

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: PAA Scale Inhibitor Market to Grow at 5.2% CAGR, Hit USD 452.6M by 2032

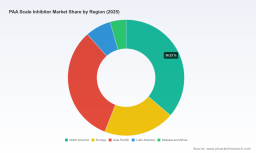
PAA Scale Inhibitor Market — Strategic Preview for 2026 Decision‑Makers
As PW Consulting’s Chief Industry Analyst, I present a forward‑looking primer on our PAA (polyacrylic acid) scale inhibitor market study — a tactical briefing designed to orient senior executives, M&A teams, product strategists and supply‑chain planners as they make critical 2026 decisions. This is a “trailer”: it surfaces the research’s analytical depth, strategic takeaways and practical tools while reserving detailed segment tables and proprietary model outputs for the full report.
PAA Scale Inhibitor Market
High‑level market trajectory (what the numbers tell you)
Our base year is 2025 (figures in USD Million). The PAA scale inhibitor market has demonstrated steady expansion through the historical window (2020–2025), rising from the mid‑hundreds to an estimated USD 317.0 Million in 2025. A continuation of this trend underpins our forecast for 2026–2032: the market is projected to grow at a compound annual growth rate (CAGR) of 5.2%, reaching roughly USD 452.6 Million by 2032 under the base scenario.
PAA Scale Inhibitor Market
Two implications flow immediately from this trajectory. First, growth is reliable but not explosive — creating a competitive environment where product differentiation, cost position and regulatory alignment determine winners. Second, the steady expansion window offers a runway for staged investments (product upgrades, incremental capacity, targeted partnerships) rather than all‑or‑nothing bets.
PAA Scale Inhibitor Market
Why this study matters for 2026 strategic choices
- Capital allocation and capacity planning: With predictable mid‑single‑digit growth, the optimal path for many players is phased capacity expansion linked to validated off‑take (customer trials, supply agreements) rather than broad build‑out. Our report includes templates to stress‑test capacity scenarios against price and raw‑material volatility.
- R&D priorities and product roadmaps: The market rewards PAA variants that combine thermal stability, high‑salinity performance and improved biodegradability. Recent vendor launches highlight this axis; firms that can translate laboratory advantage into field performance will capture premium positioning.
- M&A and partnership targeting: Moderate market concentration (with leading groups collectively accounting for a material share of revenue) creates opportunities for bolt‑on acquisitions and contract manufacturing strategies to secure regional supply and technical IP.
- Regulatory and sustainability positioning: Evolving water‑treatment permitting and corporate ESG mandates are tilting buyer preference toward formulations with documented biodegradation profiles and lower environmental persistence. This is now a procurement screen — not just a differentiator.
Market dynamics shaping 2026 negotiations and investments
Several demand and supply forces will shape commercial outcomes in 2026:
- Operational performance requirements: Operators in energy, petrochemical and industrial water systems increasingly demand inhibitors that perform under higher temperatures and salinities while minimizing sludge and deposit formation. Field reliability drives multi‑year supplier relationships.
- Environmental and permitting constraints: Biodegradability claims are being scrutinized by regulators and customers. Suppliers investing in greener chemistries gain not only compliance benefits but commercial leverage in tendering processes.
- Supply‑side moves: Capacity expansions and product launches announced by major producers are tightening lead times for differentiated grades. Buyers should anticipate both spot availability swings and outcome‑based contracting (performance guarantees, shared pilot costs).
- Pricing dynamics: Feedstock and logistics volatility remain sources of margin pressure; successful players will adopt agile pricing mechanisms and hedging strategies to defend profitability.
Competitive landscape — who to watch
The competitive map is defined by a handful of established chemical majors and specialty polymer firms that combine product portfolios, application know‑how and global supply capacity. Key companies profiled in our study include:
- BASF SE (Ludwigshafen, Germany) — market leader in specialty acrylate chemistries; markets Sokalan® acrylic homopolymers positioned for scale control and dispersion in cooling and process waters. Recent R&D developments (April 2026) include next‑generation PAA inhibitors targeting improved biodegradability and thermal resilience.
- Dow Inc. (Midland, Michigan, United States) — offers the Acumer™ family of low molecular weight polyacrylic acids designed for carbonate and sulfate scale management; strong channel presence in industrial water treatment and oilfield applications.
- Lubrizol Corporation (Cleveland, Ohio, United States) — markets water‑soluble PAA polymers (Carbosperse™ series) with emphasis on deposit control and particulate dispersion; recognized for application engineering and service support.
- Solvay S.A. (Brussels, Belgium) — supplies PAA‑based inhibitors tailored for high‑temperature desalination and industrial scale control; notable for high‑temperature performance claims and technical collaborations.
Recent vendor activity underlines the strategic vectors of the next 24 months: BASF’s 2026 product introductions emphasize biodegradability and thermal stability; Kemira’s early‑2026 polymer developments target extreme salinity environments; and capacity expansions by producers such as SNF in 2025 demonstrate preparedness for rising industrial demand. These moves confirm that incumbents are both defending share and pushing performance boundaries.
Practical insight: what the full report delivers
Our PAA Scale Inhibitor Market report is designed for immediate use in boardrooms, commercial planning cycles and M&A diligence. Practical components include:
- Comprehensive market sizing and a 2026–2032 forecast model (figures in USD Million) with scenario toggles for low, base and high cases.
- Vendor scorecards that synthesize technical capabilities, geographic reach, price positioning and recent strategic moves (product launches, capacity changes, partnerships).
- Go‑to‑market playbooks: customer segmentation, procurement RFP templates, sample contractual clauses for performance‑based procurement, and pilot design checklists.
- Supply‑chain heat maps highlighting raw‑material dependency, logistics risk and recommendations for supplier diversification.
- Regulatory and ESG impact analysis with compliance checklists and timelines to assess go‑to‑market risk.
- Financial readiness tools: capital planning templates, capex/opex impact scenarios for capacity expansions, and sensitivity analyses to commodity swings.
Note: In keeping with this document’s “trailer” role, detailed regional and application breakdowns, company revenue splits and proprietary model outputs are omitted here to protect confidential methodologies and encourage direct access to the full study.
Strategic playbook for 2026 (recommended actions)
- Prioritize performance‑backed product launches: Convert lab improvements (e.g., biodegradability, thermal stability) into field‑validated case studies. Deploy joint pilot programs with strategic customers to accelerate adoption and justify premium pricing.
- Adopt staged capacity expansion: Link any production increases to validated off‑take agreements and include contractual flex to manage demand uncertainty. Consider toll‑manufacturing or contract manufacturing to reduce capital intensity.
- Negotiate outcome‑based contracts: Structure supply deals around measured performance metrics (scale reduction, downtime avoided) to differentiate offerings and capture shared value.
- Secure feedstock optionality: Hedge critical monomer inputs through supplier agreements or vertical integration where economically viable; this mitigates margin erosion from raw‑material spikes.
- Invest selectively in sustainability credentials: Prioritize certifications and third‑party biodegradability testing that matter to buyers and regulators — these investments pay off as procurement criteria tighten.
- Scan for bolt‑ons: Use M&A to acquire niche technologies (e.g., extreme salinity formulations) or regional production footprints faster than organic build‑out allows.
Risks, blind spots and how the report mitigates them
Key downside risks include feedstock price shocks, accelerated regulatory shifts that render certain chemistries non‑viable, and rapid entry of low‑cost suppliers in specific regional markets. Our report addresses these by providing:
- Stress‑tested financial models that quantify margin exposure across commodity scenarios.
- A regulatory timeline with probability‑weighted impact assessments on product acceptability.
- Competitive playbooks to anticipate low‑cost entrants and recommended defensive measures (long‑term offtake, technical service agreements, co‑development).
How to use this preview — next steps
This briefing is curated to inform immediate 2026 planning: capital budgets, R&D roadmaps, procurement strategy and M&A screening. For teams preparing board packets or investor presentations, the full PW Consulting study provides the granular segmentation, primary‑research transcripts and downloadable model files needed to convert strategy into executable plans.
To access the complete dataset (including regional and application breakdowns, vendor revenue splits and the interactive forecast model), please visit the PW Consulting publication page for the PAA Scale Inhibitor Market. The full report is the only source of the proprietary segmentation and the underlying primary research that substantiate the strategic recommendations outlined here.
Closing
The PAA scale inhibitor market in 2026 is a market of disciplined growth and technical differentiation. Firms that move beyond commodity positioning — by combining robust field validation, environmental credentials and flexible supply arrangements — will capture disproportionate value. Our full study arms you with the quantitative models and transactional playbooks needed to turn these strategic observations into near‑term wins and enduring competitive advantage.
For detailed analysis of this topic, please visit the official page: PAA Scale Inhibitor Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com