

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Vinyl-Terminated Polydimethylsiloxane Market to Reach USD 904M by 2032

Vinyl Terminated Polydimethylsiloxane Market — Strategic Insights for 2026 Decision-Making
Executive summary
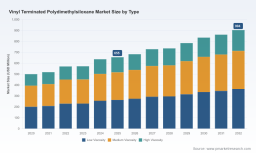
Vinyl terminated polydimethylsiloxane (VTPDMS) occupies a strategic position in silicone value chains: as a reactive intermediate it underpins addition-cure systems used across adhesives, coatings, elastomers and healthcare applications. Our PW Consulting base-year assessment (2025) values the global VTPDMS market at approximately USD 655.0 Million (Million, USD basis) having grown from roughly USD 500.0 Million in 2020. The market trajectory through the 2026–2032 forecast period is characterized by steady expansion at a compound annual growth rate (CAGR) of 4.7%, culminating in a projected market size near USD 904.0 Million by 2032.
Vinyl Terminated Polydimethylsiloxane Market
Why this study matters for 2026 corporate strategy
- Mid-single-digit CAGR masks important structural inflection points in 2026: raw-material volatility, regulatory scrutiny of key silicone precursors, and a shifting competitive footprint.
- Decisions made in 2026 about procurement contracts, R&D resource allocation, capacity expansion, and regulatory engagement will determine margin resilience and commercial positioning for the remainder of the decade.
- Our study converts macro growth and risk indicators into actionable choices — specifying timing, scale and sequencing for investments and mitigations needed to capture value while containing risk.
Snapshot of the historical and near-term evolution
Between 2020 and 2025 the VTPDMS market expanded materially, reflecting renewed demand in industrial silicone applications and an improving end-market environment. After a solid recovery phase in the early 2020s, 2024–2025 showed a step-up in both demand and pricing dynamics, driven in part by constrained feedstock availability. The forecast path to 2032 assumes continued demand diversification across end-use sectors and incremental adoption of specialty grades, resulting in the 4.7% CAGR noted above.
Vinyl Terminated Polydimethylsiloxane Market
What the full report delivers (practical, work-ready content)
PW Consulting’s full study is built for commercial and corporate decision-makers who need to translate market intelligence into executable plans. Highlights include:
Vinyl Terminated Polydimethylsiloxane Market
- Granular market-sizing and validated forecast model (2026–2032) with scenario toggles for raw-material shocks and regulatory outcomes.
- Demand-driver analytics by application and product-type, with quantitative elasticity models to test price, substitution and innovation impacts.
- Supply-side heatmaps: plant locations, capacity benches, logistics chokepoints, and a supplier risk matrix that factors technical substitutability and single-sourcing exposure.
- Practical go-to-market playbooks for both incumbent manufacturers and new entrants: product prioritization, channel strategies, and contract terms optimized for margin protection under volatility.
- Regulatory-impact assessment and stakeholder engagement templates: modeling the potential consequences of precursor restrictions and compliance pathways across major jurisdictions.
- Commercial templates — procurement hedging strategies, cost-pass-through mechanisms, and price escalation clauses tailored to silicone intermediates.
- Competitive intelligence dossiers on leading companies, plus a prioritized M&A and partnership target list with synergy levers quantified.
Note: this preview intentionally omits the full regional- and application-level split tables; those detailed segment matrices and downloadable data dashboards are available in the complete report package.
Competitive landscape — practical implications
The VTPDMS supplier universe blends specialty chemical producers, regional manufacturers, and distributors. Market concentration is moderate: the three largest suppliers account for a meaningful minority of volume, and the top five enlarge that share but leave substantial room for agile specialists and regional champions. This structure produces both competitive pressures and opportunities:
- Specialty suppliers with application-focused portfolios (product development, small-batch customization, and technical support) can command premium positioning where formulation performance or regulatory traceability matters.
- Distributors and stocking partners offer speed-to-market advantages for industrial customers that prioritize short lead times over lowest unit cost.
- Lower-cost regional producers can contest high-volume, price-sensitive segments by leveraging local feedstock access and operating-cost advantages.
Representative firms profiled in our study include established specialty players and several China-based manufacturers and distributors. Their profiles illustrate three archetypal go-to-market models: (1) specialty R&D-led producers that support formulation development, (2) bulk-volume manufacturers with emphasis on scale and cost, and (3) distributors that combine inventory availability with technical-grade stocking. Each model implies different partnership or competitive responses for buyers and investors.
Supply chain and regulatory dynamics shaping 2026 actions
- Feedstock dependency: Octamethylcyclotetrasiloxane (D4) remains a primary building block for VTPDMS. In 2026 D4 is subject to growing regulatory attention in several jurisdictions; pending evaluations can alter manufacturing economics, availability and compliance costs. The full report models plausible regulatory scenarios and quantifies impact on margins and supply symmetry.
- Price pressure on intermediates: Silicon tetrachloride — a key intermediate in several silicone production routes — registered a material price increase in early 2026 and sustained that trajectory. Rising energy costs and constrained regional availability are amplifying cost pass-through risk for producers.
- Operational exposure: Energy intensity of certain upstream processes, concentration of specific plants, and logistics bottlenecks create asymmetric risks. We identify the production nodes where a single disruption would most materially affect global supply.
Strategic implications and recommended actions for 2026
Our analysis translates market trends and risks into prioritized, time-bound actions for executives and commercial leads:
- Procurement & supply continuity — near term (0–12 months): Lock tiered supply agreements with dual-source clauses; establish strategic buffer inventory for critical intermediates; negotiate index-linked pricing mechanisms to share downside of immediate feedstock swings.
- Regulatory & stakeholder engagement — immediate to short term: Proactively engage with regulators and industry associations on D4 risk evaluations; sponsor or participate in technical studies that inform risk assessment to avoid binary policy outcomes.
- Product & commercial strategy — 2026 planning cycle: Prioritize development of higher-value, differentiated VTPDMS grades with clear value-in-use metrics (e.g., cure speed, compatibility, reduced VOCs). Deploy application-targeted go-to-market pilots in adhesives, elastomers and healthcare segments where performance premiums are achievable.
- Operational resilience & CAPEX — 12–36 months: Evaluate near-shore/backward-integration opportunities for intermediates where feedstock risk is concentrated; condition CAPEX on scenario triggers modeled in our stress-testing toolkit to avoid overcommitment in a volatile raw-material environment.
- M&A & partnerships — 2026–2028 window: With moderate concentration, targeted acquisitions of technical-capability players or regional producers offer scale and route-to-market benefits; our report identifies criteria for attractive targets and expected payback timelines under conservative demand forecasts.
- Sustainability & market differentiation — continuous: Embed lifecycle transparency into product offerings to preempt regulatory scrutiny and appeal to formulators in regulated end-markets, notably healthcare.
What to watch in the next 12 months
- Regulatory milestones related to D4: outcomes will materially influence sourcing, cost, and the feasibility of certain manufacturing routes.
- Feedstock price volatility: continued upward movement in silicon tetrachloride or energy costs would compress producer margins and accelerate cost pass-through negotiations.
- Commercial responses: shifts in supplier stocking behavior, new long-term contracts, or selective exit of marginal capacity will create windows for market share shifts — our monitoring dashboard tracks these signals in near real time.
How PW Consulting supports your 2026 decisions
We partner with chemical producers, formulators, and corporate development teams to translate the intelligence in this study into executable plans. Our services include:
- Custom scenario modeling (your cost base and customer mix) to determine optimal hedging and CAPEX timing.
- Negotiation support for long-term supply agreements and price-index frameworks tailored to silicone intermediates.
- Targeted commercial due diligence and integration playbooks for M&A opportunities identified in our sector screening.
- Regulatory strategy and stakeholder engagement roadmaps to help shape outcomes and preserve supply chain continuity.
Next step — obtain the headroom-level intelligence
This briefing provides the strategic framing and primary implications you need to prioritize 2026 decisions. Our full report contains the detailed segment matrices, regional and application-level demand models, supplier scorecards and downloadable forecasting workbooks that underpin the recommendations summarized above. For teams needing an accelerated decision package (executive dashboards, supplier negotiation templates, and scenario-adjusted financials), PW Consulting can deliver a tailored suite within a 2–6 week engagement.
Contact PW Consulting to access the complete Vinyl Terminated Polydimethylsiloxane Market report and tailored advisory services — gain the full data tables, proprietary scenario outputs, and tactical toolkits required to act with confidence in 2026.
For detailed analysis of this topic, please visit the official page: Vinyl Terminated Polydimethylsiloxane Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com