

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting Insight: Automatic Lubrication Systems Market Poised for 4.95% CAGR (2026-2032)

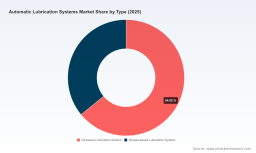
Automatic Lubrication Systems Market: Strategic Outlook for 2026
As PW Consulting’s Senior Strategic Advisor and Chief Industry Analyst, I present a forward-looking briefing designed to translate our Automatic Lubrication Systems Market study into high‑impact decisions for 2026. Built on a base year of 2025 with historical context from 2020–2025 and a detailed forecast covering 2026–2032, the report synthesizes quantitative market sizing, competitive mapping, regulatory and cost dynamics, and scenario-based guidance—delivered with the clarity business leaders need to act, while reserving the full granular intelligence for our full report.
Automatic Lubrication Systems Market
Why this study matters for 2026 decision cycles
Procurement calendars, capital planning, product roadmaps, and inorganic growth pursuits that kick off in 2026 must be calibrated against a market that is expanding steadily. Our topline market model places the global automatic lubrication systems market at approximately USD 952.3 million in 2025, with a projected rise to roughly USD 1,335.6 million by 2032—a compound annual growth rate (CAGR) of about 4.95% through the forecast horizon. This trajectory is material: it sustains attractive returns for both incumbent suppliers and new entrants while exposing firms to competitive pressure and margin volatility driven by raw material and geopolitical risk.
Automatic Lubrication Systems Market
For executives, the practical implication is straightforward: strategic choices made in 2026—whether on capacity investment, channel expansion, digital product development, or price positioning—will disproportionately determine market share capture across a multi-year growth arc that is meaningful but not explosive. That requires a measured blend of offensive investments and defensive hedges.
Automatic Lubrication Systems Market
What the report delivers (practical, action-ready content)
- Proprietary market-sizing and trend decomposition by year (2020–2025 historical baseline; 2026–2032 forecast scenarios), combining bottom‑up reconciliations and top‑down sanity checks.
- Demand-driver analytics mapping: automation adoption, safety and environmental regulation, OEM retrofit cycles, and aftermarket service economics, with quantified sensitivity to key variables.
- Cost‑structure and margin playbook that models raw material and logistics inputs, labor exposure, and tariff shocks—enabling margin stress testing and price response strategies.
- Competitive landscape and capability assessment, including capability heatmaps (product breadth, digital maturity, distribution reach, service model), vendor benchmarking, and a CR‑based concentration analysis.
- Go‑to‑market templates for industrial OEM partnerships, channel acceleration, and aftermarket service monetization—complete with sales force ROI calculators and payback timelines.
- M&A and partnering intelligence: target profiles, integration risk matrices, and value-creation roadmaps for bolt‑on and transformational deals.
- Regulatory and sustainability impact analysis covering workplace safety mandates, emissions and waste management, and industrial standards—along with compliance cost scenarios.
- Three scenario models (base, upside, downside) and sensitivity tables that allow rapid re‑forecasting for procurement planners and finance teams as costs, tariffs, or demand indicators change.
Market structure and concentration: strategic implications
The market presents a moderately concentrated competitive structure—three leading players capture a clear plurality of market share while the top five exert material control. That dynamic creates an environment where scale, channel depth, and service infrastructure drive advantage, but specialist innovators and regionally focused players can still carve durable niches by owning technical differentiation or aftersales economics.
For market leaders, the immediate priority is to convert scale into stickiness: integrated service contracts, digital predictive‑lubrication offerings, and bundled system‑plus‑consumable arrangements raise lifetime customer value. For challengers, the path to disproportionate returns lies in concentrating on underserved vertical use‑cases, differentiated single‑point or multi‑point solutions, and strategic partnerships with OEMs and aftermarket distributors.
Competitive positioning: what incumbent leaders are doing
- Groeneveld‑BEKA (Netherlands): A global systems and fluid management player with breadth across transportation, construction, mining, and industrial applications. Strengths include field service networks and solutions that combine hardware with lifecycle servicing—critical to defend high‑margin accounts.
- SKF Lincoln (USA): Offers a broad portfolio covering both oil‑ and grease‑based centralized systems. Its competitive edge is integration into rotating equipment ecosystems and leveraging existing bearings and reliability services to upsell automated lubrication packages.
- perma (Germany): Recognized for single‑point and multi‑point systems and accelerating its digitalization strategy; recent investments in expanded production capacity signal a push to convert demand tailwinds into volume and faster lead times.
- Bijur Delimon, Dropsa, Graco and others: These firms compete on product specialization—progressive, single‑line, dual‑line and oil/grease mixes—and are increasingly differentiating on service, digital monitoring, and aftermarket consumable supply chains.
- Regional specialists and OEM-aligned suppliers: Companies that pair compact product portfolios with intensive local service often secure higher retention rates despite smaller scale.
Recent commercial activity—trade show participation by A.T.S. Electro‑Lube, facility expansion by perma, and exhibition pushes from applied lubrication specialists—illustrates two concurrent movements: continued investment in product innovation and an intensified emphasis on field validation and customer education as purchase cycles lengthen and technical complexity rises.
Dynamics shaping value chains in 2026
- Automation as a structural demand driver: Broader industrial automation programs accelerate retrofit and OEM‑embedded opportunities, raising the value of digital monitoring and predictive lubrication modules.
- Regulatory and safety pressure: Increasing workplace safety and environmental regulation is nudging end‑users away from manual greasing practices toward automated, monitored lubrication—creating demand for integrated systems and compliance services.
- Raw material and tariff risk: Rising input costs and new trade measures (including recent tariffs affecting specific equipment classes) complicate cost planning. The report models tariff pass‑through, dual‑sourcing strategies, and on‑shore manufacturing break‑even points.
- Service and consumables economics: Aftermarket consumable flows (lubricants, cartridges, monitoring service) are a recurring revenue lever—firms that secure service contracts improve resilience against hardware price competition.
Actionable strategic priorities for 2026
- Re‑price and protect margins: Use our cost‑sensitivity module to stress test pricing under multiple tariff and raw‑material scenarios, and develop indexed contract language to preserve margins when inputs spike.
- Double down on service economics: Deploy predictive maintenance pilots that demonstrate measurable uptime and TCO improvements; convert pilots into subscription or managed‑service offers.
- Prioritize modular digital offerings: Invest selectively in telemetry and analytics that integrate with customer CMMS/ERP; focus on use cases with clear ROI (bearing life extension, unplanned downtime reduction).
- Localize strategically: Where trade measures or logistics costs bite, evaluate targeted local assembly or co‑manufacturing to shorten lead times and reduce tariff exposure.
- Pursue bolt‑on M&A with an eye to aftermarket scale: Targets should accelerate service delivery, broaden consumable distribution, or add digital capabilities—capture synergies before price competition intensifies.
- Embed compliance as a sales lever: Build selling propositions that quantify regulatory compliance benefits and reduced exposure to safety penalties.
How to use this intelligence in your 2026 planning cycle
Procurement, product, and corporate development leaders should integrate the report outputs into three concrete planning artifacts:
- CapEx decision memo: Use the base and downside scenarios to justify capacity investments, including sensitivity to tariff/re‑shoring outcomes.
- Commercial playbook: Translate benchmarking into sales motions—target accounts where digital lubrication yields demonstrable OEE gains and prioritize field demonstrations tied to contract pilots.
- M&A target shortlist and integration checklist: Filter prospects by recurring revenue percentage, service network overlap, and technical fit for your product stack.
Next steps and how to access the full intelligence
This briefing highlights the levers and strategic choices that will shape winners in 2026. The full PW Consulting Automatic Lubrication Systems Market report expands each section with detailed models, vendor scorecards, playbook templates, and downloadable scenario spreadsheets—the kind of granular inputs finance teams and business unit leaders will use to finalize 2026 budgets.
For executive teams preparing strategy sessions, the report functions as both a benchmarking tool and a decision accelerator: it tells you where returns will be concentrated, where risk must be hedged, and what capability investments will create sustainable differentiation.
Closing: positioning for durable advantage
The automatic lubrication market is in a structural growth phase that rewards companies that can combine technical excellence with a service‑centric go‑to‑market. In 2026, success will favor operators that move beyond hardware sales to own lifecycle economics—through digital monitoring, consumables supply, and compliance-backed value propositions—while actively managing cost and geopolitical risks. PW Consulting’s full study equips leadership teams with the numbers, scenarios, and tactical roadmaps to make those choices with confidence.
For detailed analysis of this topic, please visit the official page: Automatic Lubrication Systems Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com