

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Thermal Management Market to Reach USD 23,800M by 2032 at 8.1% CAGR

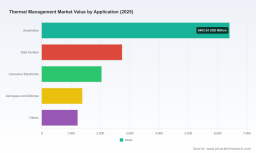
Thermal Management Market — 2026 Strategic Preview for Decision-Makers
Executive overview
Thermal management is no longer a niche engineering discipline — it is a strategic lever shaping competitiveness across data centers, electric vehicles, advanced semiconductors, and industrial electrification. PW Consulting’s Thermal Management Market study (base year 2025; historical 2020–2025; forecast 2026–2032) documents a sustained expansion trajectory with an 8.1% compound annual growth rate and an addressable market rising from USD 13,800 Million in 2025 toward the low‑twenty‑thousands by 2032. For corporate leaders planning capital allocation, product roadmaps, or M&A activity in 2026, the report crystallizes where value pools are expanding, where risk is concentrating, and what capabilities separate winners from also‑rans.
Thermal Management Market
Why 2026 is an inflection year
-
AI‑driven compute growth. Hyperscale and enterprise AI workloads are accelerating the shift from air to liquid and hybrid cooling architectures. The result: rapid demand for high‑density cooling stacks, integration services, and longer lifecycle management models.
Thermal Management Market -
Electrified mobility and power densification. EV thermal subsystems, power electronics, and battery cooling are maturing from component experiments into volume supply chains — creating new OEM requirements for durability, packaging, and supplier qualification.
Thermal Management Market -
Regulatory and standards pressure. New environmental regulations (notably upcoming controls on high global‑warming‑potential refrigerants effective early 2027) and formalized ISO standards for data center thermal management are compressing development timelines and raising compliance costs for refrigerant‑dependent solutions.
-
Supply‑side concentration and component scarcity. Critical inputs — high‑performance thermal interface materials (TIMs), specialized hoses and fittings, and micro‑channel plates — are experiencing demand surges. This creates both margin compression for incumbents and arbitrage opportunities for vertically integrated players.
What this preview reveals — and deliberately withholds
In keeping with PW Consulting’s “trailer” approach to thought leadership, this article surfaces strategic conclusions, competitive dynamics, and proven decision frameworks while deliberately omitting the granular segment and regional share tables that drive tactical sourcing and go‑to‑market decisions. The full research package contains the precise segment allocations, regional demand maps, and SKU‑level forecasts that revenue and procurement teams need to act in 2026; this preview is designed to establish confidence in the analysis and to prompt targeted follow‑up for the actionable detail.
What the full report delivers (practical, transaction‑ready content)
-
Robust market sizing and methodology: transparent assumptions, sensitivity analyses, and scenario outputs covering 2026–2032 under multiple macroeconomic and regulatory pathways.
-
Go‑to‑market playbooks: customer segmentation, channel strategies, pricing models (capex vs. opex), and service bundling templates tested with operator interviews.
-
Technology roadmaps and adoption curves: timing and risk for conduction, convection, liquid and hybrid solutions across high‑growth applications.
-
Supplier scorecards and procurement playbooks: component criticality matrices, single‑source risk heatmaps, and recommendations for hedging raw‑material inflation (TIMs, hoses, coolants).
-
Competitive benchmarking and M&A playbook: valuation multiples, integration risk checklists, and prioritized bolt‑on targets for consolidation or capability acquisition.
-
Regulatory compliance toolkit: preparedness steps for refrigerant phase‑downs, ISO alignment checklists for data center cooling, and lobbying/standards engagement roadmaps.
-
Operational pilots and ROI models: sample pilot designs for AI data center cooling and EV thermal packs, with break‑even timelines and total cost of ownership scenarios under alternative refrigerant and cooling architectures.
Competitive landscape — thematic analysis of leading players
The market shows moderate fragmentation: the top three and top five players account for a minority share of the market, indicating sizable room for consolidation but also meaningful niches where specialists can sustain premium positions. Across incumbents and challengers, four strategic moves dominate:
-
Systemization (hardware + software). Companies are moving from component sales to integrated, instrumented systems with real‑time thermal telemetry and predictive analytics. Players offering both the physical cooling stack and software (or open APIs for hyperscaler integration) enjoy stickier contracts and recurring revenue potential.
-
Liquid cooling leadership. Firms focusing on direct‑to‑chip liquid cooling, micro‑channel plates, and plate‑and‑frame solutions are capturing disproportionate attention from AI and HPC customers. Specialist suppliers that can meet leakage, serviceability, and redundancy requirements are in a strong negotiating position.
-
Vertical integration and component ownership. Control over TIMs, hoses, and coolant chemistries materially improves margin control and supply reliability. Strategic acquisitions and partnerships for key components are becoming mainstream.
-
Service‑led offerings. Providers bundling commissioning, monitoring, and lifecycle services (including refrigerant stewardship) create differentiated, defensible propositions versus pure hardware vendors.
Player spotlights — positioning and competitive implications
-
Vertiv — Focused on adaptive air, liquid and hybrid systems with an emphasis on data center reliability. Their strength is large‑scale deployments and operational services; the strategic question for customers is whether to accept a vertically integrated platform or to maintain modularity in supplier relationships.
-
Schneider Electric — Combines modular liquid cooling with software stacks for power and thermal orchestration. Their ecosystem approach is optimized for HPC and AI workloads, but integration complexity increases time‑to‑value for some enterprise buyers.
-
Johnson Controls — With traditional chiller and hyperscale cooling assets, Johnson Controls is scaling into data center thermal management via acquisitions and platform plays — a strategy that accelerates capability delivery but requires disciplined integration to protect margins.
-
Component specialists (Boyd, Advanced Thermal Solutions, CoolIT, Calyos, Dow, Gates, Indium) — These firms own the technology primitives that system integrators need: liquid cold plates, TIMs, hoses, and coolant chemistries. Their bargaining power rises as system OEMs prioritize performance and reliability.
Recent strategic movements and what they signal
-
Notable acquisitions in 2026 reflect active consolidation: integration of advanced liquid cooling capabilities into broader power and infrastructure platforms is accelerating. Expect further bolt‑on activity as incumbents buy time‑to‑market and component control.
-
Industry events and exhibitions illustrate technology maturation: component vendors are increasingly targeting test and integration forums to shorten qualification cycles with OEMs and hyperscalers.
-
Regulatory timelines are hardening: the announced regulatory schedule for refrigerants creates a narrow window for technology transition planning, supplier qualification, and inventory strategies.
Strategic imperatives for 2026 — actionable recommendations
-
For incumbents: Prioritize system + service bundles that monetize performance monitoring. Use 2026 to solidify long‑term service agreements with hyperscalers and carriers — these contracts lock in revenue streams and smooth adoption risk for liquid solutions.
-
For component specialists: Consider selective vertical integration or long‑term supply agreements to capture more of the lifecycle value. Invest in qualification programs that reduce OEM integration lead times.
-
For OEMs (automotive, aerospace): Build dual‑sourcing plans for critical TIMs and micro‑channel components; accelerate in‑vehicle thermal validation cycles to align with program launches and to avoid downstream recalls tied to thermal degradation.
-
For private equity and strategic buyers: Screen targets for platform fit, component ownership, and software telemetry capabilities. Our M&A playbook highlights acquisition thresholds where integration yields immediate margin expansion versus long integration drag.
-
For data center operators: Pilot direct‑to‑chip liquid cooling on high‑intensity racks, pairing the pilot with contractual metrics for leakage, MTTR, and PUE improvement. Factor refrigerant transition timelines into procurement cadences to avoid stranded inventory.
-
For all players: Embed regulatory scenario planning into product roadmaps (especially refrigerant phase‑down scenarios), and allocate R&D budgets to low‑GWP solvent chemistries, TIM longevity, and leak‑resilient connectors.
Decision‑making toolkit and next steps
Painstaking detail separates strategic intent from profitable execution. PW Consulting’s full Thermal Management Market report provides the operational templates and quantified scenarios that enable executable 90‑day plans, 12‑month product roadmaps, and multi‑year M&A pipelines. Deliverables include:
-
Executive dashboards with scenario toggles (regulatory, demand, component pricing).
-
Priority target lists for bolt‑ons and strategic partnerships, scored on capability, cultural fit, and time‑to‑synergy.
-
Procurement mitigation tactics and supplier co‑development frameworks designed to lock in TIM and hose supply through 2028.
-
Pilot templates and ROI calculators for AI data center cooling and EV thermal subsystems to de‑risk capital approval processes.
Closing — how to use this preview
Use this preview as your strategic checklist for 2026: align R&D to low‑GWP chemistries and liquid cooling architectures, shore up component supply, and evaluate accretive M&A where capability gaps slow time‑to‑market. For teams preparing board materials, investment committees, or commercial launch plans, the complete PW Consulting report supplies the granular segment maps, regional demand dashboards, and supplier economics that convert strategy into executable programs. Contact PW Consulting to access the full analysis, scenario models, and transaction playbooks that will inform high‑confidence decisions through 2026 and beyond.
For detailed analysis of this topic, please visit the official page: Thermal Management Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com