

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Optical Fiber Patch Cord Market to Hit USD 305.9M by 2032 (5.35% CAGR)

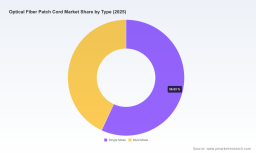
Optical Fiber Patch Cord Market — Strategic Briefing for 2026 Decision-Makers
As enterprises and infrastructure owners build roadmaps for 2026, the optical fiber patch cord market presents a measured but strategically pivotal growth corridor. Our latest study frames that corridor with a five-year historical baseline and a forward-looking forecast: from a market measured in the low hundreds of USD Million in 2020–2025 to a projected expansion at a compounded annual growth rate (CAGR) of approximately 5.35% across the 2026–2032 horizon, culminating in a market size north of three hundred million USD by 2032. For senior leaders weighing supplier commitments, product investments, or M&A within fiber connectivity, this study is purpose-built to convert macro momentum into executable decisions.
Optical Fiber Patch Cord Market
Why this study matters in 2026
-
Timing investments: The next 12–24 months will crystallize vendor positions around high-density data center solutions, low-loss single-mode offerings, and ruggedized outdoor connectors. Knowing where demand concentration and technological differentiation lie is critical for capital allocation.
Optical Fiber Patch Cord Market -
Supply chain resilience: Component and labor cost dynamics are shaping margins and lead times. A granular understanding of raw-material exposure and skilled labor dependence is essential to mitigate delivery risk.
Optical Fiber Patch Cord Market -
Regulatory and interoperability compliance: New deployments must adhere strictly to international cabling and environmental standards — non-compliance is a commercial and reputational risk.
-
Competitive positioning: Hyperscaler, enterprise, and telecom buyers are shifting procurement preferences toward performance-differentiated patch cords. Vendor roadmaps matter as much as price.
Market trajectory and what the headline numbers tell you
The market’s recent past shows steady growth from 2020 through 2025, with a clear acceleration in 2023–2025 as data center reconfiguration and 5G rollouts increased demand for higher-performance patch cords. Projecting forward under base-case assumptions — including continued hyperscale housing expansion, ongoing fiberization of mobile networks, and incremental enterprise refresh cycles — the market grows at roughly a mid-single-digit CAGR through 2032. This pace implies a market that is large enough to sustain meaningful supplier specialization yet not so concentrated that nimble entrants cannot carve profitable positions.
Concentration metrics underline that tension: the three- and five-firm concentration ratios indicate a marketplace where global leaders capture a significant share of volume, but a long tail of regional specialists and component-focused players remains commercially relevant. For corporate strategists this means dual-track commercial plays — maintain relationships with large global vendors while cultivating niche or local partners for differentiated requirements.
Core dynamics shaping 2026 procurement and product strategy
-
Performance differentiation — Low-loss and bend-insensitive fiber technologies are moving from “premium” to “must-have” for AI-optimized and hyperscale networks. Vendors investing in ultra-low-loss offerings create clear procurement value, particularly where link budgets are tight.
-
Density and manageability — High-density MTP/MPO assemblies and hybrid data-power cord concepts reduce rack footprint and installation time, becoming decisive in dense deployments.
-
Ruggedization — Outdoor and FTTA deployments are driving demand for IP67-rated and harsh-environment patch cords. Waterproof and sealed connector formats are increasingly required in field roll-outs.
-
Standards and compliance — ISO/IEC 11801, TIA-568 family standards, IEC fiber specifications, plus environmental mandates such as RoHS and REACH, form the non-negotiable baseline for spec’ing components and negotiating warranties.
-
Cost structure realities — Two structural inputs matter for margin and sourcing strategy: skilled termination and testing labor typically contribute a mid-teen share of assembly cost, while raw single-mode fiber as a material component represents a larger, high-single-digit to low-double-digit share of the finished assembly cost. These levers are actionable through automation, localized assembly, and indexed supplier contracts.
What the report contains — practical, decision-ready modules
-
Market sizing and scenario models: transparent methodology, historical calibration (2020–2025), and base / downside / upside forecasts to 2032.
-
Demand segmentation frameworks: buyer archetypes, application profiles, and a modular approach to estimating addressable demand by use case (full data available in the report).
-
Cost build-up and margin analysis: line-item assembly, material, and labor composition with stress-tests for commodity shifts and labor localization scenarios.
-
Regulatory and standards compliance matrix: mappings to ISO/IEC, TIA, IEC and environmental rules that matter for procurement, QA, and warranty clauses.
-
Vendor due-diligence toolkit: scorecards for technology maturity, manufacturing footprint, QA capabilities, and after-sales support.
-
Go-to-market playbooks: actionable strategies for vendors and buyers — procurement templates, risk mitigation measures, and rollout sequencing for pilot-to-scale migrations.
-
Strategic options analysis: acquisition targets, partnership archetypes, and capability build vs. buy decision trees with NPV sensitivity ranges.
Competitive landscape — who is shaping the market
The vendor field spans vertically integrated global manufacturers, connectivity specialists, industrial automation suppliers, and regional OEMs. A brief strategic read of major players in our coverage set:
-
Corning Incorporated — a vertically integrated leader with a portfolio spanning fiber to finished patch cords; recent product activity includes ultra-low-loss single-mode releases aimed at hyperscale and AI workloads. Corning’s combination of materials science and scale makes it a bellwether for margin and technology benchmarks.
-
CommScope — focused on high-density solutions for hyperscale data centers; their March 2025 launch of improved MTP systems emphasizes fiber management and installation efficiency as a differentiator in large-scale deployments.
-
Panduit and Belden — structured cabling incumbents that compete on standardized, installation-friendly products and enterprise channel reach; Panduit’s hybrid data-power patch cords illustrate convergence plays that simplify rack-level engineering.
-
YOFC, ZTE, Huawei and other China-based suppliers — broad manufacturing scale, competitive pricing, and rapid product iterations, including outdoor waterproof connectors and integrated solutions for FTTA and 5G front-haul.
-
Specialists such as Optical Cable Corporation (OCC), Phoenix Contact, Sumitomo, Amphenol, CRXCONEC and Bonelinks — each occupies niches such as ruggedized connectors, industrial automation-grade components, premium bend-insensitive designs, and compliant FTTH product ranges. Recent vendor activity has emphasized incremental innovations: LED-assisted installation, waterproof ODC-style cords, and improved attenuation performance.
Strategic implications and recommended actions for leadership in 2026
-
Adopt a two-tier supplier strategy: secure long-term capacity with tier-one global vendors for volume and lead-time predictability, while qualifying regional or niche suppliers for specialized product requirements and price leverage.
-
Demand specification harmonization: standardize procurement specs around compliance (ISO/IEC, TIA), testable performance metrics (insertion loss, return loss, bend performance), and installation efficiency attributes (pre-terminated lengths, hybrid designs).
-
Mitigate input-cost exposure: negotiate material-indexed long-term agreements for fiber and critical components, and explore localized assembly or automation to compress labor contribution to cost.
-
Prioritize product R&D in three areas: ultra-low-loss single-mode for extended reach links, high-density MPO systems for rack efficiency, and ruggedized/IP-rated connectors for outdoor and FTTA use cases.
-
Embed compliance and QA gates into procurement contracts: ensure traceability for RoHS/REACH, ISO test certificates, and field-retest protocols as part of acceptance criteria.
-
Use M&A and partnership selectively: target bolt-on capabilities in ruggedized outdoor connectors, optical components with bend-insensitive profiles, or software-enabled fiber management — rather than chasing volume-only playbooks.
What we’re deliberately withholding here (the “trailer” approach)
This briefing is intentionally selective: it reveals high-confidence market direction, supplier dynamics, and actionable frameworks, but it omits the granular regional and application split tables, detailed company revenue breakdowns, and the full price and margin curves that underpin scenario modelling. Those datasets — including the segmented demand tables, SKU-level pricing curves, and vendor-specific revenue footprints — are available in the full study and are designed to support procurement negotiations, investment memos, and board-level decisions.
How to mobilize this insight over the next 90 days
-
Immediate (0–30 days): Run a supplier risk audit using our vendor scorecard; prioritize critical SKUs for dual-sourcing pilots.
-
Short term (30–60 days): Update technical specifications and procurement templates to incorporate mandatory compliance clauses and performance acceptance criteria.
-
Medium term (60–90 days): Pilot a cost-reduction initiative — evaluate localized assembly, automate selective termination processes, and negotiate indexed supply agreements for fiber inputs.
PW Consulting’s Optical Fiber Patch Cord Market study distills market-scale forecasts, practical cost models, regulatory roadmaps, and vendor playbooks into a single resource designed to accelerate clear, defensible decisions in 2026. For teams preparing procurement rounds, capex submissions, or competitive positioning papers, the full report supplies the underlying data tables, SKU-level analytics, and vendor revenue detail that drive executable outcomes. Access the complete study to convert the high-level strategies in this briefing into operational plans and quantified financials.
For detailed analysis of this topic, please visit the official page: Optical Fiber Patch Cord Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com