

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Plastic Bearings Market at USD 11,900M in 2025, 4.0% CAGR to 2032

Plastic Bearings Market: Strategic Intelligence Briefing for 2026 Decision-Makers
Executive snapshot
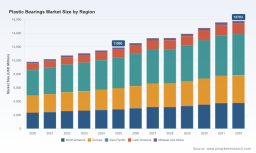
As companies set strategy for 2026, the plastic bearings market presents a predictable yet evolving opportunity: steady expansion driven by materials innovation, light-weighting trends in mobility and automation, and near-term supply-side constraints. Our PW Consulting baseline revises the market to a 2025 base-year size of USD 11,900 Million and models a compounded annual growth rate (CAGR) of 4.0% for the 2026–2032 forecast window. Under the central scenario, the market progresses toward a low-to-mid teens of billions by the late 2020s, reflecting both mature industrial demand and pockets of accelerated adoption in high-value applications.
Plastic Bearings Market
Why this study matters in 2026
-
Decision clarity in a consolidating segment: The market exhibits measurable concentration among leading manufacturers (the top three firms account for a majority share, with the top five further increasing consolidation). That structure affects pricing dynamics, supplier leverage, and M&A opportunity sets for both strategic and financial buyers.
Plastic Bearings Market -
Cost and availability forces are reshaping sourcing strategies: Polymer feedstock and processed plastic indices have moved upward in 2026, exerting upward pressure on raw-material availability and cost. Firms that lock flexible supply arrangements or redesign product stacks for material efficiency will preserve margin and deployment speed.
Plastic Bearings Market -
Regulatory shifts are altering market access: New quality and certification mandates in key markets introduce both compliance costs and barriers to entry — and, critically, create first-mover advantages for suppliers that align product portfolios and quality systems early.
Market evolution: Data-driven trends to inform capital allocation
Historic performance through 2025 shows steady expansion from the early-decade baseline, driven by diffusion of engineered polymers into traditional metal-bearing roles and greater acceptance of maintenance-free polymer solutions in automation and consumer-facing products. The modeled 4.0% CAGR for 2026–2032 is deliberately conservative relative to headline disruption scenarios; it reflects balancing forces of continued application migration and near-term supply-cost headwinds.
For 2026 planning, this implies three practical takeaways for capital allocation:
-
Prioritize investments that enhance unit economics under higher raw-material costs — for example, tooling and process improvements that enable thinner-wall designs or multi-material molding to reduce resin consumption.
-
Allocate development budgets toward higher-margin specialty segments where polymer bearings deliver unique performance or regulatory compliance value; these segments will outpace the aggregate market in margin expansion despite slower unit growth.
-
Consider bolt-on M&A that increases scale in regions or product niches where existing suppliers hold entrenched distribution channels and certification footprints — consolidation can be an accelerant for margin recovery in a tighter material-cost environment.
Competitive landscape: who shapes the market and how
The competitive set blends large, integrated polymer-specialist groups and nimble custom manufacturers. Market concentration metrics indicate a moderately concentrated market: the three largest competitors control a clear majority of value, and the top five extend that control significantly. This layered concentration yields predictable competitive behavior — price leadership by incumbents on standard SKUs, and premium pricing for engineered, certified solutions.
-
Igus (Köln, Germany) — Igus stands out as a motion-plastics specialist with a volume-oriented, engineered-polymer play. Their injection-molded iglidur® bearings target high-load, maintenance-free industrial use cases in automation and robotics. Igus’ scale in mold design and automated production positions them to compress unit costs in mainstream industrial automation applications, while their strong branded portfolio supports aftermarket and replacement channels.
-
GGB (Torrington, CT, USA) — GGB brings competency in metal-polymer and thermoplastic composite plain bearings, with proven credentials in automotive and heavy-duty industrial environments. Their engineering focus on composite formulations and tribological performance makes them a natural incumbent for applications requiring hybrid load-bearing and wear characteristics.
-
Trelleborg AB (Sweden) — Trelleborg’s strength lies in polymer and composite solutions for extreme environments, including aerospace and marine. Their customer base tends to value qualification depth and long-certification lifecycles — factors that raise barriers for new entrants but favor suppliers that invest in compliance and engineering partnerships.
-
BNL (USA) — A North American supplier that actively engages in trade events and industry forums; their visibility at The Bearing Show in Detroit (March 2026) signals an outward commercial push to capture OEM and after-market opportunities in the region. Providers with an active trade presence are likely to accelerate commercial adoption through relationship-driven channels.
-
Hartford Technologies (USA) — A custom and drop-in replacement specialist emphasizing recreational and industrial assemblies. Firms like Hartford succeed by leveraging application-specific know-how and flexible manufacturing to serve smaller, fragmented demand pockets that larger players may overlook.
Industry dynamics shaping supplier and buyer strategy
-
Raw material pressure and supply-side tightness. Public indices have shown increases in plastic resins and processed goods, creating immediate cost pressure and intermittently constrained availability for specific polymer grades. Procurement strategies should shift from short-term price chasing to multi-factor sourcing: multi-supplier contracts, local buffer inventories for critical grades, and design-for-material substitution where feasible.
-
Regulatory and quality compliance. New mandates in certain large markets require certification and identified supply-chain traceability for bearings, including plastic types. This changes the calculus for market entry: certification costs are non-trivial but become strategic assets once obtained, shortening procurement cycles and enabling premium pricing.
-
Application-driven segmentation. While traditional industrial and automotive uses remain core, growth pockets appear in medical, food-processing, and specialized packaging applications where polymer bearings’ hygiene, corrosion resistance, and low maintenance are decisive. Each pocket has distinct qualification timelines and margin profiles.
What the PW Consulting report delivers (practical, operational outputs)
Our full study translates market observations into executable workflows for commercial and technical teams. Key deliverables include:
-
Top-down market sizing and validated bottom-up demand models covering the 2020–2032 window (base year 2025), with scenario runs that stress-test macro and raw-material assumptions.
-
Supply-chain heat maps and cost-driver analysis that isolate material, processing, and logistics risk points — with recommended mitigation playbooks for procurement and R&D.
-
Competitive benchmarking that profiles leading and emerging suppliers on technology depth, certification status, manufacturing footprint, and channel strength — designed to support supplier selection and negotiation strategies.
-
Commercial playbooks: go-to-market frameworks for launching polymer-bearing variants into priority verticals, tailored distributor strategies, and aftermarket capture plans.
-
M&A and partnership screening: a prioritized shortlist framework for targets and alliances, with financial and operational due-diligence checklists to accelerate 60–120 day execution cycles.
-
Scenario-based pricing and margin modelling that integrates polymer index trajectories and certification cost amortization to forecast profitability under alternative market outcomes.
Strategic implications and recommended actions for 2026
-
Operational resilience: Establish a cross-functional materials task force to secure critical polymer grades through multi-source agreements and conditional inventory drawdowns; use analytical forecasting to plan mold investment to minimize scrap and rework.
-
Regulatory-first product roadmaps: Prioritize obtaining regional certifications in markets where regulation is tightening, as certification becomes a competitive moat and a near-term revenue enabler.
-
Segment-led R&D: Focus development resources on higher-margin, regulated applications (medical, food processing, selective industrial niches) where qualification complexity increases switching costs.
-
Commercial acceleration: Deploy distributor and OEM engagement models that leverage trade participation and co-marketing (e.g., trade-show platforms) to shorten qualification cycles; consider hybrid pricing models to offset raw-material volatility.
-
M&A discipline: Pursue bolt-on acquisitions that increase control over key SKUs or regional certification footprints. Targets should display margin resiliency, certified product lines, and complementary channel access.
How to use this briefing in corporate planning
In 2026, plastic bearings strategy must be both defensive and opportunistic. Defensive measures focus on cost and supply stability; opportunistic actions target certified, higher-margin applications and strategic consolidation. This briefing and the full PW Consulting report are tools to convert macro signals into board-level choices: budget allocations, R&D roadmaps, and M&A mandates. Importantly, because the market demonstrates moderate concentration, timing matters — early certification and scale investments can change competitive dynamics in under two years.
Next steps
This article presents the strategic contours and evidence-based implications of the plastic bearings market for 2026 planning. For operational teams and executives seeking the granular segmentation, proprietary demand curves, and the vendor-level financial metrics required for transaction or product-launch decisions, our full report contains the detailed datasets and executable templates to move from strategy to implementation.
PW Consulting’s full Plastic Bearings Market report (base year 2025, forecast 2026–2032) consolidates the quantitative models, supplier dossiers, and go-to-market playbooks referenced here. Access it to obtain the segment-level modeling, scenario outputs, and supplier scorecards that are intentionally omitted from this briefing to preserve the competitive utility of the underlying intelligence.
For detailed analysis of this topic, please visit the official page: Plastic Bearings Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com