

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Piperylene Market to Hit USD 1,231M by 2032, Growing at 6.9% CAGR

Piperylene Market 2026: Strategic Briefing for Decision-Makers
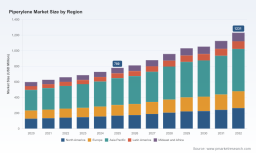
As supply chains normalize and end-markets recalibrate after successive cycles of feedstock volatility, piperylene has re-emerged as a quietly strategic olefin in 2026. PW Consulting’s new Piperylene Market study translates five years of historical dynamics (2020–2025) into an actionable forward view across 2026–2032. The market’s trajectory — from roughly USD 598.5 million in 2020 to USD 780.0 million in 2025, and a disciplined projection to about USD 1,231.0 million by 2032 at a 6.9% CAGR over the forecast period — underscores both growth and structural maturation. This briefing outlines why that growth matters for corporate strategy in 2026, what the report delivers, and how executives should prioritize moves in procurement, capacity, commercial strategy, and innovation without disclosing the proprietary segment-level minutiae reserved for the full study.
Piperylene Market
Why Piperylene Deserves Board-Level Attention in 2026
-
Diversifying feedstock exposure: Piperylene, largely sourced as a C5 fraction from steam cracking and other olefin streams, sits at the intersection of petrochemical economics and specialty polymers. Its pricing and availability are sensitive to crude slate changes, steam-cracker yields, and downstream demand cycles—factors that can materially affect margin profiles for resin and elastomer producers.
Piperylene Market -
Compounding demand drivers: Across adhesives, resins, rubber modifiers, and select coatings, demand for piperylene-based intermediates is growing not only in absolute terms but in application intensity. The market’s projected compound growth (6.9% CAGR, 2026–2032) reflects both volume expansion and gradual value-upgrading through higher-purity streams and specialty grades.
Piperylene Market -
Consolidated supply base: The sector displays a high concentration among top producers (CR3 and CR5 metrics show a concentrated topology). Such concentration favors coordinated capacity decisions, creates opportunities for offtake negotiation, and increases the strategic importance of long-term partnerships and feedstock security.
-
Strategic adjacency to sustainability goals: As downstream customers demand lower-carbon resins and circular-feedstock options, piperylene producers who can offer traceability, lower-carbon footprints, or compatibility with bio-derived streams will capture premium niches during the forecast window.
What PW Consulting’s Report Delivers (Operationally Focused)
Our study is designed as a strategic toolset for commercial and corporate teams. The full report synthesizes quantitative models with qualitative scenario work to produce actionable outputs, including:
- Market sizing and trend decomposition: A verified historical series and forward curve that explain drivers behind the USD 598.5M → USD 780.0M evolution through 2025 and the pathways to the USD 1,231.0M 2032 outcome.
- Pricing and feedstock modeling: Dynamic models linking steam-cracker yields, C5 fraction availability, and piperylene pricing under multiple crude-slate and demand scenarios.
- Supply-chain stress tests: Scenario-based risk matrices quantifying exposure to feedstock shocks, logistics disruptions, and capacity swings among integrated producers.
- Commercial playbooks: Negotiation frameworks for offtake contracts, hedge strategies, and short-/long-term sourcing prioritization tailored to buyer profiles (commodity users, specialty formulators, toll processors).
- M&A and capacity decision frameworks: Valuation sensitivities and decision gates for brownfield debottlenecking, greenfield options, and bolt-on M&A versus long-term tolling partnerships.
- Technology and product roadmap: Assessment of high-purity versus technical-grade positioning, innovation levers for product differentiation, and R&D investment sizing to support premiumization.
- Regulatory and sustainability overlay: Guidance on compliance expectations, carbon accounting for olefin streams, and strategies to align with customer ESG requirements.
Competitive Landscape: Strategic Implications from Core Players
The piperylene ecosystem is dominated by a mix of global integrated producers, regional petrochemical champions, and specialty chemical houses. Key participants include LyondellBasell, ExxonMobil Chemical, Chevron Phillips Chemical, Zeon Corporation, LOTTE Chemical, Eastman, Shell Chemicals, Sinopec, Formosa, and Mitsui Chemicals. Each typifies a distinct strategic posture:
-
LyondellBasell, ExxonMobil, Chevron Phillips, Shell, and Sinopec: These integrated majors leverage steam-cracking scale and downstream integration to manage feedstock volatility and secure internal demand. For corporate strategists, they represent both reliable suppliers and potential acquirers/partners in capacity plays; their investment cycles signal the rhythm of global availability.
-
Zeon, LOTTE, Mitsui, and Formosa: These players are more focused on specialty grade extraction and downstream applications such as resins and synthetic rubbers. They are often the sources of formulation-led product innovation and are important partners for co-development and offtake for higher value segments.
-
Eastman and similar specialty firms: They act as bridges between commodity supply and application-specific product solutions (e.g., resin modifiers, coatings intermediates), making them ideal collaborators for commercialization and market entry strategies focused on premium end-use sectors.
For buyers and investors, the strategic takeaway is clear: alignment with one of the major integrated producers secures volume and competitively priced feedstock, while partnerships with specialty suppliers unlock product differentiation. This dual-path approach should inform procurement and M&A choices in 2026.
Market Dynamics and External Noise: The Regulatory Angle
Two notable regulatory developments in early 2026 — modernization of approval standards and accelerated pathways in major drug-regulatory agencies — while not directly tied to petrochemicals, exemplify an important cross-industry trend: regulators are compressing development timetables and shifting evidentiary expectations. For piperylene market participants, the implications are twofold:
-
Downstream timing sensitivity: Industries that adopt new regulatory efficiencies (e.g., pharma packaging, adhesives used in medical devices) may accelerate procurement cycles for speciality resins and adhesives that incorporate piperylene-derived intermediates. Suppliers with validated quality systems and regulatory-ready documentation will win early contracts.
-
Increased demand for traceability: Accelerated approvals and closer regulatory scrutiny amplify the value of traceable, consistent feedstocks. Producers offering robust chain-of-custody and quality assurance systems will be better positioned to capture cross-sector demand spikes.
Priority Actions for 2026
-
Secure mid-term offtake: Negotiate 24–36 month frameworks with flexible volume bands tied to feedstock indices. Prioritize counterparties that can demonstrate integrated supply resilience or certifiable lower-carbon footprints.
-
Invest selectively in high-purity capability: Given the forecasted premiumization, modest investments in purification or selective separation can unlock higher-margin streams without large-scale capacity expansion.
-
Hedge feedstock exposure: Use blended hedging instruments that reflect steam-cracker economics and seasonal demand cycles. Scenario modeling from the report identifies stress points where hedges materially protect margins.
-
Align R&D with regulatory-ready specs: Ensure product dossiers and quality systems meet accelerated approval expectations in regulated end-markets—this reduces time-to-contract for customers in sectors experiencing faster approvals.
-
Monitor consolidation signals: With the market exhibiting significant concentration among leading producers, watch for divestments, capacity swaps, and strategic alliances as trigger points for opportunistic M&A or partnership moves.
Why PW Consulting’s Study Is Strategically Useful
This report is built to move beyond descriptive market commentary and into prescriptive decision support. By mapping historical performance into a transparent scenario framework and layering in supply-side concentration metrics, pricing models, and demand-depth analytics, the study lets executives play out "what-if" choices with quantified outcomes. In short, it converts a 6.9% CAGR narrative into specific procurement timelines, capex gates, and commercial tactics for 2026.
Next Steps and Access
This briefing intentionally frames the strategic stakes and operational levers without disclosing the granular segment splits and proprietary scenario matrices that underpin our conclusions. For procurement teams, R&D leaders, and corporate development professionals who require the full quantitative models, supplier scorecards, and deal-level negotiation playbooks, the complete Piperylene Market report is available through PW Consulting’s portal. Accessing the full study will provide the detailed regional, type, and application segmentation, plus vendor-level assessments that inform executable 2026 strategies.
For inquiries about tailored briefings, bespoke scenario workshops, or rapid due-diligence packages based on the report, contact PW Consulting’s Chemicals & Materials practice. Our team will convert industry-level insights into a customized decision pack aligned to your risk appetite and commercial timeline.
For detailed analysis of this topic, please visit the official page: Piperylene Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com