

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Rigid Endoscopes Market at USD 1,250M in 2025, 5.5% CAGR

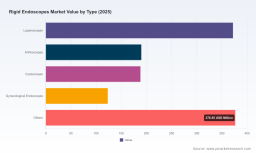
Rigid Endoscopes Market — Strategic Preview for 2026 Decision-Makers
As PW Consulting’s Senior Strategic Advisor and Chief Industry Analyst, this briefing synthesizes the essential takeaways from our full Rigid Endoscopes Market study to inform high-stakes decisions in 2026. Using a base year of 2025 and a historical window covering 2020–2025, our analysis traces how the market evolved into a USD 1,250 million industry in 2025 and projects the market to expand steadily across the 2026–2032 forecast horizon. Under our central scenario the market grows at a compound annual growth rate (CAGR) of 5.5% and approaches roughly USD 1,800 million by 2032. This preview highlights strategic inflection points, regulatory headwinds, competitive vectors, and the practical implications you should act on today. For proprietary subsegment tables, country-level splits, and modeled scenarios, access to the full report is required.
Rigid Endoscopes Market
Why the market trajectory matters for 2026 strategy
The dynamics underpinning the rigid endoscopes market are driven by a clear convergence of clinical, economic, and technological forces. Minimally invasive surgery remains a primary clinical catalyst, supported by demographic tailwinds (aging populations and rising chronic disease burdens) and the ongoing shift of procedures from open surgery to endoscopic approaches. On the economic side, hospital throughput pressures and evolving reimbursement schemes are accelerating demand for equipment that reduces OR time while maintaining quality.
Rigid Endoscopes Market
Technological advancements—higher-resolution optics, 4K/HD imaging, illumination innovations, and modular integration with visualization platforms—are increasing the lifetime value of endoscope systems and creating differentiation opportunities for original equipment manufacturers (OEMs). At the same time, the industry is negotiating a growing cost and compliance burden related to reprocessing reusable devices. Recent standards and guidance have heightened sterilization requirements and materially increased per-procedure reprocessing cost assumptions, shifting total cost of ownership calculations for hospitals and influencing procurement strategies.
Rigid Endoscopes Market
Regulatory and reprocessing dynamics: a practical constraint
- Standards impact economics: The application of contemporary processing standards to rigid endoscopes has raised reprocessing complexity and, in many cases, the per-procedure cost base for hospitals—industry references place that increment in the low hundreds of USD per procedure. These increases materially affect the comparative economics of reusable versus disposable instruments and shift negotiating leverage toward suppliers who can offer validated low-cost reprocessing pathways or single-use alternatives.
- FDA recommendations: Regulatory guidance increasingly favors more robust sterilization methods (e.g., ethylene oxide or low-temperature gas plasma) for reusable endoscopes. This alters capital planning: hospitals must either invest in upgraded reprocessing infrastructure (with associated recurring costs and compliance overhead) or contract externally for specialized sterilization services.
Strategic implications for core stakeholders in 2026
- OEMs and platform providers: Prioritize modularity and systems integration. With imaging and visualization becoming the primary differentiators, vendors that offer upgradeable optics, backward-compatible scopes, and full-suite visualization platforms will capture premium share and generate recurring software and service revenues.
- Hospital procurement and IDNs: Reconfigure purchase decisions around total cost of ownership, not unit price. Incorporate reprocessing cost models and downtime risk into sourcing, and consider multi-year service agreements that lock in validated sterilization processes and spare-part logistics.
- Investors and private equity: Seek targets with defensible service incomes—service contracts, consumables, and reprocessing solutions. Market concentration metrics (a three-firm CR3 near two-thirds and a broader CR5 approaching three-quarters) signal a market with high incumbent power, but attractive niches exist for disruptive entrants focused on single-use optics, reprocessing outsourcing, or AI-enabled visualization.
- Service providers and sterilization specialists: The demand for outsourced reprocessing and sterilization is poised to grow. Firms that can offer validated, cost-efficient sterile-processing models or mobile sterilization units will gain traction with smaller hospitals and ambulatory surgical centers that cannot justify heavy capital investment.
Competitive landscape — who matters and how they are positioned
The market is moderately concentrated: leading global players hold a majority share, which shapes pricing, standards adoption, and distribution dynamics. The market leaders blend broad device portfolios with deep clinical relationships and global service footprints. Key players include:
- KARL STORZ SE & Co. KG (Tuttlingen, Germany) — Known for its HOPKINS® optics and a long heritage in diagnostic/operative telescopes across ENT, gynecology, and general surgery.
- Stryker Corporation (Kalamazoo, Michigan, United States) — Offers rigid endoscopes within a broader Endoscopy and Surgical Visualization portfolio, leveraging integration with laparoscopic and urologic systems.
- Olympus Corporation (Tokyo, Japan) — A major supplier of rigid laparoscopes and high-quality visualization products, with emphasis on imaging systems and clinical workflows.
- Smith & Nephew plc (London, United Kingdom) — Focused on arthroscopy and sports medicine optics, with an emphasis on high-definition scopes tailored to orthopedics.
- B. Braun Melsungen AG (Melsungen, Germany) — Markets Aesculap-branded rigid endoscopes with a focus on laparoscopy and minimally invasive surgical instruments.
Competitive advantage flows from three axes: (1) imaging and systems integration, (2) after-sales services and consumables, and (3) compliance and validated reprocessing pathways. Expect consolidation around these axes—larger players will continue to fortify service networks and validation programs, while nimble specialists will target vertical niches.
Where value creation will concentrate through 2026
- Service economics: Consumables, optics upgrades, and maintenance contracts will comprise the fastest-growing recurring-revenue pockets. Players that reframe sales conversations around lifecycle economics will outcompete those focused on one-time device sales.
- Validated reprocessing solutions: Providers that supply validated, cost-efficient reprocessing protocols and equipment—especially those that reduce the need for capital-intensive hospital upgrades—will capture outsized share of new deployments.
- Single-use vs. reusable hybrid models: Hybrid strategies that combine reusable core systems with single-use adjuncts (e.g., disposables for contamination-prone components) address infection-control concerns without abandoning the economic benefits of reusables.
- Software-enabled differentiation: Advanced imaging, AI-assisted visualization, and procedure analytics will become decision multipliers, justifying price premiums and enabling tied services like remote diagnostics and predictive maintenance.
What the PW Consulting report delivers — pragmatic, actionable outputs
Our full market study goes beyond descriptive analysis to provide practical tools you can deploy in 2026 planning cycles. Highlights include:
- Validated market sizing and growth scenarios (base year 2025; historical 2020–2025; forecast 2026–2032) with a central CAGR of 5.5% under our baseline scenario.
- Segment- and channel-agnostic frameworks for assessing product prioritization and investment trade-offs without exposing sensitive client-facing subsegment figures in this preview.
- Decision-ready modules: TCO calculators (including updated reprocessing cost inputs), procurement RFP templates, and service-contract benchmarking standards.
- Regulatory impact assessment with compliance roadmaps—detailing how recent processing standards and FDA recommendations affect capital planning, OPEX, and clinical workflow redesign.
- Competitive playbooks and M&A screening—profiles of strategic targets, partnership templates, and integration risk checklists tuned to the market’s current concentration profile.
- Technology radar and adoption timelines for imaging, single-use optics, sterilization tech, and AI-enabled visualization tools.
Practical next steps for executives in 2026
- Run a two-week portfolio triage using our scoring matrix: classify SKUs by clinical value, upgradeability, margin profile, and reprocessing burden. Divest or reprice poor-fit assets and fast-track upgradeable platforms.
- Implement a reprocessing cost audit in high-volume sites: map current sterilization practices against updated standards and estimate incremental per-procedure costs to inform procurement negotiations.
- Design pilot agreements with sterilization specialists or outsourced reprocessing vendors to compare internal versus external economics over a 24-month horizon.
- Accelerate partnerships that bring imaging and analytics into the OR ecosystem—hospital systems value integrated workflows over isolated product features.
- Prepare M&A shortlists focused on asset-light recurring revenue (software, consumables, validation services) rather than capital-intensive manufacturing alone.
Concluding perspective — how to use this preview
This strategic preview is intended to orient your leadership team on the critical choices that will define success in 2026 and beyond: managing the reprocessing cost transition, prioritizing system-level differentiation, and capturing recurring revenue streams while navigating a moderately concentrated supplier landscape. The PW Consulting full report contains the granular tables, country- and application-level models, and scenario outputs needed to operationalize these recommendations. Use this briefing to align stakeholders, define hypothesis-driven pilots, and prioritize scope for deeper analysis.
To obtain the full report and unlock proprietary segmentation, country breakdowns, and downloadable decision tools referenced here, please visit the PW Consulting research portal or contact our market intelligence desk. The next 18 months present a rare window to reshape product portfolios and capture durable margins—this study is designed to make that window actionable for 2026 planning cycles.
For detailed analysis of this topic, please visit the official page: Rigid Endoscopes Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com