

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Blood Irradiation Market Poised for Growth at 5.49% CAGR Through 2032

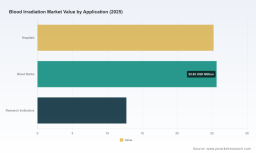
Blood Irradiation Market 2026: Strategic Preview for Executive Decision-Making
Between 2020 and 2025 the global blood irradiation market expanded steadily—from a modest base to a materially larger, more diversified opportunity. Our baseline 2025 estimate places the market at approximately USD 63.61 Million, and under our central scenario the market is forecast to reach roughly USD 93.35 Million by 2032, representing a compound annual growth rate (CAGR) of about 5.49% over the forecast period (2026–2032). That trajectory reflects a mix of steady clinical demand, incremental technology adoption, and an evolving regulatory and standards environment that is reshaping product lifecycles, procurement practices, and service models.
Blood Irradiation Market
Why this briefing matters for 2026 corporate strategy
- Timing is asymmetric: The path from regulatory proposal to market impact is measurable but decisive. With major regulatory proposals and standards updates issued in early 2026, organizations that craft compliance-forward roadmaps now will enjoy first-mover advantages in procurement cycles and clinical partnerships over competitors that adopt a wait-and-see stance.
- Incremental growth, compounding opportunity: A mid-single-digit CAGR does not imply low upside. For incumbents and new entrants alike, predictable demand combined with service, upgrade and consumable revenue streams creates attractive margin expansion opportunities—especially when paired with targeted product differentiation.
- Fragmentation creates optionality: Market concentration metrics show a dispersed supplier base. Low CR3/CR5 ratios indicate that no single player dominates the market; this fragmentation makes consolidation, strategic alliances and channel-led expansion attractive near-term plays.
- Standards and procurement are converging: Industry standards updates and regulatory clarifications are tightening the functional and documentation requirements for blood irradiators. This convergence will accelerate buyers’ preference for validated, trackable technologies and for vendors that can integrate equipment, software and service into compliant workflows.
What PW Consulting’s full report delivers (practical, execution-ready content)
Our research is built for executives who need rapid, defensible answers—not generic market color. The full study includes:
Blood Irradiation Market
- Top-line time series market sizing (historical 2020–2025 and forecast 2026–2032) and scenario variants that stress-test demand under different regulatory and reimbursement pathways.
- Commercially actionable segmentation frameworks (technology, clinical application, end-user and region) that identify pockets of early adoption and margin upside—presented so you can prioritize sales and R&D investments.
- Competitive benchmarking and capability heatmaps for the industry’s leading device suppliers, covering product portfolios, service models, regulatory posture, installed-base dynamics and strategic intent.
- A regulatory and standards tracker that synthesizes recent and pending rulemaking, with explicit implications for product classification, submission strategies and time-to-market under multiple jurisdictions.
- Go-to-market playbooks, including channel mapping, tender-readiness checklists, clinical evidence roadmaps, and pilot design templates applicable to blood banks, hospitals and research institutions.
- Financial tools: downloadable financial models, NPV/IRR scenarios, pricing sensitivity matrices and ROI calculators for capital procurement, retrofit versus replace decisions, and service contract structuring.
- Deal and M&A screening: target archetypes, integration risk checklists and valuation heuristics calibrated for the sector’s typical margins and growth multiples.
The report intentionally presents deep, source-level analysis while withholding proprietary granular splits in the free summary—this “trailer” approach demonstrates our methodology and insights while directing decision-makers to the full dataset for transaction-level planning.
Blood Irradiation Market
Competitive landscape — strategic reading of the vendor field
The supplier universe comprises global OEMs, regional specialists and diversified industrial groups. Key players include established manufacturers of gamma-ray systems, X‑ray device suppliers, and a mix of regional producers offering lower-cost alternatives. Several strategic patterns stand out:
- Technology incumbents versus modular challengers: Historically, gamma-ray systems commanded clinical trust due to proven sterilization profiles, while X‑ray and emerging modalities have competed on operational flexibility and regulatory fit. Some vendors differentiate by integrating radiation sources with advanced dose-monitoring and digital traceability—features increasingly demanded by hospital procurement teams.
- Service-first strategies win installed-base loyalty: Vendors that combine preventive maintenance, consumables and rapid-response service have higher retention and recurring revenue potential. For capital-constrained buyers, bundled financing and outcome-linked contracts can accelerate adoption.
- Regional manufacturing and regulatory alignment: Several manufacturers leverage localized production and regulatory know-how to reduce approval time and servicing cost in target markets. This provides them with price and speed advantages—vital in tender-driven health systems.
- Partnerships and ecosystem plays: The most adaptive companies are forging links with blood centers, standards bodies and electronic health record vendors to embed irradiation workflows—an effective moat against commoditized price competition.
Notable firms warranting specific executive attention include manufacturers focused on gamma systems and X‑ray platforms, international medical equipment suppliers with diversified portfolios, and several Asia-based producers that are scaling exports. While we profile each of these companies in the full report—covering product roadmaps, clinical evidence, regulatory filings and recent commercial moves—the public summary purposefully omits vendor share data to preserve competitive sensitivity.
Regulatory & standards inflection points — implications for 2026 strategy
Key developments in early 2026 materially affect risk and investment timelines. Regulators and standards bodies have sharpened requirements for device classification, performance controls and premarket submissions. Two developments are particularly consequential:
- Device reclassification and special controls: Recent rulemaking proposes reclassifying certain blood irradiators under a higher regulatory scrutiny pathway—creating clearer expectations for labeling, performance testing and post-market surveillance. For companies selling into regulated markets, this raises the bar for design controls and documentation but also creates a moat for compliant suppliers.
- Targeted premarket requirements for specific clinical uses: Regulators have signaled distinct submission timelines and evidentiary thresholds for irradiators used in intraoperative salvage or other specialized applications. This bifurcation means firms must choose between broad-market offerings that meet general controls and focused investments in indications that require higher-level approvals.
Standards organizations have likewise updated clinical practice guidance, making irradiation procedures and device validation central to blood bank accreditation. These standards propagate into procurement specifications, accelerating demand for devices that can demonstrate standards compliance.
Recommended executive actions for 2026
Based on our analysis, leadership teams should prioritize a short list of high-impact moves this year:
- Activate a regulatory-first product roadmap: Map each product and indication to the evolving classification and submission timelines, and begin formalizing 510(k)/PMA strategies or equivalent dossiers. Early engagement with regulators shortens approval timelines and reduces downstream rework.
- Defend and monetize installed base: Rapidly implement service and upgrade programs that convert legacy devices into standards-compliant assets. Bundled service contracts and data-driven maintenance increase recurring revenue and raise switching costs.
- Prioritize clinical evidence and pilot partnerships: Design pragmatic clinical or operational pilots with strategic customers—blood centers and high-volume hospitals—that generate the real-world evidence required by purchasers and regulators.
- Optimize go-to-market channels: Rebalance direct sales and distributor partnerships by market segment; strengthen tender-readiness and capitalize on regions where local manufacturing or regulatory familiarity accelerates procurement.
- Prepare an M&A playbook for consolidation opportunities: Use the sector’s fragmentation to identify bolt-on targets—service providers, regional OEMs and digital monitoring specialists—that can be integrated quickly to expand margins and footprint.
- Invest in digital enablement: Telemetry, dose logging and audit-ready reporting are becoming procurement hygiene—embed these capabilities to differentiate on total cost of ownership and compliance.
How PW Consulting’s deliverables shorten implementation timelines
We designed this research to be more than insight—it is a toolkit for execution. Clients receive:
- Scenario-driven forecasts and downloadable models to stress-test capex and revenue plans.
- Regulatory timelines mapped to product roadmaps with filing templates and clinical evidence blueprints.
- Vendor scorecards and negotiation playbooks tailored to common procurement processes in blood banks and hospital systems.
- An opportunity prioritization matrix that ranks markets, channels and product initiatives by ease-of-entry, margin upside and regulatory complexity.
These outputs accelerate board-level decision-making and reduce the time between strategy and commercial impact.
Next steps
We have framed the strategic landscape for 2026: steady market growth underpinned by regulatory tightening and service-driven economics, and a competitive field ripe for differentiation and consolidation. For transaction-level diligence, product development planning, or immediate regulatory positioning, the full PW Consulting report provides the empirical dataset, vendor dossiers, and executable playbooks you will need.
Access the complete study to retrieve the market model, vendor profiles, regulatory tracker and operational templates that will inform your 2026 investment and go-to-market choices.
For detailed analysis of this topic, please visit the official page: Blood Irradiation Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com