

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Contact Center Market to Reach USD 98.84B by 2032 at 11.05% CAGR

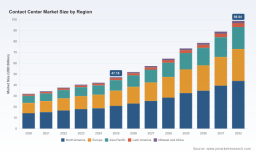
Contact Center Market — Strategic Preview for 2026 Decision-Makers
Executive snapshot
As organizations enter budgeting and transformation cycles for 2026, the contact center landscape is no longer a point solution — it is a strategic spine connecting sales, support, and digital experience. PW Consulting’s latest market study (base year 2025, forecast 2026–2032) shows a sustained expansion of the addressable market, reflecting accelerated adoption of cloud-native platforms, embedded AI, and omnichannel orchestration. The global market recorded clear year-on-year growth through 2020–2025 and is forecast to expand at an 11.05% CAGR into the 2030s, approaching a near-doubling from 2025 to 2032. For senior leaders, that trajectory converts into three imperatives for 2026: prioritize vendor and architecture choices that are future-proof, quantify the impact of automation on cost and experience, and build contracting strategies that survive supplier-driven price shocks.
Contact Center Market
Why this research matters for 2026 planning
- Timing of investment: 2026 is the inflection year where technology upgrades, licensing changes, and operational redesigns converge. Capital and operating budgets set this year will determine the degree to which organizations capture automation value and customer experience differentiation.
- Vendor economics and concentration: The market exhibits moderate concentration (CR3 ≈ 33.6%, CR5 ≈ 37.1%), meaning a handful of providers influence price and feature roadmaps, but the market still offers ample choice for specialized and mid-market buyers. That balance creates bargaining power — if you have the right procurement playbook.
- Operational levers: Advances in conversational AI and orchestration change the unit economics of contact work. Our report quantifies practical break-even points for automation versus human handling and models the sensitivity of TCO to volume, complexity, and license escalation.
Market trajectory and what the numbers signal
Macro growth is not abstract: the market’s climb through 2020–2025 established a baseline of platform modernization and proved cloud economics across industries. The forecast through 2032 — driven by omnichannel conversion, AI augmentation, and growing enterprise recognition of contact centers as revenue engines — implies material opportunity for vendors and buyers alike. For procurement and transformation leaders, the sequence is clear: accelerate pilot-to-scale programs for Tier 1 automation, lock favorable commercial terms for mission-critical modules, and embed recurring SaaS cost scenarios into three-year budgets.
Contact Center Market
Forces shaping decisions in 2026
- AI as an operational multiplier: Conversational agents and agent-assist technologies are converting margin for contact organizations. Sector analysis shows AI-driven automation has the theoretical potential to reduce contact center agent labor costs by up to $80 billion globally. A single Tier 1 interaction handled by AI can reduce per-interaction cost dramatically versus live handling — a dynamic that changes workforce planning, routing design, and workforce management assumptions.
- Per-interaction economics: The disparity between live-agent and automated handling is stark; while a live inbound call can cost in the mid-single-digit to low-double-digit dollars, AI-handled Tier 1 interactions can be managed for cents. These differentials are central to our ROI models and migration sequencing guidance.
- Supplier pricing and licensing risk: The industry is experiencing upward pressure on software pricing. Enterprise vendors have implemented across-portfolio price increases effective July 2026; key platform dependencies (including frontline and business tiers in major productivity suites) are scheduled for meaningful increases during the same period. This creates a two-way dynamic: buyers must accelerate negotiations to lock existing rates while modeling worst‑case license inflation into TCO scenarios.
- Capital flows into specialization: Funding trends signal where innovation will accelerate. Recent investments into AI support automation and business-messaging-first platforms show investor confidence in niche, high-leverage propositions — an important factor when evaluating partner roadmaps and acquisition risk.
Competitive landscape — positioning and strategic guidance
The contact center competitive set has evolved from PBX-centric incumbency to a field of cloud-first, AI-enabled platform plays, vertical specialists, and unified-communications incumbents. Our competitive analysis evaluates vendor direction across five vectors: product architecture (cloud-native vs. hybrid), AI maturity (assistant + analytics), orchestration and journey capabilities, verticalization, and commercial flexibility.
Contact Center Market
- Five9: A cloud-native Intelligent CX platform with strong AI agent-assist and predictive routing. Best suited for enterprises prioritizing rapid cloud migration and advanced agent augmentation. Watch for integration readiness with adjacent CRM and workforce suites.
- Genesys: A mature omnichannel platform focused on journey orchestration, embedded chatbots, and workforce engagement. A solid choice where end-to-end experience consistency and large-scale workforce optimization are primary objectives.
- NICE: Known for CXone and deep workforce optimization/quality management capabilities. Strong where compliance, QA and automated quality scoring are central to operations.
- Talkdesk: Positions itself with industry-specific experience clouds and rapid vertical deployments. Attractive for regulated or highly specialized verticals that need packaged, faster time-to-value solutions.
- Dialpad: An AI-first contact center with real-time transcription and flexible agent workflows. Appeals to organizations prioritizing real-time analytics and distributed agent models.
- Verint: Focused on workforce and quality management with robust analytics — a pragmatic choice for operations-centric transformations.
- Nextiva: Markets unified communications plus contact center with predictable pricing and simpler procurement — useful for mid-market buyers seeking an all-in-one approach.
- RingCentral: Combines UCaaS and contact center capabilities with omnichannel features and growing AI support — an option when consolidating collaboration and contact workloads.
- Vonage: Offers customizable contact center solutions with omnichannel integrations and AI agents — well-suited for enterprises needing bespoke integration flexibility.
- Zoom: Extends its collaboration strengths into an AI-first contact center offering, promising seamless voice-collaboration convergence for organizations that tie meetings and contact workflows closely together.
Our vendor scorecards in the full report compare these providers across deployment risk, integration cost, AI maturity, and three-year roadmap alignment. Given current market concentration metrics, buyers can achieve leverage, but must be prepared with a technical and commercial evaluation framework to capture it.
Report contents — practical modules that inform 2026 action
PW Consulting’s full study is designed as an operational playbook, not just a market overview. It includes:
- Scenario-based market forecasts (2026–2032) and sensitivity analyses that quantify upside from accelerated AI adoption and downside from license inflation.
- A vendor selection toolkit: scored evaluation templates, integration risk heatmaps, and reference architecture patterns for cloud-native and hybrid implementations.
- TCO and ROI models with per-interaction cost baselines, workforce transition cost curves, and break-even calculators for automation rollouts.
- Contract and procurement playbook: negotiation levers, renewal timing guidance, and clauses to mitigate mid-contract price escalations.
- Implementation roadmaps: phased migration sequences to convert pilots into enterprise-scale automation while preserving CX quality and compliance.
- Benchmarked KPIs and staffing models to translate automation lift into staffing reductions and re-skilling needs.
- Appendices with primary interviews, vendor roadmap scoring, and an evidence-backed list of red flags for vendor sustainability and acquisition risk.
How to apply the research in 2026 — immediate actions for leaders
- Short-term (0–6 months): Re-run license commitments and renewals against the July 2026 pricing changes; prioritize contract amendments that cap escalators or shift to consumption-based models where practical.
- Medium-term (6–18 months): Pilot AI-handled Tier 1 flows with clear measurement windows (cost per interaction, containment rate, CSAT impact). Use our ROI templates to validate scaling decisions before full workforce reallocation.
- Long-term (18–36 months): Transition to an orchestration-first architecture that decouples channel handling, analytics, and workforce management — this reduces vendor lock and improves resilience against supplier price adjustments.
- Procurement play: Build a multi-vendor procurement strategy that pairs a core platform with best-of-breed AI and vertical accelerators; use our vendor scorecards to define preferred supplier bundles and negotiation timelines.
- Workforce strategy: Invest in rapid re-skilling (agent as experience manager) and create clear pathways from repetitive task handling to higher-value roles; our workforce models project timing and cost for these transitions.
Signals to watch and final counsel
Two funding events in the ecosystem — significant investments into AI-support automation and business messaging platforms — indicate where innovation and competition will heat up. Combined with the wide gap in per-interaction economics between live handling and automated handling, these signals point to an acceleration of automation pilots turning into enterprise rollouts during 2026–2027.
Practical counsel for 2026: treat vendor price changes and license inflation as risk factors to be actively modeled and mitigated, not as footnotes. Lock favorable commercial terms where possible, accelerate measurable AI pilots, and use an orchestration-first architecture to preserve optionality. The choices you make this budget cycle will crystallize who captures the productivity gains of automation and who remains exposed to rising licensing and labor costs.
Next step
This article is a preview of PW Consulting’s full Contact Center Market study. The full report contains the granular regional, type and application splits, vendor-level market shares, and downloadable tools referenced above. If you are preparing strategic budgets, vendor negotiations, or transformation roadmaps for 2026, access the full study to obtain the detailed models, vendor scorecards, and actionable playbooks that will support defensible decision-making in the year ahead.
For detailed analysis of this topic, please visit the official page: Contact Center Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com