

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: In-Building Wireless Market Poised for 11.8% CAGR through 2032

In‑Building Wireless Market: Strategic Insights for 2026 Decision‑Makers
As PW Consulting’s Senior Strategy Advisor and Lead Industry Analyst, I present this executive introduction to our new In‑Building Wireless Market study. The report—anchored on 2025 as its base year with a historical review from 2020–2025 and a forecast through 2026–2032—translates technical evolution, regulatory change, and commercial dynamics into decision‑ready guidance for enterprise and network leaders in 2026.
In-Building Wireless Market
Market trajectory at a glance
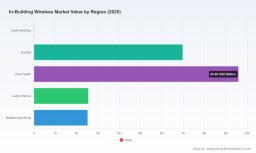
Our topline macro view shows a market that has expanded steadily over the last half decade and is positioned for sustained growth throughout the next business cycle. Measured in USD Million, the market moved from a single‑digit million baseline in 2020 to approximately USD 22.6 Million in 2025 (base year). Underlying demand drivers and technology transitions yield a compound annual growth rate (CAGR) of 11.8% for the forecast horizon, bringing the market to roughly USD 49.3 Million by 2032. Those dynamics create both immediate procurement imperatives and multi‑year portfolio opportunities for system integrators, equipment vendors, venue operators, and enterprise IT organizations.
In-Building Wireless Market
Why this research matters for 2026 decisions
- Capital allocation and timing: The combination of rising demand and a double‑digit CAGR forces a choice between early deployment to capture service differentiation and staged rollout to manage capex. Our analysis helps you align CAPEX/ OPEX profiles with expected service monetization horizons.
- Vendor and technology selection: The market is at an inflection between legacy DAS approaches and a proliferating set of alternatives—small cells, distributed radio solutions, and cloud‑managed private 5G radios. Selection criteria now require deeper evaluation of interoperability, neutral‑host capability, spectrum access strategies (including shared bands), and long‑term software licensing costs.
- Regulatory risk and spectrum strategy: New regulatory moves in 2026 materially affect indoor operations—particularly the FCC’s action enabling more flexible operation of low‑power indoor unlicensed devices in the 6 GHz band and ongoing proposals around spectrum sharing for space and satellite broadband. These shifts change the calculus for private networks and automated frequency coordination systems.
- Procurement and ROI discipline: With multi‑vendor ecosystems and growing market concentration among top suppliers (noted CR3 and CR5 concentrations), procurement teams need robust, vendor‑agnostic ROI models and tender specifications that prevent lock‑in while protecting interoperability.
What’s inside the report (practical, actionable components)
- Market sizing and forecast model (2020–2032) with scenario analysis and sensitivity testing for adoption, pricing, and spectrum access assumptions.
- Decision frameworks for enterprises and venues: build vs buy, neutral host vs operator‑led, and staged deployment roadmaps with KPIs tied to revenue uplift, safety/mission outcomes, and tenant satisfaction.
- Vendor assessment matrix: capability, interoperability, cloud management, CBRS/6 GHz support, and compliance markers—designed for procurement and technical evaluation committees.
- Deployment playbooks: technical checklists for integration with existing fiber, PIM mitigation, power optimization, and RF commissioning best practices to reduce rework and cost overruns.
- Commercial templates: RFP language, SLA clauses, and financing models that balance vendor incentives with buyer protection.
- Regulatory and risk dashboard: current policy actions, pending rule‑makings, and decision triggers that should prompt contract renegotiation or capex deferral.
- Case studies and proof‑of‑concept blueprints: rapid validation approaches for stadiums, campuses, healthcare facilities, and industrial sites.
Note: This preview highlights structure and strategic themes. Detailed segment breakouts, granular regional and application splits, and project‑level financials are reserved for the full report to preserve competitive value and guide you to our source page for complete intelligence.
In-Building Wireless Market
Competitive landscape — focal companies and implications
Three vendors exemplify divergent strategic pathways shaping the market:
- Moso Networks (United States): Positioning itself on private 5G and neutral‑host architectures with plug‑and‑play radios and cloud connectivity, the vendor simplifies indoor and mixed indoor/outdoor deployments. Their recent product launch in early 2026 underscores a go‑to‑market that emphasizes rapid time‑to‑value and reduced integration complexity—an attractive proposition for enterprises prioritizing speed over deep custom integration.
- ANDREW / Amphenol (United States): A legacy systems player doubling down on digital DAS and multi‑operator solutions, ANDREW’s engineering pedigree is a strong fit for mission‑critical environments and large venues. Recognition at industry awards and compliance with Build America Buy America standards in early 2026 signals broad suitability for government and federally funded projects where procurement constraints matter.
- SOLiD (South Korea): Focused on modular, scalable DAS and in‑building solutions, SOLiD is playing to venues and enterprises where challenging RF environments demand flexible architectures and proven field resilience.
Recent industry commentary from other notable suppliers highlights emphasis on ROI measurement and unified network strategies for education and enterprise. Collectively, these vendors illustrate the market’s bifurcation: speed and cloud‑centric private cellular versus engineered DAS platforms optimized for scale and multi‑operator connectivity.
Strategic takeaways for vendor selection and partnerships
- Match architecture to outcome: prioritize cloud‑managed private radios for rapid rollouts and pilot projects; retain DAS or distributed radio systems where multi‑operator support or mission continuity is non‑negotiable.
- Insist on interoperability and open interfaces: vendors tout plug‑and‑play—but integration complexity is the leading source of schedule slippage and cost creep. Contractualize interface requirements and test plans up front.
- Factor procurement constraints: for government or federally funded work, supplier compliance (e.g., Build America Buy America) can be a decisive selection criterion.
- Design neutral‑host economics early: neutral host models can unlock revenue for venue owners but require careful subscriber, capacity and cost allocation modeling to be viable long term.
Key market dynamics to monitor in 2026
- Spectrum policy and operational rules: FCC developments around indoor 6 GHz use and spectrum sharing for space services will shape which technologies are feasible and how automated frequency coordination must be implemented.
- Technology convergence: Private 5G, CBRS ecosystems, and advanced small cells are converging with traditional DAS. Decide whether to adopt hybrid architectures or standardize on a single platform for operational simplicity.
- Infrastructure integration costs: Reliable in‑building coverage still depends on disciplined integration with existing fiber, signal sources, and careful PIM management. These costs are front‑loaded and should factor into total cost of ownership models.
- Market concentration: With the top three firms holding a material share of the market and the top five possessing an even larger combined share, competitive dynamics favor scale vendors for large deployments but leave room for niche specialists in verticals and complex sites.
How to use this research in your 2026 planning cycle
- Q1 2026: Use the report’s ROI frameworks to prioritize three pilot sites representing distinct risk profiles (e.g., high‑density stadium, mission‑critical hospital, and a multi‑tenant commercial campus).
- Q2 2026: Run vendor interoperability tests and issue RFPs tied to measurable SLAs and frequency‑coordination commitments; include regulatory contingency clauses related to FCC rule changes.
- Q3–Q4 2026: Execute staged rollouts based on pilot learnings; transition from pilot financing to production budgets with clear conversion criteria (KPIs such as throughput, call success, tenant NPS, and incremental revenue capture for neutral host models).
- Ongoing: Maintain a rolling six‑quarter capability roadmap to reassess vendor roadmaps, spectrum access changes, and evolving market concentration risks; update procurement documents as needed.
Conclusion and next steps
The in‑building wireless market in 2026 presents a rare combination of rapid end‑user demand, evolving regulatory terrain, and vendor differentiation that rewards disciplined strategy. Our report converts that complexity into pragmatic choices—from procurement language and deployment checklists to long‑range financial models and vendor selection heuristics. For the full segment breakouts, granular vendor scoring, and project‑level financials that support immediate procurement actions, please consult the complete PW Consulting report. This introduction is intentionally selective; the detailed intelligence you need to operationalize these insights is available in the full study.
For detailed analysis of this topic, please visit the official page: In-Building Wireless Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com