

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Heavy-Duty Laundry Machinery Market to Reach USD 2,756.8M by 2032 (6.98% CAGR)

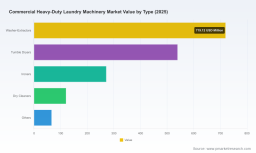
Commercial Heavy‑Duty Laundry Machinery: Strategic Intelligence for 2026 Decision‑Making
As PW Consulting’s Senior Strategy Advisor and Head Industry Analyst, I present a concise, practice‑oriented introduction to our newest market research on the Commercial Heavy‑Duty Laundry Machinery sector. This briefing synthesizes the macro dynamics, competitive currents, regulatory inflections, and operational implications that will matter to executives, investors, and procurement leaders shaping plans in 2026. The goal is to demonstrate the analytical depth and decision‑ready outputs in our full study while intentionally withholding the segmented datapoints that form the proprietary core of the report—access to which is available via the source page.
Commercial Heavy-Duty Laundry Machinery Market
Market at a Glance: What the Numbers Tell Us
The global market for commercial heavy‑duty laundry machinery has emerged from a period of steady recovery and structural renewal. By the 2025 base year, the market reached approximately USD 1,715 Million, and our scenario models show this expanding materially through the forecast window to reach roughly USD 2,757 Million by 2032 at a compounded annual growth rate of 6.98%. The trajectory reflects a combination of replacement cycles, a wave of retrofits focused on energy and water efficiency, and expanding demand across institutional end users driven by hygiene and operational productivity imperatives.
Commercial Heavy-Duty Laundry Machinery Market
Two implications flow directly from these macro indicators: first, capital allocation windows in 2026 should prioritize flexible platforms that capture both retrofit and new‑install opportunities; second, buyers and OEMs must align pricing, service and digital offerings to defend margin as demand scales and competition consolidates. Market concentration metrics suggest a moderately consolidated supplier base, with the top three and five players controlling a meaningful share of the market—enough to influence pricing, distribution, and aftermarket standards, but also leaving room for regional and niche challengers to scale via focused differentiation.
Commercial Heavy-Duty Laundry Machinery Market
Why This Research Matters for 2026 Decisions
- Risk‑adjusted investment planning: Our report converts top‑line growth expectations into pragmatic capital planning scenarios for OEMs and operators, illustrating payback pathways under varying energy cost and regulatory assumptions.
- Procurement and sourcing optimization: Detailed supplier and component risk matrices show where single‑source exposures and raw‑material sensitivities (notably stainless steel supply and pricing) could affect lead times and margins.
- Go‑to‑market and service design: From distributor incentives to outcome‑based service models, the study identifies which commercial strategies preserve unit economics and increase shareability of recurring revenue.
- Regulatory stress‑testing: We map the commercial impact of plausible regulatory moves—such as changes in water and energy standards and sanitization mandates—so teams can prioritize compliance investments without overcapitalizing on unlikely scenarios.
Demand Side Dynamics: Drivers and Strategic Responses
Demand is being reshaped by four converging forces. First, heightened hygiene expectations in healthcare and hospitality create a persistent need for validated sanitization routines; adoption of standards like NSF Protocol P172 is shifting procurement toward certified washers and documented process controls. Second, operating cost pressure—principally energy and water—continues to push buyers to prioritize machines with superior lifecycle economics rather than the lowest upfront price. Third, labor constraints and the push for throughput drive interest in automation, conveyors, and integrated material‑handling systems that reduce manual touchpoints and improve cycle times. Fourth, capital budgets are increasingly assessed through the lens of total cost of ownership (TCO), compelling both vendors and operators to present verifiable TCO models at the point of sale.
For manufacturers and distributors, the strategic response in 2026 should be to bundle hardware with differentiated service offerings (predictive maintenance, spare parts programs, financing) and to demonstrate measurable TCO benefits through third‑party validated case studies.
Product & Technology Momentum
- Energy‑optimization remains the dominant product innovation theme: advanced heat‑recovery, higher‑G‑force extractors, and low‑consumption dryer technologies are moving from premium options to commercial expectations.
- Digitalization: IoT and OEM‑agnostic telematics are shifting service models from reactive field work to predictive scheduling, reducing downtime and parts inventory costs.
- Modularity and retrofittability: Given the size of installed bases, modular designs that enable staged upgrades (controls, sensors, variable speed drives) unlock higher wallet share without forcing full plant replacement.
- Materials and durability: Stainless steel remains the dominant choice for high‑volume operations; its availability and cost trajectory should be factored into product roadmaps and sourcing strategies.
Regulatory & Standards Context
Policy and standards continue to influence procurement and lifecycle economics. Notably, changes in the U.S. regulatory environment around water conservation standards have created near‑term uncertainty for product specifiers and manufacturers. Meanwhile, sanitization standards—such as NSF Protocol P172—raise the bar for validated performance in healthcare and certain institutional settings. For 2026 planning, firms must maintain an active regulatory watch, incorporate compliance buffers into product development timelines, and use certification as a commercial differentiator in tender processes.
Competitive Landscape: Who’s Moving and Why It Matters
The competitive field blends long‑standing industrial OEMs with regional specialists and distributor networks. Key players we profile include:
- Alliance Laundry Holdings Inc. (Speed Queen): A dominant brand in commercial and on‑premise segments. Recent strategic moves—acquisition of distribution assets and an IPO registration filing—signal an emphasis on channel control and capitalizing on aftermarket and service revenue streams. Leadership changes further suggest a near‑term focus on international rollout and investor communications.
- Dexter Laundry, Inc. : Strong in vended and on‑premise systems with a reputation for rugged, serviceable machines. Dexter’s distribution relationships and focus on reliable platforms make it a steady performer in price‑sensitive institutional markets.
- Pellerin Milnor Corporation : Specializes in high‑capacity washer‑extractors and tunnel systems for industrial laundries. Milnor’s deep engineering capability positions it well for large centralized laundries and specialized industrial accounts where throughput and custom solutions drive wins.
- Girbau SA : Known for energy‑efficient industrial and commercial solutions and for pushing integration of efficiency into product positioning—particularly in regions where energy and water regulations are stringent.
- Electrolux Professional Group : Leverages strong brand equity and global service networks to win hospitality and institutional accounts, particularly where integrated laundry room solutions and international compliance are required.
Industry events like The Clean Show 2025 reinforced these competitive themes, showcasing automation, telematics, and new hardware that accelerates throughput. At the channel level, distributor recognition programs and selective acquisitions highlight how vertical control of distribution and aftermarket is an increasingly important lever for market share and margin expansion.
M&A, Partnerships and Channel Plays to Watch in 2026
Market concentration metrics suggest incumbents can materially shape distribution and service economics. Expect three tactical playbooks to dominate M&A and partnerships:
- Horizontal consolidation to secure regional scale and reduce fragmentation in aftermarket service networks.
- Vertical moves—either acquiring distribution assets or partnering with finance and service firms—to capture recurring revenue and extend customer lifetime value (as illustrated by recent distribution acquisitions and distributor awards).
- Technology partnerships that accelerate digital service delivery and retrofit programs, enabling OEMs to monetize telematics through subscription models.
What PW Consulting’s Full Report Delivers (Practical, Executable Outputs)
- Forecast model with scenario planning (base, downside, upside) and sensitivity testing for energy prices and regulatory shifts.
- TCO calculators and procurement playbooks tailored to operators, corporate real estate managers, and large institutional buyers.
- Supplier and component risk matrices, including raw‑material exposure and recommended hedging/sourcing strategies.
- Competitive benchmarking that combines product, channel, and aftermarket scoring—actionable for commercial and M&A teams.
- Regulatory impact matrix and compliance timelines for target markets, with prioritized mitigation actions.
- M&A target shortlists and integration checklists oriented to both scale and capability acquisition.
- Operational roadmaps for OEMs and large end‑users covering retrofit sequencing, predictive maintenance rollouts, and spare‑parts optimization.
Each deliverable is supported by reproducible data tables, benchmarking dashboards, and an executive briefing pack designed for board and investor discussions. Note: detailed regional, type and application splits are maintained as proprietary datasets in the full report and are intentionally not reproduced here.
How to Use This Intelligence in 2026
- Executives: Use our scenario models to validate capex timing and scale manufacturing footprints in line with the 2026 demand inflection.
- Product Leaders: Prioritize modular, retrofitable controls and energy‑recovery features that shorten payback under mainstream TCO assumptions.
- Commercial Heads: Reconfigure distributor incentives to reward lifecycle revenue and certification attainment rather than one‑time hardware sales.
- Private Capital and M&A Teams: Focus on targets that complement service capabilities, telematics stacks, or regional distribution strength rather than purely product scale.
- Procurement: Integrate TCO calculators into RFPs and require validated sanitization and efficiency certifications as pass/fail criteria.
Closing Note
In 2026 the market presents both opportunity and complexity: growth is real and measurable at the macro level, but value will accrue to firms that can translate product innovation into verifiable lifecycle savings, secure resilient supply chains, and monetize aftermarket services. PW Consulting’s full Commercial Heavy‑Duty Laundry Machinery Market report provides the granular segmentation, competitor scorecards, and executable toolkits needed to convert these market dynamics into concrete plans. For access to the complete datasets, segmentation tables, and proprietary models, please visit our report page.
For detailed analysis of this topic, please visit the official page: Commercial Heavy-Duty Laundry Machinery Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com