

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Spinal Cord Stimulation Market to Reach USD 330 Million by 2032 at 8.2% CAGR

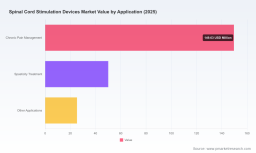
Spinal Cord Stimulation Devices Market — Strategic Outlook for 2026 Decision-Makers
As PW Consulting’s Senior Strategy Advisor and Lead Industry Analyst, I present an executive framing of our latest Spinal Cord Stimulation (SCS) Devices Market study — a practical intelligence brief designed to inform board-level choices, commercial strategy, and capital allocation through 2026 and beyond. This is a forward-looking synthesis: it conveys the high-value signals you need to decide what to pursue next, while preserving the granular model outputs and segment-level estimates for subscribers who access the full report.
Spinal Cord Stimulation Devices Market
Executive snapshot: market momentum and what it means
The global SCS devices market has demonstrated steady expansion through the 2020–2025 base period and is positioned for sustained growth across our 2026–2032 forecast horizon. In our base-year accounting (2025, USD, revenue unit: Million) the market sits in the low hundreds of millions and is projected to grow at a compound annual rate of approximately 8.2% through 2032. Underlying that headline trajectory is an acceleration in technology-driven adoption, evolving reimbursement dynamics, and an expanding clinical footprint for indications beyond classic chronic pain.
Spinal Cord Stimulation Devices Market
- Historical growth has been driven by iterative product innovation, improved patient selection and a maturing clinical evidence base that increases surgeon and payer confidence.
- Near-term forecasts reflect both adoption of closed-loop and high-frequency waveforms and an uptick in outpatient and ambulatory delivery pathways that reduce total cost of care.
- Market concentration is moderate: the top three incumbent firms account for a meaningful plurality of market revenues, with the top five widening that share — a structure that favors differentiated technology plays and targeted commercialization rather than broad-cost disruption alone.
Why this report matters for 2026 corporate decisions
Two strategic timing factors make our 2026-focused guidance particularly consequential:
Spinal Cord Stimulation Devices Market
- First, clinical and regulatory inflection points across multiple vendors are converging into commercial launches and reimbursement updates. These discrete events materially alter addressable markets and channel economics within single fiscal years.
- Second, investor and acquirer attention to medtech portfolio optimization is intensifying. Companies with differentiated closed-loop systems, automated programming capabilities, or non‑invasive clinic/home devices will trade at premium expectations — provided they can demonstrate scalable commercial pathways and repeatable clinical benefit.
For executives weighing R&D prioritization, M&A, or go‑to‑market reorganization, our study translates those macro trends into operational decision levers: which clinical claims to prosecute, which geographies to enter first, and which reimbursement strategies will deliver predictable uptake in 12–36 months.
Market dynamics: reimbursement, delivery settings, and clinical adoption
Regulation and reimbursement remain primary gatekeepers of commercial success. Current payer frameworks and CPT/DRG coding practices continue to shape site-of-care economics, clinician incentives, and patient access. Notably, Medicare coding and payment guidance for SCS procedures — as reflected in national payer resources and vendor reimbursement guides — remain an active component of adoption calculus through 2026. Publicly available coding references continue to define physician payment rates for core implantation procedures and outline documentation expectations for coverage.
- Stable, transparent coding creates predictability for capital planning and pricing strategies for hospital systems and ambulatory surgery centers.
- Shifts toward outpatient and ambulatory surgical center (ASC) models reduce total procedural costs and make value-based contracting with payers more viable for advanced SCS platforms.
- Local coverage policies and coding interpretations remain a regional risk: proactive engagement with payers and targeted health economics dossiers will be necessary to accelerate adoption.
Technology trajectory and product evolution
We observe three convergent technology themes reshaping competitive advantage:
- Closed-loop and sensing-enabled systems that dynamically adapt stimulation to physiologic feedback, improving responder rates and energy efficiency.
- High-frequency and paresthesia-free waveforms that expand patient acceptance and broaden indications.
- Automation in programming and home/clinic-capable non-invasive modalities that reduce clinician burden and improve scalability of follow-up care.
These developments are not theoretical: several vendors have progressed through regulatory milestones and commercial launches that validate technological differentiation and accelerate adoption curves. The practical implication for strategy teams is clear — product roadmaps and clinical evidence generation plans need to be aligned with reimbursement dossiers and channel enablement at the point of launch.
Competitive landscape — positioning, playbooks, and recent catalysts
The competitive topology is dominated by established medtech firms and a set of focused innovators. Incumbents benefit from installed bases, clinician relationships, and broad regulatory footprints; challengers win share through narrow clinical differentiation or lower-cost delivery models.
- Medtronic (HQ: Ireland) continues to invest in closed-loop rechargeable systems and has recent regulatory approvals that put it at the forefront of sensing-enabled platforms.
- Abbott Laboratories (HQ: United States) maintains a strong presence with a portfolio focused on proven waveform efficacy and clinician-oriented programming interfaces.
- Boston Scientific Corporation (HQ: United States) competes with advanced waveform platforms and has codified reimbursement guidance as part of its go‑to‑market support for clinicians and hospitals.
- Nevro Corporation (HQ: United States) leverages high-frequency waveform differentiation as a route to defend and extend its market position.
- Biotronik (HQ: Germany) and Saluda Medical (HQ: United States) illustrate two complementary challenger archetypes — one extending global regulatory reach with new systems, the other introducing automated programming and sensing platforms that enable novel clinical workflows.
Recent regulatory and commercial milestones underscore why 2026 is a pivotal year:
- Several vendors have secured regulatory approvals for closed-loop and sensing-enabled systems in the last 24–36 months, lowering clinical adoption barriers for these technologies.
- At least one company has completed a full U.S. commercial launch for an automated programming platform, signaling a shift from proof-of-concept to scalable commercialization.
- Emergent non‑invasive systems have begun to obtain clearances for clinic and home use in narrowly defined patient populations, introducing an adjacent addressable market that incumbent implantable vendors must monitor.
Collectively, these moves compress time-to-value for companies that can operationalize evidence-to-reimbursement pathways and scale training for implanting physicians.
Strategic implications and recommended actions for 2026
Our analysis yields five high‑impact, actionable recommendations for leadership teams planning investments or strategic shifts in 2026:
- Prioritize clinical claims and evidence generation that directly map to payer value drivers (e.g., responder durability, reduced revision rates, and site‑of‑care cost savings).
- Design launch playbooks that converge clinical, reimbursement, and commercial capabilities — early engagement with payers and ASC networks materially shortens commercialization timelines.
- Consider bolt‑on acquisitions or partnerships to close capability gaps (e.g., programming automation, remote patient management) rather than building all elements in-house.
- Calibrate pricing and contract structures to outpatient and bundled-care models; competitive advantage will accrue to firms that can demonstrate superior total cost of care improvements.
- Use a portfolio approach to balance high‑innovation, high-cost programs with lower-risk product extensions and service offerings that monetize installed bases (e.g., remote monitoring subscriptions, programming services).
What PW Consulting’s full SCS Devices Market report delivers
Our full study is purpose-built to convert market intelligence into immediate commercial action. Subscribers will receive:
- A detailed market model (historical 2020–2025; forecast 2026–2032) with scenario-sensitive outputs and sensitivity analysis for price, penetration, and technology adoption rates.
- Competitor benchmarking: product feature matrices, clinical pipeline mapping, regulatory timelines, and inferred commercial maturity scores for leading players.
- Reimbursement and policy matrix: region-by-region coding, coverage nuances, and payer engagement playbooks tied to launch timing.
- Provider adoption models and clinician decision funnels that identify the fastest routes to procedural volume growth.
- M&A and partnership screening tools: target prioritization criteria and an evidence-based valuation overlay for potential acquisitions.
- A practical commercial toolkit: messaging frameworks, training cadence templates, and an ROI calculator for payer negotiations.
Note: while this executive brief surfaces headline market sizing, CAGR, concentration indicators, and qualitative trajectories, the report itself contains the full segment-level breakdowns (product, application, region), unit economics, and downloadable model files — core assets intentionally gated to preserve the research value for subscribers.
Final perspective — orienting 2026 bets for asymmetric upside
The SCS market in the coming cycle favors companies that can link differentiated technology to verifiable value for payers and providers. With a moderate concentration structure and a forecast growth rate above many traditional medtech segments, the opportunity is meaningful but selective: winning requires coordinated execution across clinical development, regulatory strategy, commercialization, and reimbursement.
PW Consulting’s latest market study is calibrated to help executives make those choices confidently — to prioritize the programs that compound value, to defer or divest those that will be value‑destroying, and to time-market entries so that operational leverage and clinical proof coincide. For teams preparing budgets, evaluating targets, or designing 2026 launches, our report translates uncertainty into an actionable blueprint.
Next steps
Access the full report to unlock the complete market model, competitor scorecards, and our prioritized action roadmap. PW Consulting clients with strategic needs for bespoke scenario modeling, commercial due diligence, or payer engagement support should contact our SCS practice for tailored advisory offerings.
For detailed analysis of this topic, please visit the official page: Spinal Cord Stimulation Devices Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com