

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Desktop IP Phone Market to $517.9M by 2032; 4.25% CAGR Boosts Video Phones

Desktop IP Phone Market 2026: Strategic Playbook — Executive Preview
Introduction
As organisations refine hybrid working models and enterprise communications architectures, desktop IP phones remain a strategic, tangible anchor for voice and video collaboration. PW Consulting’s Desktop IP Phone Market study synthesises five years of historical performance (2020–2025) and projects forward through 2032, delivering a rigorous, decision-ready view for 2026 planning cycles. In brief: the market expanded from roughly USD 301 million in 2020 to about USD 385 million in 2025, and is forecast to continue growing at a steady compound annual growth rate (CAGR) of approximately 4.25%, reaching north of our 2030s horizon by 2032.
Desktop IP Phone Market
Why this research matters for 2026 decisions
- Timing for procurement and refresh cycles: Many enterprises face device refresh decisions in 2026 that will set multi-year standards for cost, security, and user experience. Our research highlights when to accelerate procurement to capture favourable pricing windows and when to delay for improved feature maturity.
- Vendor selection under concentrated supply: With the market exhibiting measurable concentration among a small set of providers, understanding the nuances of vendor roadmaps, certification support, and interoperability becomes mission-critical to avoid lock-in and ensure resilience.
- Risk mitigation from regulation and supply chain shocks: Emerging regulatory constraints and continued component shortages are altering supplier mixes and channel strategies. The study provides scenario-based guidance to help CISOs, procurement leads, and IT strategists preserve continuity while meeting compliance.
- Aligning device strategy with UC and security stacks: Desktop IP phones are no longer simple voice endpoints; they are nodes in unified communications ecosystems, and choices made in 2026 will materially affect integration, user adoption, and total cost of ownership over the coming contract periods.
Market snapshot: growth, rhythm and structure
The desktop IP phone market has moved through a period of measured recovery and steady evolution. After an initial dip and subsequent consolidation in the early 2020s, the market reached approximately USD 385 million in 2025. Our baseline scenario projects continued expansion consistent with a mid-single-digit CAGR (~4.25%) across the 2026–2032 forecast window. Growth is driven by enterprise-grade refresh cycles, widening adoption of video-capable desk phones, and an uptick in purpose-built devices for regulated and secure environments.
Desktop IP Phone Market
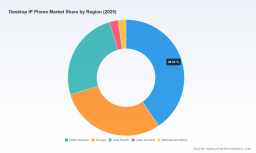
That said, the headline growth conceals important dynamics: product segmentation is shifting toward richer multimedia devices and managed-service driven procurement, while pockets of price pressure and channel diversification persist. To preserve the consultative arc of this preview, the report purposely withholds the granular regional/application splits and product-tier revenue buckets that form the backbone of deployment-level decisioning — these are available through the full study.
Desktop IP Phone Market
Key market dynamics shaping vendor and buyer strategy
- Feature evolution and differentiation: Modern desktop IP phones differentiate through video readiness, integrated wireless connectivity (Wi‑Fi/Bluetooth), AI-enhanced audio (noise suppression and voice isolation), and platform-grade firmware management. Buyers must weigh the incremental value of advanced displays and video against lifecycle costs and interoperability constraints.
- Hybrid work permanence: Hybrid workplace models are increasing demand for devices that balance office-grade ergonomics with remote deployment ease. This is driving the adoption of Wi‑Fi-enabled and soft-client-friendly models, but also sustaining demand for robust desk phones in call-centre and regulated settings.
- Concentration and competition: Market concentration is meaningful: the top three and top five suppliers account for a substantial portion of revenue, shaping price dynamics, support models, and channel relationships. This concentration benefits enterprise buyers through mature feature sets and certified integrations, but it also raises questions about replacement flexibility and supplier leverage during supply disruptions.
- Regulatory and geopolitical frictions: Regulatory measures implemented in 2026 and beyond—affecting device authorisations and the inclusion of certain suppliers on covered lists—have immediate implications for procurement strategies, especially for North American and allied-market deployments. Compliance-conscious buyers must incorporate regulatory screening into vendor onboarding and lifecycle management.
- Supply chain fragility: Persistent component shortages and longer lead times for specialised parts continue to pressure time-to-deploy and cost. Enterprises should design procurement windows that provide buffer for extended lead times and prioritise suppliers with diversified manufacturing footprints and transparent supply-chain visibility.
Competitive landscape — what senior buyers should know
Our competitive mapping focuses on the leading enterprise vendors and emerging specialists that matter to mid-to-large buyers. The report delivers comparative intelligence across product families, certification coverage, enterprise integration capabilities, and go-to-market approaches.
- Cisco Systems, Inc. — A dominant enterprise incumbent, Cisco’s desk phone portfolios emphasise broad feature coverage, deep firmware and platform integration, and enterprise-grade support. Their higher-end IP Phone series are positioned for organisations prioritising unified management and large-scale interoperability with Cisco infrastructures.
- Yealink (Yunnan Guangtian Technology Co., Ltd.) — Yealink’s T-Series and W-Series deliver compelling value on features such as Wi‑Fi and multi-line support, making them attractive for cost-conscious deployments that still require advanced endpoint capabilities and third-party PBX compatibility.
- Poly (HP Inc.) — Poly focuses on audio quality and workplace productivity features (e.g., NoiseBlockAI), with a portfolio addressing both voice-first and video-enabled desktop use cases; Poly’s devices are often chosen where audio fidelity and user experience are priority selection criteria.
- Mitel Networks — Mitel’s portfolio caters to enterprises seeking tight PC and UC integration, with devices that support collaborative workflows and simplified endpoint management, often through managed service partners.
- Grandstream Networks, Inc. — Known for open-SIP support and flexible integration, Grandstream appeals to organisations that prioritise interoperability and alternative UC architectures, including hybrid cloud/private deployments.
- Fanvil, snom, Gigaset — These European and China-based specialists introduce competitive alternatives in quality, certification focus (e.g., Microsoft Teams/Lync support), and regional go-to-market strengths. Recent product launches and certifications highlight their ambitions to move up the value chain and capture enterprise segments requiring specific platform qualifications.
Notably, recent developments — including a refreshed European professional portfolio rollout and new qualification achievements — signal accelerating competition at the mid-to-upper tiers. The report profiles these moves, highlights feature-by-feature differentials, and maps likely competitive responses by incumbent vendors.
Regulations and supply-chain headwinds — preparing for the upside and the downside
- Regulatory risk: Changes enacted in 2026 around device authorisation and covered vendor lists are creating immediate sourcing implications. Buyers must incorporate regulatory checkpoints into vendor selection and consider dual-sourcing options for mission-critical endpoints.
- Component constraints: The enterprise voice equipment supply chain remains subject to disruptions that extend lead times and occasionally force SKU rationalisation. Effective procurement will mix forecast-driven orders, flexible contract terms, and inventory hedging where appropriate.
- Security posture: As desk phones become more capable (video, app platforms), they also expand the attack surface. The full study contains a security due-diligence checklist for evaluating firmware update practices, encryption standards, and device management hygiene.
What the full PW Consulting report delivers (operational toolkit)
Beyond strategic narrative, the study is designed as an operational toolkit for procurement, IT architecture, and security teams. Key deliverables include:
- Scenario-based demand forecasting and procurement timing guidance mapped to contract cycles and expected lead times.
- Vendor scorecards comparing product families on integration, certification, management, and TCO dimensions (note: this preview intentionally omits granular split data and score values).
- Device selection decision trees tailored to workplace archetypes (corporate office, hybrid knowledge workers, contact centres, regulated facilities).
- A supplier-risk playbook addressing regulatory screening, dual-sourcing criteria, and contingency planning.
- Practical deployment checklists: firmware policies, QoS prerequisites, PoE and power budgeting, and lifecycle replacement triggers.
- Financial models and benchmarking templates for calculating TCO, depreciation, and managed-service trade-offs over 3–7 year horizons.
Strategic recommendations for 2026
- Adopt a hybrid procurement posture: Combine short-term tactical buys to satisfy immediate needs with strategic agreements that include flexibility clauses for regulatory changes and component volatility.
- Prioritise certification and lifecycle assurances: Devices with proven platform certifications and committed firmware support reduce integration risk and total cost over long upgrade cycles.
- Design for interoperability: Avoid undue dependency on single-vendor proprietary features unless those features deliver clear, measurable value that justifies potential lock-in.
- Embed security and compliance into procurement: Treat device selection as part of the security architecture; require vendors to demonstrate patch cadences, secure boot, and OTA update practices.
- Use pilots to de-risk new device classes: Pilot video-capable and Wi‑Fi-enabled desk phones with cross-functional teams to verify network readiness, user acceptance, and management workflows before large-scale rollouts.
Next steps & how to use this preview
This piece is a decision-oriented preview designed to emphasise the strategic levers and operational actions that will matter most in 2026. For procurement teams, IT architects, and board-level sponsors, the full PW Consulting Desktop IP Phone Market report provides the granular segmentation, regional demand matrices, vendor-level revenue and share analytics, and downloadable templates that turn strategy into executable plans.
We have intentionally withheld detailed regional and application splits and certain sensitive competitive metrics in this preview to ensure that the full intelligence package retains its operational value for subscribers. If you are preparing a procurement cycle, refreshing device standards, or embedding endpoints into a larger UC transformation, the full report will provide the empirical backing and tools to execute with confidence.
Conclusion
The Desktop IP Phone market in 2026 is at a decision inflection: steady growth, concentrated supplier dynamics, regulatory shifts, and supply-chain realities demand a more disciplined, risk-aware procurement and deployment practice. PW Consulting’s study equips leaders with the forecasts, competitive intelligence, and practical tools needed to make those decisions — while reserving the granular data that operational teams require in the full research product. For a complete package including vendor scorecards, region-by-region demand matrices, and downloadable TCO models, refer to the report access page.
For detailed analysis of this topic, please visit the official page: Desktop IP Phone Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com