

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Bluetooth Speaker Market to Reach USD 64.07 Billion by 2032

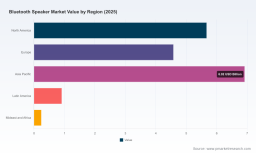
Bluetooth Speaker Market: Strategic Intelligence Briefing for 2026 Decision-Makers
As organizations calibrate strategy for 2026, the Bluetooth speaker market presents a rare convergence of rapid growth, technological differentiation, and geopolitical stress. PW Consulting’s latest market study—anchored on a 2025 base year and projecting through 2032—shows a market accelerating from a mid-single-digit billion-dollar base in 2020 to a materially larger global opportunity by the mid-point of the forecast. The study’s modeled trajectory implies a compound annual growth rate of 19.65% across the forecast window, with the market expanding significantly year-on-year into 2026 and beyond. This briefing synthesizes the study’s strategic implications: what leaders must act on now, which scenarios to plan for, and where to look for asymmetric advantage—without giving away the report’s granular segmentation, which remains gated in the full deliverable.
Bluetooth Speaker Market
Why this market matters for 2026 strategy
-
Scale and velocity: The Bluetooth speaker market has moved from niche consumer segments into a broad consumer and commercial adoption phase. The growth profile reflected in our forecast represents both expanding unit demand and rising average selling prices in selected premium niches.
Bluetooth Speaker Market -
Fragmented competition: Despite accelerating demand, market control remains dispersed. The top players together account for roughly a quarter to slightly under one-third of industry revenue—leaving substantial room for challenger brands, private-label entrants, and white-label manufacturers to win share.
Bluetooth Speaker Market -
Technology and ecosystem effects: Feature differentiation (wireless protocols, multi-room ecosystems, broadcast audio standards, app/platform integration) is becoming as important as raw acoustic performance in capturing lifetime customer value.
-
Macro risk overlay: Tariff regimes, export controls on critical materials, and raw material inflation are actively reshaping cost curves and supply choices—making location, supplier diversification, and procurement strategy critical for 2026 planning.
What the PW Consulting report delivers (practical, decision-ready content)
The full study is purposely operational. Clients receive not just market sizing and trend narratives, but tools to convert insight into action. Highlights include:
-
Scenario-driven demand models calibrated from 2020–2025 historicals and projecting 2026–2032; each scenario maps to explicit triggers (tariff escalation, rapid battery-cost declines, broadcast audio adoption) so you can stress-test product and geographic plans.
-
Go‑to‑market playbooks for distinct strategic profiles—premium brand builders, value-volume players, and B2B/contract manufacturers—detailing channel mix, promotional elasticity, and aftermarket monetization levers.
-
Supply chain risk matrix that scores suppliers by concentration, exposure to tariff lines, raw material dependencies (notably magnets and lithium cells), and lead‑time volatility—with mitigations ranging from hedging to dual‑sourcing and partial nearshoring.
-
Cost‑to-serve and margin models under alternative tariff and raw material scenarios, enabling CFOs to simulate price pass-through, rebate programs, and margin protection strategies for 2026 price-setting cycles.
-
Compendium of product feature trends and consumer demand signals—battery endurance, IP ratings, wireless broadcast audio (Auracast), multi-room interoperability, and embedded voice/assistant stacks—ranked by willingness-to-pay and churn impact.
-
M&A and partnership target shortlist with valuation heuristics tailored to acquirers seeking scale, technology, or channel access; includes playbooks for integrating IP, manufacturing assets, and cross-selling into existing platforms.
Competitive landscape: who’s shaping the market and how
The market includes a blend of legacy audio incumbents, technology-driven challengers, and fast-moving consumer electronics brands. Strategic implications differ by positioning:
-
Bose Corporation (Framingham, MA): Continues to anchor a premium portable portfolio focused on acoustic performance and brand cachet. Their pathway centers on product refinement and protective margins—competitors should assume continued premium pricing power and strong brand loyalty in noise-cancelling and portable audio segments.
-
Harman International (JBL, Harman Kardon) (Stamford, CT): Leverages scale and broad channel reach to defend mass-premium territory. Recent device refreshes signal that incremental product cadence and durability enhancements remain central to defending share.
-
Sony Group Corporation (Tokyo): Aggressive feature-based innovation—exemplified by its second-generation ULT Power Sound series launched during 2025—points to a strategy blending ruggedization, party-oriented features, and advanced audio processing.
-
Ultimate Ears (Indianapolis): Maintains outdoor- and party-market credibility through product specialization; their playbook highlights experiential differentiation over price-led competition.
-
Anker Innovations / Soundcore (Shenzhen): Demonstrates how aggressive cost structures and rapid product cycles can capture volume at attractive margins. The company’s January 2025 product introduction shows continued emphasis on battery life and ingress protection as differentiators.
-
Marshall Amplification (London): Positions around design-led premium offerings, now fortified by durability features and user controls—appeals to lifestyle‑conscious buyers rather than pure audiophiles alone.
-
Tribit and Guangzhou Deyin: Represent robust OEM/ODM capacity from China with product strategies focused on ruggedness and battery life—forms of competitive pressure that impact pricing in outdoor/utility segments.
-
Klipsch and Sonos: Klipsch is leaning into broadcast audio support and heritage sound, while Sonos maintains momentum in home multi-room systems—two different routes to lock-in and recurring revenue via ecosystems and licensing.
Recent product activity and strategic cues (2025–mid‑2026)
-
Sony’s ULT Power lineup (Aug 2025) emphasizes party-mode features and wireless robustness—signal: software-enabled experience is a near-term battleground.
-
JBL’s Flip 7 and Charge 6 (May 2025) showcase incremental hardware refinement to defend the high-volume outdoor/portable segment.
-
Klipsch’s tease of Auracast-capable models and Marshall’s IP67-rated releases (May 2025) point to emergent feature standards and a push toward durability as a purchasing criterion.
-
Anker’s Boom Go 3i (Jan 2025) reiterates value plays premised on long battery life and ingress protection—validating that consumer priorities remain heavily practical as well as experiential.
Regulatory and supply-side shocks to price in for 2026
-
Tariff volatility: Recent U.S. tariff actions have materially raised landed costs for electronics and reportedly resulted in tens of billions of dollars in tariff payments across the consumer tech sector. Manufacturers and importers must model tariff pass-through and consider inventory timing and alternate routing.
-
Targeted increases: Semiconductors and lithium‑ion batteries are now subject to escalated tariff lines in some jurisdictions—this directly affects BOM dynamics for higher-end and battery‑heavy portable models.
-
Export controls: Controls on rare earths and critical inputs introduced by major suppliers reshape long-run sourcing strategies; expect upward pressure on magnet costs unless firms secure alternative suppliers or invest in material substitution R&D.
-
Raw material stress: The cost trajectory for neodymium magnets and lithium cells is exerting downward pressure on manufacturer margins. Short-term hedging, longer-term supplier partnerships, and design-for-supply adjustments are pragmatic responses.
Immediate and medium-term strategic priorities for 2026
-
Supply chain rebalancing (0–12 months): Employ the report’s supplier exposure heatmap to prioritize dual-sourcing for batteries and drivers, evaluate nearshoring vs. tariff-hedging logistics, and accelerate long‑lead procurement where tariffs are likely to bite.
-
Product and portfolio hygiene (6–18 months): Rationalize SKUs to reduce complexity, invest selectively in features that increase willingness-to-pay (battery life, IP rating, multi-device pairing, broadcast audio), and test tiered service bundles to extract recurring revenue.
-
Channel and pricing experiments (6–12 months): Use localized pricing models to absorb tariff shocks in priority markets, pilot subscription-led warranties or app ecosystems, and expand B2B propositions for venues and events where returns on durability and sound levels are higher.
-
Strategic M&A and partnerships (12–36 months): Target acquisitions that bring supply security (battery or magnet supply), software/IP (ecosystem control, broadcast audio), or channel access; prioritize assets that accelerate margin recovery under stressed cost scenarios.
-
Regulatory scenario planning (ongoing): Maintain a triggered-monitoring framework tied to tariff, export control, and environmental compliance thresholds; pre-authorize contingency plans for rapid manufacturing reallocation.
What this means for executives reading in 2026
For CEOs, CFOs, and Heads of Product, 2026 is the inflection year where strategy must shift from reactive cost management to proactive capture of value through differentiation and supply security. The growth runway is attractive—driven by both unit demand and monetization opportunities—but the path to durable margin expansion is narrow unless firms can pair product-level innovation with robust supply countermeasures.
PW Consulting’s full report provides the executable models, scenario triggers, supplier scorecards, and a prioritized list of initiative portfolios to translate this insight into measurable outcomes. We intentionally withhold the report’s detailed regional and application-level splits in this briefing to preserve the study’s gate-kept competitive utility; the full intelligence package contains those segmentation layers along with executable playbooks and model files.
Next steps
-
Download the PW Consulting market study to access the segmented models, the supplier risk dashboards, and the M&A target shortlist that inform 2026 capital and product decisions.
-
Request a tailored executive workshop where we stress‑test your portfolio against the report’s scenarios and produce a prioritized 90‑day action plan for procurement, R&D, and channel strategy.
In a market forecasted to expand sharply through the coming decade, the difference between winners and laggards will be determined by how quickly they convert insight into supply‑secure, feature‑differentiated product portfolios. PW Consulting’s Bluetooth Speaker Market study is designed to be the operational intelligence that helps you win that race.
For detailed analysis of this topic, please visit the official page: Bluetooth Speaker Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com