

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: PC System Utilities Market to Grow at 4.11% CAGR to $22.74B by 2032

PC System Utilities Software Market 2026: Strategic Briefing for Decision‑Makers
As PW Consulting’s lead industry analyst, I present a focused strategic briefing that frames the PC system utilities software market as you prepare major 2026 decisions. This is a trailer — a concise, high‑signal distillation of the full study that demonstrates analytical depth while preserving the report’s proprietary segment tables and tactical playbooks for subscribers. Below you will find the macro trajectory, competitive posture, regulatory headwinds, and the practical levers executives must evaluate this year.
PC System Utilities Software Market
Macro snapshot: growth trajectory and what it means for strategy
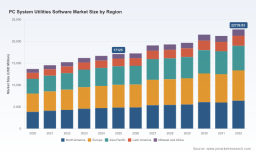
Between 2020 and 2025 the PC system utilities software market expanded materially, reflecting continued demand for performance optimization, cleanup, and recovery tools as PCs remain central in hybrid work and digital transformation environments. Using 2025 as the base year and a forecast window from 2026–2032, our proprietary model projects a steady compound annual growth rate (CAGR) of approximately 4.11% through 2032. By the end of the forecast horizon the market is expected to reach the mid‑twenty billion dollar range (measured in USD).
PC System Utilities Software Market
Why this matters in 2026: a 4% CAGR denotes a mature market with steady consumption but rising competitive and margin pressures. Growth is sufficient to reward disciplined product and go‑to‑market (GTM) innovation, yet not so rapid that incumbents can rely on rising tides. Strategic choices this year must therefore prioritize margin protection, differentiation, and recurring revenue models rather than pure top‑line capture.
PC System Utilities Software Market
Market structure and competitive context
-
Concentration: Our concentration analysis shows a mid‑level consolidation dynamic — the top three vendors account for a significant but non‑dominant portion of the market, and the top five capture just over half of total industry revenue. That structure creates a corridor of opportunity: well‑funded challengers can grow through focused feature differentiation, partnerships, and channel plays, while incumbents must defend with scale, brand trust, and platform integration.
-
Incumbent archetypes: Vendor positions range from lightweight, consumer‑oriented cleaners to full‑suite optimizers and recovery specialists. Some players compete on freemium acquisition funnels and upsell into paid utilities; others pursue enterprise features and service packaging for SMBs and managed service providers (MSPs).
-
Competitive pressure from platform owners: Recent updates to native platform offerings illustrate a new competitive variable. Large platform vendors are improving built‑in maintenance and monitoring functions — a trend that increases the bar for third‑party utilities and compresses feature differentiation unless vendors pivot to value‑added capabilities (security integration, privacy safeguards, enterprise reporting, or specialized recovery functionality).
Key vendors — positioning and strategic moves to watch
-
Specialist optimizer players: Companies offering comprehensive system optimization suites remain relevant by consolidating complementary functions (tuning, disk cleanup, registry repair, and telemetry‑driven recommendations). Their strategic advantage is deep feature breadth and user familiarity; their risk is commoditization by OS‑level improvements.
-
All‑in‑one cleaners and security hybrids: Some vendors combine optimization with security features to create sticky value for users. This hybrid model supports subscription economics but increases product complexity and regulatory exposure (data handling from system scans and security telemetry).
-
Regional and product niche players: Firms that focus on particular regional channels, language packs, or specialized features (e.g., advanced data recovery) can generate attractive margins through curated offerings and distribution alliances with OEMs and VARs.
In short, vendor strategies that will win in 2026 lean into either (a) platform integration and enterprise features, (b) bundled security/maintenance suites for SMBs, or (c) aggressive freemium funnels that convert to add‑on services. Purely commodity feature sets without defensible data or partnership moats face margin erosion.
Regulation, compliance and operational cost drivers
-
Privacy and compliance: The regulatory environment increasingly shapes product design. Data privacy rules and international compliance standards (including ISO 27001 alignment expectations) require explicit controls over system scan telemetry, user consent frameworks, and secure storage. Vendors that bake compliance into product architecture reduce sales friction with enterprise buyers.
-
Infrastructure and labor: Cloud hosting for update delivery, telemetry ingestion, and secure user data repositories elevates infrastructure costs. Simultaneously, specialized engineering and maintenance labor are among the largest cost items for utilities vendors. Strategic sourcing, automation in CI/CD, and efficient telemetry sampling can materially improve unit economics.
-
Platform vendor activity: Native PC management updates from major OS players change the competitive baseline. Vendors must evaluate defensive engineering and partnership options — for example, offering advanced capabilities that complement native utilities rather than compete head‑on.
Strategic implications for buyers, vendors and investors in 2026
-
For enterprise buyers: Prioritize vendors that demonstrate enterprise‑grade privacy controls, transparent telemetry practices, and contractual compliance. Demand benchmarked ROI analyses (productivity gains, device life extensions) and insist on interoperable APIs for centralized device management.
-
For software vendors: Convert one‑time buyers into recurring revenue via modular subscriptions, MSP partnerships, and lifetime value‑focused product roadmaps. Invest selectively in AI/ML capabilities that deliver measurable end‑user value (predictive maintenance, anomaly detection) rather than cosmetic feature launches.
-
For OEMs and channel partners: Integrate differentiated utilities into OEM‑branded experiences or subscription bundles. Co‑marketing deals and pre‑installation agreements with secure opt‑in flows will create the best conversion economics.
-
For investors and M&A teams: Look for targets with defensible data assets, strong channel relationships, and margin improvement levers such as automation and enterprise packaging. The mid‑market consolidation opportunity remains real, given the market’s moderate concentration and fragmented mid tier.
Actionable frameworks — what to test and measure in 2026
-
1) Product differentiation heatmap: Map all features against buyer value (consumer vs. SMB vs. enterprise) and competitor saturation. Prioritize development where value is high and competition is thin.
-
2) GTM channel experiment matrix: Run short, instrumented pilots with OEM preloads, MSP bundles, and direct‑to‑consumer freemium funnels and measure CAC payback and conversion to recurring revenue.
-
3) Compliance readiness checklist: Implement privacy‑by‑design assessments, ISO 27001 gap closure plans, and contractual templates to accelerate enterprise procurement.
-
4) Unit economics playbook: Model infrastructure (hosting, CDN, telemetry ingestion) and labor cost scenarios; prioritize automation to reduce maintenance burn.
What the full PW Consulting report delivers (practical, playbook‑oriented)
Our full-length study provides the granular intelligence executives use to translate strategy into execution. Highlights include:
-
Market sizing and forecasting methodology with scenario analyses extending through 2032, including upside/downside scenarios and sensitivity to platform vendor incursion and macro volatility.
-
Segment deep‑dives with buyer personas, adoption pathways, and pricing elasticity insights (note: detailed segment tables and numeric splits are available in the full report).
-
Vendor scorecards and competitive benchmarking across product, distribution, security posture, and churn metrics for the core players in the market.
-
Tactical GTM templates for OEMs, MSP partners, and direct sales — including pilot scope, KPI dashboards, and short‑term commercial structures to accelerate 12‑month traction.
-
M&A playbook — valuation heuristics, integration risks, and a shortlist of strategic acquisition profiles for buyers seeking inorganic growth.
-
Regulatory and compliance annex with implementation checklists to align product roadmaps and contracts with contemporary data protection expectations.
-
ROI calculators and scenario models you can plug your own metrics into to produce board‑ready projections.
Closing: the strategic choice for 2026
The 2026 inflection point is clear: the PC system utilities market remains sizable and resilient but demands strategic clarity. Winners will be those who convert product familiarity into durable business models — through subscription economics, compliance as a sales asset, and partnerships that offset native platform headwinds. PW Consulting’s full report arms decision‑makers with the quantification, vendor intelligence, and execution playbooks needed to choose the right path.
To access the complete dataset, proprietary segment tables, and vendor scorecards that underpin these conclusions, please visit the report page. PW Consulting subscribers will receive model files, scenario calculators, and an executive workshop package designed to operationalize 2026 plans within 90 days.
For detailed analysis of this topic, please visit the official page: PC System Utilities Software Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com