

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
Halogen-Free Flame Retardants: USD 2.47B in 2025 to USD 3.45B by 2032 (4.9% CAGR)

Halogen-Free Flame Retardant Chemicals Market: Strategic Briefing for 2026 Decision-Makers
As PW Consulting’s senior strategy advisors, we present a concise, decision-focused introduction to our full Halogen-Free Flame Retardant (HFFR) Chemicals Market study. This briefing synthesizes the high-level market trajectory, near-term dynamics that will shape procurement, R&D and M&A decisions in 2026, and the competitive vectors that matter. The full report (base year 2025, historical coverage 2020–2025, forecast 2026–2032) contains the granular segment tables, regional and application splits, and interactive financial models that should inform board-level choices; this preview intentionally highlights strategic direction while withholding the detailed segment-level data to guide you to the source for execution-level intelligence.
Halogen-Free Flame Retardant Chemicals Market
Market trajectory at a glance
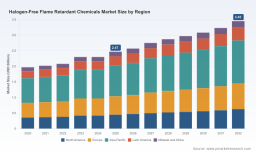
The HFFR market has transitioned from a niche regulatory-compliance play to a structurally growing global chemical sub-sector. Total industry revenues grew from USD 1.96 billion in 2020 to USD 2.47 billion in 2025 (base year), reflecting accelerating substitution away from legacy halogenated systems in safety-critical end markets. Under our baseline scenario — which incorporates continuing regulatory tightening, steady end-market recovery in construction and electronics, and gradual adoption in transportation and specialty polymers — the market is projected to expand at a compound annual growth rate of 4.9% through 2032, reaching approximately USD 3.45 billion by the end of the forecast horizon. This is steady, investible growth rather than runaway expansion, which places a premium on differentiated product strategy and supply security.
Halogen-Free Flame Retardant Chemicals Market
What is driving growth — and what will constrain it?
- Regulatory push and product substitution: Accelerating fire-safety mandates (notably under REACH and RoHS-aligned regimes) are increasing the compliance burden on OEMs in construction, electronics, and transport. Buyers are shifting toward halogen-free chemistries not only to meet legal requirements but to avoid downstream liabilities and to improve sustainability credentials.
- End-market electrification: The growth of e-mobility and denser electronics board designs increases demand for flame retardants that balance thermal, mechanical and smoke-toxicity performance. Performance-driven specification changes are opening premium niches for certain phosphorus-based and engineered additive systems.
- Raw-material and logistics pressure: Feedstock dynamics are a tangible constraint. For example, magnesium hydroxide pricing trends have shown upward pressure — a recent index noted a price rise in North America in early 2026 driven by freight and feedstock inflation. Brucite ore, the primary natural feedstock for Mg-based products, is concentrated in regions exposed to geopolitical risks; this creates supply volatility that can ripple through pricing and availability.
- Market concentration and capacity moves: The market is moderately concentrated: the top three players account for a material share of the industry, with additional scale in the top five. Large incumbents are expanding capacity and deepening portfolios (notable rollouts and production line additions occurred in 2025), which will influence supplier bargaining power and speed of technology diffusion.
Supply-side dynamics: what procurement and operations teams must model
Supply-side risk in 2026 will be a function of feedstock concentration, logistics costs, and targeted capacity expansions. Two operational imperatives emerge:
Halogen-Free Flame Retardant Chemicals Market
- Secure feedstock chains: Buyers should treat long-term agreements for brucite-derived inputs and specialty phosphorus precursors as strategic assets. Where feasible, structure contracts with indexed pricing and take-or-pay clauses to hedge freight-driven spikes while preserving optionality for alternative chemistries.
- Assess capacity overlays: Recent capacity investments by incumbent manufacturers indicate that supply will adjust, but not uniformly across chemistries. Companies should map supplier footprints against their own production locations and end-market exposure to quantify landed-cost risk and lead-time sensitivity.
Competitive landscape — where the strategic battlegrounds are
The competitive field comprises multinational specialty chemical groups, regional mineral suppliers, and compounders that integrate formulation expertise with downstream service. Key archetypes and representative players (covered in-depth in our report) include:
- Technology-driven specialty producers: Established multinationals that combine proprietary flame retardant chemistries with global supply and regulatory capability. Their playbook focuses on performance differentiation for engineering plastics and electronics applications, plus investments to reduce volatility in ancillary antimony or halogenated systems.
- Commodity mineral suppliers: Firms supplying aluminum trihydrate (ATH) and magnesium hydroxide — competing on scale, cost, and the ability to offer low-dust, pre-treated grades that reduce downstream processing costs for compounders and OEMs.
- Compounding and formulation specialists: Smaller, agile suppliers that convert base additives into application-ready, non-halogenated compounds, capturing margin via customization for cable, textile and automotive interiors.
Representative firms profiled in our study include Clariant AG (leading Exolit OP phosphorus-based solutions for engineering plastics and e-mobility), Lanxess AG (additives and polymer solutions for electronics and construction), Huber Advanced Materials (ATH and MgOH supply), RTP Company (compounded non-halogenated compounds), and regional players such as Oceanchem Group and SK Minerals & Additives. Each of these competitors pursues distinct routes to value: IP-led product portfolios, vertical integration into mineral feedstocks, or localization and cost-advantage plays in emerging markets.
Recent strategic moves to monitor
- Major incumbents completed targeted expansions and introduced next-generation halogen-free formulations in 2025–2026, reflecting both demand confidence and an intent to pre-empt supply tightness.
- Regional suppliers have launched indigenous brands aimed at local OEMs and rising domestic standards — a trend that will intensify price competition while improving availability for local manufacturing ecosystems.
- Raw-material price indices and sourcing bottlenecks are already impacting contract negotiations; expect more supplier-driven cadence in price adjustments in 2026 unless larger buyers secure long-term hedges.
Strategic implications for 2026 decisions — a playbook
Executives planning capital allocation, sourcing, or product strategy in 2026 should prioritize the following actions:
- Supply diversification and strategic sourcing: Negotiate multi-supplier frameworks that include a mix of incumbent global suppliers and selected regional producers to balance cost and continuity. Consider forward-buy programs or shared inventory pools for critical feedstocks.
- Focused R&D and product roadmaps: Invest in formulations that reduce the total additive load while meeting smoke and toxicity targets. Position new product launches against evolving regulatory thresholds and OEM specification windows to shorten sales cycles.
- M&A and partnership scouting: Prioritize bolt-on acquisitions that close capability gaps (compounding, downstream testing labs, or local mineral assets) over broad conglomerate buys. Strategic partnerships with OEMs can convert specifications into stickier adoption curves.
- Commercial segmentation and pricing discipline: Use value-based pricing in high-spec segments (e.g., e-mobility, medical-grade plastics) while protecting margin through cost-to-serve optimization in commodity channels.
- Regulatory go-to-market readiness: Prepare dossiers and certification roadmaps for REACH, RoHS and equivalent regional regimes; proactive compliance will be a commercial differentiator for suppliers and buyers alike.
What PW Consulting’s full report delivers — operational tools, not just analysis
Our comprehensive study translates this strategic framing into deployable assets for 2026 decision cycles. Highlights include:
- Interactive market-model (2020–2032) with scenario toggles for high/low regulatory stringency and raw material shocks.
- Competitive heat maps and supplier capability matrices with verified profiles and contacts for targeted procurement outreach.
- Supply-chain stress-testing templates and recommended contract language for feedstock hedging and service-level guarantees.
- Technology deep-dives on phosphorus-based systems, aluminum trihydrate and magnesium hydroxide chemistries, with comparative performance and processing trade-offs.
- Regulatory impact matrices and a certification roadmap for REACH/RoHS alignment across geographies.
- Commercial playbooks for entering or defending priority end-markets, including sample business cases for vertical integration and co-development agreements with OEMs.
90-day executive roadmap
- Days 0–30: Run a supplier risk heat-map and identify single points of feedstock exposure. Begin prioritizing critical specs for product testing in high-growth end-markets.
- Days 31–60: Engage two alternate suppliers and negotiate pilot supply agreements. Launch accelerated R&D sprints for at least one high-value phosphorus-based or engineered additive formulation.
- Days 61–90: Finalize commercial terms for supply-side protection (e.g., indexed contracts, inventory-sharing), and present an integrated investment case (capex vs partnership vs acquisition) to the executive committee.
Why this matters now
With the HFFR market characterized by steady CAGR-driven expansion, regulatory acceleration, and supply-side pinch points, 2026 is a year to convert strategic intent into structural advantage. Companies that lock in diversified feedstock access, move early on performance-differentiated chemistries, and align commercialization to tightening regulatory windows will capture durable margin. Conversely, passive strategies that delay supplier rationalization or product certification risk higher spot exposure and slower adoption curves.
For boards and commercial leaders, our study is designed to convert uncertainty into prioritized action. To access the segment-level matrices, supplier scorecards, and interactive forecast models that underpin this briefing, please refer to the full Halogen-Free Flame Retardant Chemicals Market report available on our website. PW Consulting’s industry team stands ready to run customized scenario workshops and supplier negotiations support tailored to your portfolio.
For detailed analysis of this topic, please visit the official page: Halogen-Free Flame Retardant Chemicals Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com