

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Vanillin Market to Grow at 7.5% CAGR Through 2032

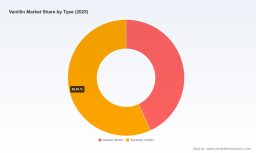
Vanillin Market — Strategic Outlook for 2026 Decision-Making
Executive summary
By 2025 the global vanillin market has emerged from a period of steady recovery into an inflection phase. Our PW Consulting baseline model, calibrated to historical performance (2020–2025), projects a compound annual growth rate (CAGR) of 7.5% across the 2026–2032 forecast window. Under that trajectory, the market doubles in strategic relevance as product formulators, ingredient buyers, and specialty chemical investors confront simultaneous supply-side upheaval, escalating sustainability expectations, and new trade policy constraints. This introduction articulates why the 2026 strategic planning cycle must treat vanillin as a core procurement, innovation and M&A priority, and summarizes the decision-useful outputs contained in our full Vanillin Market report.
Vanillin Market
Why vanillin matters to 2026 strategy
Vanillin is both a commodity and a differentiator. At scale it behaves like a refined petrochemical derivative—sensitive to feedstock cycles and capacity shifts; at the product level it delivers consumer-facing sensory attributes that carry premium positioning in food & beverage, fragrances, and personal care. The market’s mid-single-digit to high-single-digit growth (7.5% CAGR in our base case) masks richer dynamics. For commercial teams and procurement leads planning for 2026, two themes are decisive:
Vanillin Market
- Supply-chain resiliency: regulatory actions and capacity movements have compressed near-term available volumes and changed the cost calculus for import-dependent buyers.
- Portfolio differentiation: demand for certified bio-vanillin and "natural" claims is rising, creating margin dispersion between commodity synthetic grades and higher-value bio-based alternatives.
Market trajectory — the macro picture
Our top-line market-sizing shows consistent expansion from the 2020 baseline through 2025 and onward to 2032 under the base-case growth path. The trajectory reflects sustained demand growth in core end-uses, incremental substitution toward bio-derived and certified-natural offerings, and pricing realignment following recent regulatory interventions. For strategy teams, the implication is clear: volume growth alone will not guarantee margin growth—value capture will increasingly depend on positioning across the synthetic–natural spectrum and the structure of supply arrangements.
Vanillin Market
Key demand drivers and structural risks
- End-use mix evolution: food & beverage remains the primary demand engine, supported by steady gains in pharmaceuticals, personal care and emerging specialty applications. Product developers will need to balance cost-performance trade-offs as customers segment around naturalness and sustainability.
- Feedstock dynamics: guaiacol, the principal petrochemical feedstock for synthetic vanillin, links the vanillin cost curve to broader aromatic feedstock markets. Volatility in upstream petrochemical markets transmits quickly into input costs and contract renegotiation risk.
- Trade and regulatory shocks: in 2025 several jurisdictions instituted anti-dumping and countervailing measures affecting imports from certain origins, materially altering cross-border flows and prompting buyers to re-evaluate sourcing footprints.
- Certifications and sustainability premiums: lignin-derived and other bio-based vanillin producers can command differentiated pricing where traceability and certification (e.g., forest stewardship certifications) are required by brand owners.
Competitive landscape — who matters and what they signal
The vanillin market is moderately fragmented. The leading global flavor & fragrance houses and specialized producers coexist with regional synthetic producers and a growing set of bio-focused suppliers. Our concentration metrics indicate meaningful room for mid-market consolidation alongside strong positions held by integrated global players.
- Major synthetic producers (China & India): Established manufacturers in China and India supply cost-competitive synthetic grades and have historically anchored global spot and contract markets. Their scale and feedstock optimisation capabilities keep synthetic vanillin prices competitive, but export-focused strategies are increasingly exposed to trade-policy shifts.
- Specialist bio and lignin-based suppliers: Producers using lignin or other biomass feedstocks occupy a premium, differentiated niche—certification and traceability are core assets for customers targeting natural claims and sustainability-oriented price premiums.
- Global flavor houses: Multinational groups embed vanillin into broader flavor systems and functional blends, offering customers single-source advantages (formulation, compliance, and global distribution). Their scale allows them to manage inventory and hedge input risks more effectively.
Representative industry participants observed in our competitive mapping include leading synthetic specialists, lignin-origin innovators and vertically integrated flavor houses. Each archetype implies distinct strategic responses: the synthetic players will prioritise cost and access to feedstock; bio-specialists will invest in certification and supply chain traceability; global houses will optimise portfolio-level margin and service integration.
Recent developments that reframe 2026 decisions
- Significant trade remedial measures established in 2025 have increased uncertainty around cross-border supply. Where previously cost-advantaged suppliers could arbitrage regional differentials, those pathways have narrowed—prompting buyers to reassess landed costs and dual-sourcing strategies.
- Targeted capacity adjustments and restarts in specific plants have already moved spot availability and near-term lead times. Market participants will need fast-access scenario models to quantify how plant-level changes translate to regional availability and pricing trajectories.
- Sustainability and certification milestones—particularly for lignin-derived vanillin—are now commercial differentiators. Buyers who can demonstrate certified sourcing are more likely to secure long-term contracts at premium pricing from brand-conscious customers.
Strategic implications for 2026 — what leaders must do
Decisions taken in 2026 will influence cost structures, product portfolios and market share for the remainder of the decade. Our consulting experience highlights five actionable priorities for C-suite and procurement leaders:
- Reassess sourcing architecture: implement regional footprint analysis to determine whether nearshoring, local manufacturing partnerships or multi-origin contracting reduces net landed cost and policy exposure.
- Dual-track product strategy: retain competitive synthetic supply for price-sensitive SKUs while building a validated pipeline of bio-vanillin SKUs for customers demanding natural/sustainable attributes.
- Hedge and procurement sophistication: develop feedstock-linked hedging and multi-year contracting frameworks that balance price certainty with flexibility to adapt to capacity shocks.
- Invest in certification and traceability: for producers and brand owners, certification (and the systems that demonstrate it) unlocks incremental margins and long-term contractual relationships.
- Pursue targeted consolidation and alliances: given moderate market concentration, acquisitive or partnership-based moves can rapidly secure scale, proprietary technologies or geographic reach—especially in a post-trade-remedy context.
What the full PW Consulting Vanillin Market report delivers
Our full report is designed as a decision-ready toolkit for 2026 planning. Key practical deliverables include:
- Transparent market-size model (historical 2020–2025 and scenario-based forecasts to 2032) with sensitivity levers for feedstock, tariffs and bio-adoption rates.
- Granular supply-chain maps and a capacity tracker with plant-level notes and likely near-term availability scenarios.
- Regulatory and trade impact assessment that quantifies tariff scenarios and proposed mitigations for procurement teams.
- Competitive dossier and capability matrix for the leading producers, including strategic positioning, technology routes (synthetic vs. lignin/biotech), and commercialization strengths.
- Commercial playbook: go-to-market strategies for suppliers, procurement negotiation templates, and margin improvement tactics for downstream users.
- Deal origination shortlist: M&A targets and partnership candidates prioritized by strategic fit and integration ease.
- Interactive decision tools (Excel-based) enabling executives to model scenarios for price, volume and margin under alternate policy or feedstock shocks.
To adhere to the "trailer" principle: the public executive summary shows the analytical scaffolding and highlights, while the report itself contains the actionable granular datasets and company-level economics that procurement, R&D and corporate development teams will need to execute in 2026.
Closing — an advisory checklist for immediate action
- Q1 2026: Initiate an immediate sourcing stress test—map current contracts against at-risk suppliers and implement contingency agreements for critical SKUs.
- Q2 2026: Commission a certification gap analysis if pursuing natural/bio claims; prioritize investments that enable two- to three-year contract wins with premium customers.
- Mid-2026: Run an M&A/partnering screen tied to capacity and technology—target assets that close feedstock exposure or secure certified supply chains.
- Continuous: Maintain a rolling scenario model with triggers tied to regulatory announcements and plant-level capacity notifications; align procurement KPIs to the model outputs.
PW Consulting’s Vanillin Market study translates those recommendations into executable plans with quantified trade-offs under alternate policy and commodity price environments. For commercial teams and boards preparing budgets and capital plans in 2026, the report is designed to move from insight to implementation: from sensitivity curves to signed contracts and from strategic options to executed portfolio changes.
Next steps
Access to the full dataset, plant-level capacity tracker, and the scenario modelling tool is available through our Vanillin Market product page. PW Consulting can also deliver a bespoke 1-day strategy workshop that uses your internal volumes and product mix to produce a customised risk-and-opportunity heatmap for 2026. Contact our industry team to schedule a briefing and receive a tailored short list of immediate tactical actions.
For detailed analysis of this topic, please visit the official page: Vanillin Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com