

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Nanoimprint Lithography Market to Reach USD 214.9M by 2032 at 9.55% CAGR

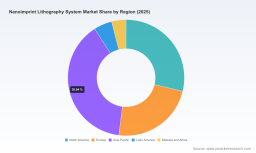
Nanoimprint Lithography Systems: Strategic Preview for 2026 Decision‑Makers
Why this study matters now
As organizations recalibrate capital plans and technology roadmaps for 2026, Nanoimprint Lithography (NIL) is moving from niche R&D use toward commercially meaningful production deployments. Our PW Consulting market model—anchored on a 2025 base year—shows a clear growth trajectory, with the global NIL systems market expanding at a compound annual growth rate (CAGR) of approximately 9.55% and more than doubling over the coming forecast window. That trajectory is not uniform by application or geography, but it is large enough to affect tool‑buying strategies, foundry partnerships, and product roadmaps for semiconductor, photonics and advanced consumer‑electronics manufacturers.
Nanoimprint Lithography System Market
This preview is designed to help executives, product and supply‑chain leaders, and corporate strategy teams act with conviction in 2026: it highlights the structural drivers, competitive moves, and prioritized playbooks they must consider, while reserving the full granular segmentations and financial tables for the complete PW Consulting release.
Nanoimprint Lithography System Market
Report deliverables — practical and operational
- Market sizing & topline forecast (2020–2032): validated historicals, base‑year calibration, and scenario projections to 2032 that support capital planning and valuation work.
- Technology roadmaps and comparative economics: UV‑NIL, thermal/hot‑embossing, step‑and‑repeat, rolling NIL (RNIL) — throughput, yield, cost drivers, and mold‑lifetime tradeoffs.
- Commercial playbooks: go‑to‑market options for OEMs, foundries and systems integrators, including pricing approaches, factory adoption timelines, and pilot-to‑volume conversion checklists.
- Supply‑chain and materials assessment: critical inputs such as quartz/fused‑silica molds, tooling lifecycles, supplier concentration, and mitigation levers for 2026 procurement execution.
- Competitive intelligence and vendor profiles: capability matrices, strategic positioning, and deal‑level signals (recent deliveries, foundry agreements, product launches) for market participants.
- Risk & regulation framework: scenario analyses for policy, energy, and standardization developments that materially influence adoption timing.
- KPIs and investment appraisal templates: concise scorecards for evaluating vendor pitches, pilot projects, and internal investments in NIL competence.
What the headline numbers imply for corporate strategy
The market expansion reflected in our forecast is substantive enough to justify dedicated NIL strategies for companies whose product roadmaps intersect with nanostructured optics, high‑resolution patterning, or cost‑sensitive subwavelength features. For investors and C‑suite leaders, the key takeaways are:
Nanoimprint Lithography System Market
- Timing matters: adoption is accelerating, but capital cycles and qualification timelines remain multi‑year. Early pilots conducted in 2026 are likely to determine supplier selection and volume ramp timing through 2028–2030.
- Economics are shifting: relative to high‑energy lithography platforms, NIL can reduce process energy and mask costs materially for certain classes of devices, altering total cost of ownership (TCO) calculations used in 2026 CAPEX debates.
- Segment‑specific opportunity sizes differ: semiconductors and high‑end photonics show the strongest near‑term demand signals, while larger consumer categories enable scale for lower‑cost NIL variants and imprint‑based manufacturing concepts.
Market dynamics and inflection points to watch in 2026
- Standardization and ecosystem building: industry gatherings and standards efforts in 2026 are reducing technical fragmentation and lowering barriers for factories to adopt NIL for volume. Tracking standards milestones should be part of any procurement decision.
- Materials and throughput constraints: quartz and fused‑silica molds remain the workhorse for high‑resolution patterning; hard mold technologies extend service life but require more robust handling and maintenance regimes. These are central to cost modeling and spares planning.
- Energy and regulatory considerations: NIL removes the need for certain high‑energy lithography sources, offering potential energy‑consumption advantages that align with corporate sustainability targets and regulatory pressures in some jurisdictions.
- Foundry partnerships and service models: demonstrated foundry agreements in 2025–2026 signal that NIL is moving out of point solutions into contractual volume services for optics and specialized semiconductors. Contractual arrangements will influence supplier lock‑in and IP licensing strategies.
- Varied technical approaches: step‑and‑repeat systems, UV‑NIL, hot embossing and rolling imprint each occupy distinct niches; vendor roadmaps and in‑field proof points will be pivotal when prioritizing which approach to back in 2026.
Competitive landscape — strategic positions and implications
Several established and emerging suppliers are shaping the market dynamic. Their public profiles and recent moves provide a useful lens for assessing potential partners and competitors in 2026:
- EVG (Austria): A market leader in UV‑NIL and volume systems, with strong product lines for large‑area substrates and 300 mm wafer production. EVG’s focus on production‑ready systems makes them a natural partner for firms seeking low‑risk scale‑up.
- Canon Inc. (Japan): Bringing precision optical engineering and roadmap capability (including steps toward single‑digit nanometer feature control) — Canon’s narrative centers on bridging R&D and prototype semiconductor use cases to near‑production readiness.
- NIL Technology ApS (Denmark): Focused on mass‑production services for meta‑optics and advanced optics; effective when buyers are evaluating an end‑to‑end supplier that combines equipment with manufacturing service know‑how.
- Obducat AB (Sweden): Strong in micro‑/nano‑lithography with foundry service offerings for photonics and optical components — recent multi‑year supply agreements indicate robust pipeline stability for customers seeking long‑term supply commitments.
- Nanonex Corporation (USA): Known for versatile UV/thermal platforms and 3D nanostructure capabilities — a fit for organizations exploring differentiated device architectures enabled by imprinting.
- Prinano Technology, Stensborg A/S, GermanLitho (China/Denmark/China): Each brings localized manufacturing strength, differentiated product form factors (e.g., rolling NIL, step‑and‑repeat mass‑production tools), and competitive positioning in regional markets — essential considerations for regional supply strategy and cost optimization.
Recent commercial signals — new production deliveries, launch of NIL line capabilities, foundry contracts and visible presence at industry events — show the market is shifting from pilots to commercial engagements. In 2026, vendor selection should weigh not only tool specs but also demonstrated supply reliability, service contracts, and roadmap alignment with your product lifecycle.
Scenario‑based strategic plays for 2026
Based on our scenario analysis, PW Consulting recommends three prioritized plays depending on corporate risk appetite and time horizon:
- Fast‑Follower Production Play (for firms seeking early volume): Secure pilot capacity with a production‑ready supplier, negotiate short‑term foundry contracts to derisk ramp, and lock in mold‑supply agreements to stabilize unit economics.
- Capability Build & IP Play (for firms seeking differentiation): Invest in co‑development with NIL equipment providers to customize imprinting processes, protect resulting process IP, and pilot vertically integrated manufacturing to shorten time‑to‑market for innovative optical or chip features.
- Outsource & Scale Play (for asset‑light firms): Use third‑party NIL foundries and service providers to validate product designs at scale while keeping capital light; reserve long‑term tool purchases until unit economics are proven.
How to convert insight into action in 2026
To operationalize NIL strategy in 2026, leadership teams should consider a short list of concrete near‑term steps:
- Run a 6–12 month pilot with clear acceptance criteria (throughput, defectivity, mold lifetime, cost per piece). Tie performance milestones to go/no‑go funding gates.
- Engage with standardization bodies and industry consortia to influence NIL interface and quality specifications; early engagement reduces integration risk and accelerates factory adoption.
- Map and qualify at least two mold suppliers and establish spares logistics; molds are a key working capital and uptime risk.
- Update TCO models to include energy, mask, and maintenance differentials versus incumbent lithography technologies; use sensitivity analyses to identify breakpoints for investment.
- Monitor vendor commercial signals—deliveries, foundry contracts, product launches—and integrate these as triggers in procurement timelines.
What to expect from the full PW Consulting report
The complete study provides the granular datasets, segmentation tables, and vendor scorecards necessary to finalize procurement and investment decisions. It includes downloadable financial models, build‑vs‑buy calculators, and a prioritized vendor short‑list mapped to seven buyer profiles. This preview deliberately omits detailed segment percentages and contract values to protect primary‑source insights; the full report contains those tables and proprietary scenario outputs that decision‑makers will need to execute in 2026.
For teams planning CAPEX, M&A diligence, or product‑roadmap pivots this year, the full PW Consulting NIL Systems report is designed as an executable toolkit—transforming the market’s growth trajectory and competitive dynamics into clear, prioritized actions you can implement within the next 12 months.
Contact PW Consulting to access the detailed datasets, vendor scorecards, and scenario models that underpin these findings—and to schedule a strategy session that converts NIL opportunity into concrete 2026 outcomes.
For detailed analysis of this topic, please visit the official page: Nanoimprint Lithography System Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com