

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Sparkling Juices Market to Reach USD 2,216.3M by 2032 at 11.67% CAGR

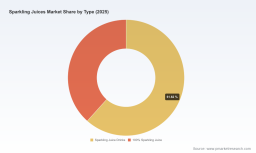
Sparkling Juices Market — Strategic Preview for 2026 Decision‑Makers
As PW Consulting’s Senior Strategy Advisor and Chief Industry Analyst, I present a focused briefing on the Sparkling Juices market that frames the strategic choices facing manufacturers, retailers, ingredient suppliers, and investors in 2026. This is a “trailer” of our full market study: it surfaces the most consequential trends, competitive moves, and tactical recommendations you will need to prioritize in the coming 12–24 months — while reserving the full segmented intelligence for the complete report.
Sparkling Juices Market
Market trajectory at a glance
The sparkling juices market has moved from niche indulgence toward mainstream beverage category over the last half‑decade. On a macro basis, the industry expanded from roughly USD 586.6 million in 2020 to about USD 1,024.0 million in 2025. Under our central forecast, the market is expected to continue growing at a compound annual growth rate (CAGR) of approximately 11.67% through 2032, reaching an estimated USD 2,216.3 million by the end of the forecast period. This rate reflects both premiumization (higher per‑unit price) and widening consumption occasions rather than purely volumetric growth.
Sparkling Juices Market
Two high‑level inferences flow from this trajectory: first, rising consumer interest in health‑forward fizzy beverages translates into durable demand; second, faster growth relative to traditional juice segments invites intensified competition, product innovation, and consolidation — but also leaves high value for those who can capture premium, clean‑label, and functional positioning.
Sparkling Juices Market
What is driving strategic urgency in 2026?
- Structural demand shift: Consumers are treating sparkling juices as multi‑purpose beverages — from refreshment to functional moments to social occasions — elevating the commercial value of distinct flavor and ingredient strategies.
- Cost and compliance pressure: Volatile fresh‑fruit concentrate costs and evolving labeling rules (particularly for sugar and “natural” claims) are squeezing margins and compelling rapid reformulation or value‑engineering choices.
- Channel dynamics: Accelerating omnichannel retailing and direct‑to‑consumer models change assortment economics and promotional strategies.
- Market concentration: The category shows moderate concentration (CR3 ~35%, CR5 ~50%), which means both regional leaders and nimble challengers can find profitable niches but national scale remains an advantage for cost and shelf access.
Industry dynamics: risks and operational levers
Key operating realities that will determine winners in 2026 are not only about brand or flavor — they are about supply chain resilience, claims defensibility, and agile go‑to‑market capability.
- Raw material volatility: Fluctuations in fruit concentrate pricing compress margins and introduce procurement risk. Successful producers are combining hedging, multi‑sourcing, and contract farming to stabilize costs and preserve premium positioning.
- Regulatory and packaging compliance: New labeling requirements for added sugars and natural claims have increased compliance costs across major markets. Brands that proactively align formulations and invest in transparent labeling avoid disruptive reformulation cycles and brand trust erosion.
- Consumer preference shifts: Clean‑label, low‑sugar, and functional claims (e.g., antioxidants, probiotics, adaptogens) are evolving from niche differentiators to table stakes for premium segments.
- Supply chain resilience: Fresh fruit sourcing volatility is forcing changes in production timelines and inventory strategy; players with integrated sourcing or closer relationships with growers have faster response times to demand or crop shocks.
Competitive landscape — what to watch
The category combines legacy juice houses, natural‑brand challengers, and functional‑beverage innovators. Below are concise strategic reads on the core companies profiled in our full study — each illustrates different playbooks you can emulate or defend against.
- S. Martinelli & Co. — A heritage player leveraging provenance: their emphasis on 100% juice sparkling ciders and blends made from U.S. apples with no added sweeteners or preservatives targets consumers who prioritize authenticity and ingredient simplicity. Their leverage is brand heritage and a clean‑label story; their constraint is scale relative to mainstream beverage rivals.
- Spindrift Beverage Co. — Differentiates through product authenticity: real‑squeezed fruit sparkling beverages with minimal ingredients. Spindrift’s model focuses on premium positioning and social media‑native storytelling, enabling rapid trial but requiring disciplined supply chain quality to avoid cost overruns.
- Cawston Press — European innovator marrying pressed‑fruit authenticity with low‑sugar formulations. Their recent product innovations show a pathway for translating clean‑label credibility into wider retail distribution in markets sensitive to sugar reduction.
- Talking Rain Beverage Company (Sparkling Ice) — Competes on zero‑sugar and mass distribution scale. Their capability is leveraging large retail relationships and manufacturing scale; the strategic dilemma is maintaining perceived naturalness while delivering zero‑sugar positioning.
- Welch Foods Inc. — Brings strong legacy juice IP to sparkling formats. Recent limited‑edition launches demonstrate an ability to activate celebratory, seasonal, and retail‑partnered programs that drive short‑term velocity at scale.
- R.W. Knudsen (Knudsen & Sons) — Plays the organic, small‑batch natural juice card. Organic credentials and family‑brand provenance attract a consistent premium cohort; growth hinges on an ability to scale without diluting perceived artisanal value.
- Belvoir Farm — U.K. craft brand that is translating botanical and botanical‑infused flavors into mainstream formats. Their recent school‑friendly launches illustrate how formulation and pack sizing create new everyday occasions.
Recent competitive moves (selection)
- Welch’s launched a limited‑edition Sparkling Blueberry SKU with patriotic packaging for America’s 250th anniversary in May 2026 — a play that blends seasonal marketing with large‑format retail distribution.
- Belvoir Farm introduced a school‑compliant sparkling fruit juice range in January 2026 with a lower sugar profile and convenient 330ml can sizing — an example of product adaptation to regulatory and parental demand.
- Cawston Press rolled out a zero‑sugar sparkling apple & rhubarb drink in early 2026, demonstrating how natural sweeteners and pressed fruit positioning can be combined to meet low‑sugar expectations.
What the full PW Consulting report provides (practical, transaction‑ready content)
- Quantitative market model (2020–2025 historical; 2026–2032 forecast) with scenario sensitivity to raw‑material cost swings and regulatory outcomes.
- Granular segmentation framework (by product type, flavor profile, region, and distribution channel) and demand drivers for each segment — note: the trailer intentionally omits the detailed segment tables to preserve proprietary intelligence.
- Margin and price‑elasticity analysis, including pack size economics and promotional uplift models designed for retailer negotiations.
- Go‑to‑market playbooks: launch checklists, trade promotion templates, DTC optimization blueprints, and retail shelving/assortment strategies calibrated by customer archetype.
- M&A and partnership screening: target scorecards and integration risk matrices for acquisitive growth or supplier consolidation strategies.
- Capability diagnostic and roadmap: a practical 12‑18 month plan to stabilize sourcing, reformulate for labeling compliance, and accelerate premiumization without surrendering margin.
Actionable recommendations for corporate boards and executive teams in 2026
Translate the market opportunity into defendable competitive advantage by focusing on three parallel tracks:
- Protect margin through procurement innovation: Implement layered sourcing (spot + forward contracting + grower partnerships) and invest in supply‑chain analytics to reduce blindspots. Scenario‑test your P&L at +/- 20% concentrate price moves.
- Prioritize claims defensibility and regulatory foresight: Align formulations with the strictest labeling standards in your top three markets today — this reduces rework and preserves shelf continuity. Where feasible, invest in transparent provenance tracking (batch‑level traceability) to reinforce premium claims.
- Segment your innovation roadmap: Reserve premium SKUs for high‑margin channels and test functional or low‑sugar variants via controlled DTC or regional rollouts. Use limited editions and seasonal programs to accelerate trial without long‑term SKU complexity.
- Channel economics first: Reassess promotional budgets with SKU‑level ROI. Negotiate buy‑ins with retailers on merchandising rather than solely price promotions; focus on featured seasonal blocks and cross‑category co‑promotions (e.g., mixers, non‑alcoholic celebration packs).
- Prepare for consolidation and partnerships: Given the category’s moderate concentration and growth, create an M&A scorecard for adjacent entrants and claim‑adjacent ingredient suppliers; consider minority investments in high‑growth challengers to secure innovation pipelines.
Why this matters now
2026 is a decision inflection point: the market is large enough to justify scale investments but still young enough that positioning and supply‑chain choices will determine who captures the majority of future value. Missteps in formulation, procurement, or channel strategy are costly to reverse; conversely, well‑executed premium positioning, backed by procurement resilience and regulatory foresight, can lock in outsized returns as the market roughly doubles over the next six years.
Next steps — how PW Consulting can accelerate your 2026 plan
- Executive briefing: 90‑minute deep dive to align leadership on scenario priorities and a 90‑day operational plan.
- Rapid procurement and formulation sprint: 6‑week program to stabilize input costs and rebaseline SKU economics under current labeling scenarios.
- M&A readiness package: diligence templates, integration playbooks, and a shortlist of screened targets aligned to your strategic ambition.
For clients and decision‑makers who require the full, actionable intelligence — including the detailed segment tables, channel revenue splits, and SKU‑level economics that are intentionally withheld in this preview — PW Consulting’s full Sparkling Juices Market report provides the depth and models you need to execute with confidence in 2026. Contact PW Consulting or visit our report page to access the comprehensive dataset, commercial playbooks, and modeled scenarios that inform board‑level approvals and near‑term operational moves.
For detailed analysis of this topic, please visit the official page: Sparkling Juices Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com