

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: 10-Deacetylbaccatin III Market Set to Reach USD 236M by 2032 (5.5% CAGR)

10-Deacetylbaccatin III Market: Strategic Intelligence for 2026 Decision-Making
As the pharmaceutical value chain recalibrates around biologics, semi-synthetic APIs and resilient supply networks, 10-Deacetylbaccatin III (10-DAB III) has re-emerged as a strategic raw material. PW Consulting’s latest market study—anchored on 2025 as the base year and projecting through 2032—translates historical patterns (2020–2025) and a steady 5.5% CAGR into practical guidance for corporate leaders preparing 2026 action plans. This introduction outlines the macro trajectory, competitive dynamics, and the operational levers that will matter most next year; it intentionally withholds proprietary sub-segment tables and granular regional splits to encourage direct access to the full intelligence set.
10-Deacetylbaccatin III Market
Executive snapshot: Growth with defined inflection points
The market for 10-DAB III has grown from approximately USD 120 million in 2020 to roughly USD 161.5 million in 2025, reflecting a steady recovery and broadening end-market activity. Our forecast, driven by supply-side consolidation, incremental capacity additions in Asia, and sustained demand from paclitaxel/docetaxel semi-synthesis and allied research applications, anticipates continued expansion to an estimated USD 236.0 million by 2032 on a 5.5% compound annual growth rate (CAGR).
10-Deacetylbaccatin III Market
What this means for 2026 planning is straightforward: demand will be predictable but competitive pressure on cost and quality will intensify. Firms that move now to shore up validated supply, diversify supplier footprints, and de-risk regulatory pathways will convert growth into durable margins.
10-Deacetylbaccatin III Market
Why this report matters for 2026 corporate strategy
- Procurement certainty: The study maps validated supplier capabilities, regulatory filings, and production footprints, enabling procurement teams to reduce lead-time risk and negotiate long-term offtake arrangements with traceable quality commitments.
- Manufacturing & CAPEX planning: We translate demand curves into capacity stress-tests and build/no-build scenarios—critical inputs for 2026 CAPEX cycles where long-lead equipment and facility certifications can determine market share.
- Regulatory & quality alignment: Our analysis highlights the regulatory dossiers and quality certifications that accelerate customers’ formulation timelines—information that informs investment in dossier filings or strategic partnerships.
- Portfolio prioritization: For pharma and chemical players evaluating vertical integration or outsourcing, the report provides decision frameworks to assess ROI across integrated supply, toll manufacturing, and pure distribution models.
Market trajectory and what the numbers reveal
The past half-decade shows an industry that is neither nascent nor saturated. From a 2020 baseline near USD 120 million to USD 161.5 million in 2025, the market exhibits steady, resilient demand. The forecast to 2032 implies incremental acceleration in absolute terms as oncology volumes stabilize and manufacturers optimize semi-synthetic routes. The 5.5% CAGR encapsulates a mix of mature demand from pharmaceutical manufacturing, periodic step-ups from API supply reshoring, and steady consumption by R&D institutions testing next-generation taxane analogues.
Importantly, concentration metrics indicate a fragmented supplier landscape—our CR3 and CR5 estimates suggest low market concentration. In practice, that means buyers have negotiation room but should be wary: fragmentation coexists with pockets of technical specialization and regulatory advantage that can skew sourcing economics for specific quality grades or documented supply histories.
Demand drivers and supply-side dynamics
- End-market stability: Oncology treatment volumes underpin baseline demand; progress in combination therapies and reformulated taxanes adds predictable uplift.
- Quality differentiation: Purity grades and process control drive premium pricing for commercial intermediates intended for sterile API synthesis versus research standards.
- Regulatory barriers to entry: Active master files, GMP certifications, and region-specific dossiers raise switching costs for buyers and create strategic advantage for suppliers that maintain up-to-date filings.
- Geopolitical & logistics risk: Supply resilience and multi-jurisdictional manufacturing footprints will be decisive as companies reassess single-source dependencies.
Competitive landscape: who matters and why
The market is populated by a mix of European specialty intermediates firms, North American botanical extractors, and an expanding cohort of Asia-based GMP manufacturers. The companies identified in our study exhibit distinct strategic postures—some compete on dossier-backed, high-purity intermediates for regulated markets; others prioritize cost-competitive supply to large formulators. Key players include:
- Indena S.p.A. (Milan, Italy) — A vertically integrated player specializing in botanical intermediates and API precursors. Indena’s established filings and commercial offerings position it as a preferred partner for customers needing dossier-backed materials for docetaxel production.
- Phyton Biotech LLC (North Carolina, USA) — A US-based supplier with a reputation for high-quality, plant-derived intermediates. Its focus on validated supply chains and service to western formulators makes it a strategic fit for buyers prioritizing regulatory traceability.
- Regional Asian manufacturers (e.g., firms in China, Taiwan, Korea, India) — Several GMP-compliant producers offer scale and cost leadership; their competitive advantage lies in capacity, local raw material access, and increasingly, improved process control. Some of these companies hold international filings that facilitate exports to regulated markets.
- Reference-standard specialists — Providers of certified reference materials support analytical validation and R&D, creating an adjacent niche that supports market credibility and scientific reproducibility.
Strategically, buyers should evaluate suppliers not only on price but on dossiers, batch history transparency, capacity flexibility, and the ability to deliver documented continuity of supply under regulatory scrutiny. For suppliers, the winning moves include investing in active master files, securing third-party certifications, and offering tiered product portfolios (research grade to high-purity commercial intermediates).
Risks & inflection points to monitor in 2026
- Regulatory shifts: Updates to GMP expectations, export controls, or changes in dossier requirements can create sudden sourcing friction. Companies should map regulatory dependencies across markets.
- Feedstock volatility: Botanical sourcing is vulnerable to weather and harvest cycles; vertical integration or diversified botanical sourcing strategies will mitigate that exposure.
- Capacity mismatches: As semi-synthetic taxane demand grows, incremental capacity delivered without commensurate quality control will compress margins and raise recall risk.
- Intellectual property & process innovation: Process intensification or biocatalytic routes that reduce reliance on plant-derived intermediates could be disruptive; monitoring R&D pipelines is essential.
What PW Consulting’s full report delivers (operationally actionable)
Our comprehensive study translates market analysis into tools that decision-makers can operationalize in 2026. Highlights include:
- Validated market sizing and a scenario-based demand model calibrated to historical 2020–2025 performance and our 2026–2032 forecast.
- A supplier due-diligence framework that maps certifications, dossier statuses, capacity logistics and quality controls—structured to accelerate supplier selection and contract negotiations.
- Commercial playbooks for buyers and suppliers: procurement tactics, pricing levers, and collaboration models (toll manufacturing, strategic offtake, co-development) tailored to different company profiles.
- Risk matrices and contingency plans for regulatory, supply, and feedstock shocks, with stress-tested mitigation steps and decision gates for CAPEX commitments.
- Executive dashboards, KPIs and negotiation checklists to shorten procurement cycles and reduce exposure to single-source dependencies.
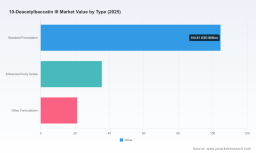
Note: the full report contains granular subsegment analyses (by region, type, and application) and supplier scorecards. In keeping with the “prequel” principle, we have intentionally omitted those proprietary tables from this introduction—these are available in the complete package to authorized subscribers.
How to use these insights to shape 2026 priorities
- Procurement & sourcing: Convert forecast clarity into binding multi-year supply agreements with staggered quantity flexibility and quality acceptance criteria to lock favorable economics while preserving operational agility.
- Manufacturing strategy: Prioritize investments in certificate maintenance and process validation over marginal capacity expansion unless backed by secured offtake commitments.
- M&A & partnerships: Use supplier scorecards to identify bolt-on targets for vertical integration or to source strategic partnerships that accelerate dossier filings and regional market access.
- R&D alignment: Re-weight discovery pipelines and formulation timelines to reflect realistic lead times for high-purity intermediates and to exploit new formulations that reduce API cost per treatment.
Conclusion — positioning for a controlled growth phase
The 10-DAB III market is entering a controlled growth phase: predictable, technically demanding, and strategically consequential for firms engaged in taxane synthesis and related therapeutic research. The story for 2026 is not one of runaway demand, but of strategic position-taking—companies that shore up validated supply, formalize quality and regulatory dossiers, and adopt diversified sourcing will capture disproportionate value as the market scales from its 2025 base toward the 2032 projection.
Access to the full PW Consulting report will provide the confidential subsegment matrices, supplier benchmarking and executable negotiation materials you need to convert these strategic imperatives into immediate actions in 2026. Contact PW Consulting to obtain the complete market model and supplier scorecards.
For detailed analysis of this topic, please visit the official page: 10-Deacetylbaccatin III Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com