

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Artificial Pancreas Market to Hit USD 316.95M by 2032, 7.12% CAGR

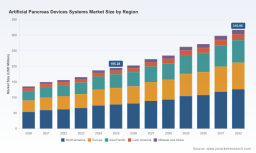
Artificial Pancreas Device Systems Market — Strategic Preview for 2026 Decision-Makers
As PW Consulting’s lead industry analyst, I present a concise strategic preview of the Artificial Pancreas Device Systems market intended to inform executive decisions in 2026. This briefing synthesizes our market-sizing, competitive tracking, regulatory mapping, and scenario modeling into an actionable narrative — enough to identify opportunity vectors and risk levers, while preserving the granular segmentation and proprietary model outcomes for subscribers of the full report.
Artificial Pancreas Devices Systems Market
Market snapshot — trajectory and what it means
The artificial pancreas device systems sector is in a steady growth phase. Our base-year framework (2025) and historical tracking (2020–2025) show a clear expansion from the market’s early scale toward broader commercial adoption. Using our conservative forecasting assumptions and validated uptake models, the market is expected to grow at roughly 7.12% CAGR across the 2026–2032 forecast horizon. In dollar terms, the market moved materially between 2020 and 2025 and the model projects continued expansion through 2032 as algorithmic automation, sensor accuracy, and payer recognition converge to reduce barriers to use.
Artificial Pancreas Devices Systems Market
What this means for executives in 2026: the opportunity is established but not yet mature. The next three years will determine whether suppliers consolidate leadership through product breadth and reimbursement depth, or whether newer entrants capture specialist niches by offering differentiated clinical outcomes, pricing models, or integration strategies with third‑party sensors and telehealth platforms.
Artificial Pancreas Devices Systems Market
Why this preview matters for 2026 corporate strategy
- Timing strategic pivots: The market’s near‑term growth window means timing matters. Decisions on clinical trial investments, regulatory filings, and reimbursement negotiations initiated in 2026 will often not yield commercial returns until the late 2020s — yet the competitive landscape is shifting in ways that make early-mover advantages durable (e.g., algorithm IP, sensor partnerships).
- Resource allocation trade-offs: Firms must prioritize between expanding device portfolios, accelerating algorithm development, or deepening payer engagement. Our scenario tools show different ROI curves depending on whether a company emphasizes clinical superiority, unit economics, or channel expansion.
- M&A and partnership calculus: With a mid‑market concentration among top firms, strategic M&A can be an efficient route to scale. However, the best acquisition targets are frequently those that close specific capability gaps (sensor compatibility, SaaS analytics, or unique adjudication evidence for payers).
Competitive landscape — how to read the players
The competitive field is best viewed through capability clusters rather than simple market share tables. Four archetypes dominate current headlines:
- Established device platform leaders — incumbent medical device firms leveraging integrated hardware and clinical channels to defend and extend adoption of automated insulin delivery systems.
- Modular/patch innovators — companies offering tubeless or discrete delivery that emphasize user convenience and adherence, often paired with algorithm upgrades as a differentiator.
- Algorithm-first challengers — teams with advanced closed‑loop control IP or machine-learning enabled personalization who pursue integrations with multiple delivery and sensor partners.
- Sensor and ecosystem integrators — firms that position themselves as the connective tissue across devices, apps, and payer systems, enabling flexible combinations of best‑of‑breed components.
Key players tracked in our research — and the strategic signals they are sending — include:
- Medtronic: Continues to advance its integrated platform approach and to defend installed base economics through iterative system upgrades and provider relationships. Their focus on end‑to‑end solutions keeps them central to hospital and specialty clinic contracts.
- Insulet Corporation (Omnipod): Pursues a modular, patch-based convenience proposition with aggressive algorithm enhancements and user‑centric software updates — a clear strategy to broaden indications and payer acceptance.
- Tandem Diabetes Care: Demonstrates the value of rapid regulatory execution and algorithm evolution; recent clearances and commercial rollouts broaden addressable populations and signal a scale-up play.
- Beta Bionics: Embodies the algorithm-first challenger model, emphasizing openness to sensor partnerships and a clinical narrative around simplified user experience.
Our competitive scorecards go beyond product features to quantify route-to-market strength, clinical evidence velocity, payer engagement, and IP defensibility. These multidimensional assessments allow boards and corporate development teams to prioritize targets and counter‑moves in 2026.
Regulatory and reimbursement environment — the operational backdrop
Policy and coverage developments are actively shaping adoption economics. Notable dynamics we incorporate in our models include:
- Clear regulatory expectations that automated insulin delivery systems will generally follow 510(k)-style pathways in key jurisdictions, with added emphasis on software lifecycle management and postmarket surveillance.
- Active payer coding and coverage updates that are beginning to recognize bundled device+sensor+software offerings, which materially impacts unit reimbursement and total cost of care discussions.
- Event-level regulatory advisories and product corrections that can temporarily disrupt adoption momentum — a critical operational risk for manufacturers in 2026.
Implication for 2026 planning: regulatory strategy must be treated as a commercial lever, not merely a compliance checkbox. Investments in design controls, real‑world evidence generation, and payer-facing health economics dossiers will directly influence market access outcomes.
Recent clinical and commercial developments — directional signals
Over the past 18 months, notable product clearances, product integrations, and availability announcements have altered competitive dynamics. Several firms have expanded indications and compatibility with leading glucose sensors; others have sought broader type‑2 diabetes approvals — moves that open new patient cohorts and change go‑to‑market priorities. At the same time, safety notices and device corrections underscore the importance of robust manufacturing and quality systems as competitive differentiators.
What the full report contains (practical, operational, proprietary)
Our full PW Consulting market study delivers hands‑on deliverables for 2026 decision-making, including:
- Detailed market sizing and demand models calibrated to historical adoption (2020–2025) and multiple forecast scenarios through 2032.
- Granular segmentation (type, region, application) and company-level revenue benchmarking — note: those tables and line-item forecasts are intentionally reserved for subscribers of the full report.
- Competitive dossiers with go-to-market maps, patent landscape snapshots, and four‑quarter innovation roadmaps for each major vendor.
- Reimbursement and regulatory playbooks: coding impacts, payer engagement templates, and precedent-based negotiation strategies for managed care and national health systems.
- Commercial sensitivity analyses and stress tests — supply chain disruption scenarios, price compression and margin models, and reimbursement pullback simulations.
- Actionable one‑page playbooks tailored for product strategy, M&A diligence, and market entry that your executive team can operationalize immediately.
We intentionally withhold granular regional and application split tables in this preview to preserve the transformational value of the full deliverables. Those datasets, together with our interactive financial model, are the assets that materially shorten time-to-precision for commercial planning.
Strategic recommendations for 2026 (practical, prioritized)
- Build a reimbursement war‑room: Assemble clinical, health economics, and payer affairs resources now. Winning coverage decisions in 2026 requires coordinated evidence and commercial negotiation playbooks developed in parallel with regulatory filings.
- Prioritize sensor interoperability: Investments to certify compatibility with leading continuous glucose monitors unlock distribution partnerships and reduce switching costs for end users.
- Consider bolt‑on M&A where capability gaps exist: Target smaller firms that provide narrowly scoped algorithm enhancements, telehealth integration, or proven payer evidence packages rather than attempting to build all capabilities in-house.
- Operationalize quality and postmarket surveillance: Quality incidents materially affect adoption. Strengthen manufacturing oversight, supply diversification, and adverse event management to protect momentum.
- Design clinical programs for wider indications: Evidence supporting use in broader diabetes populations (e.g., selected type‑2 cohorts) can materially expand addressable markets and improve payer value propositions.
How PW Consulting can accelerate your 2026 agenda
Our advisory engagements are structured to compress the time between insight and execution. For 2026 we offer modular support: quick‑turn market opportunity assessments, bespoke reimbursement dossiers, acquisition target screening with three‑level due diligence, and implementation support for regulatory submissions and commercialization plans. The full report provides the datasets and modeling engines required to run these interventions with precision.
Next steps
If your team is prioritizing strategic moves in 2026 — whether accelerating product launches, pursuing partnerships, or evaluating acquisition targets — our full Artificial Pancreas Device Systems market study is designed as an operational playbook. For access to the report’s complete segmentation tables, company revenue benchmarks, and interactive forecast model, visit our report page or contact PW Consulting to schedule a briefing and model walkthrough.
In an industry where clinical credibility, payer recognition, and operational rigor determine winners, 2026 is the year to convert market momentum into lasting leadership. This preview highlights the critical constants and decision levers; our full deliverables provide the granular inputs you’ll need to act with speed and confidence.
For detailed analysis of this topic, please visit the official page: Artificial Pancreas Devices Systems Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com