

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: MIM Furnace Market Poised for 6.7% CAGR to 2032

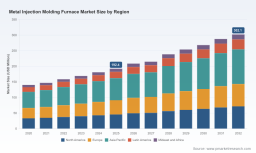
Metal Injection Molding Furnace Market — Strategic Outlook for 2026 Decision-Makers
As PW Consulting’s senior industry analyst, I present a concise strategic primer that demonstrates why the Metal Injection Molding (MIM) furnace market deserves boardroom attention in 2026. This market is no longer a niche vertical engineering exercise; it is a capital-intensive component of broader electrification, medical miniaturization, and aerospace weight-reduction plays. Our full Metal Injection Molding Furnace Market study (base year 2025, forecast 2026–2032) synthesizes proprietary primary interviews, equipment-level technical benchmarking, and financial modelling to convert industry complexity into decision-ready intelligence. Below I summarise the strategic value of that research for corporate planning while deliberately withholding granular segment datapoints — a deliberate “trailer” to prompt access to the full report for transactional, competitive and investment use.
Metal Injection Molding Furnace Market
Why this market matters to 2026 planning
The furnace installed base and replacement cycle dynamics mean that capital allocation decisions made in 2026 will determine manufacturing cost curves and part capabilities through the end of the decade. After five years of steady expansion, total industry revenues grew from approximately USD 140 million in 2020 to roughly USD 192 million in 2025. Our forecast, anchored on a 6.7% compound annual growth rate (CAGR) for the 2026–2032 interval, projects continued expansion through 2032 — driven by higher-value alloys, tighter tolerances for medical & aerospace parts, and the growing adoption of continuous and vacuum processing solutions.
Metal Injection Molding Furnace Market
Two planning horizons should shape executive thinking in 2026:
Metal Injection Molding Furnace Market
- Short-term (12–24 months): secure supply of furnace platforms and consumables while insulating manufacturing from tariff and defence-procurement policy shocks;
- Medium-term (3–6 years): deploy equipment that enables alloy diversification (e.g., titanium and high-strength stainless grades) and lowers total cost of ownership via energy efficiency and automation.
Key market characteristics that alter strategic choices
Market structure matters. Despite rising volumes, concentration metrics indicate a fragmented supply landscape: the top three and top five vendors together account for a minority share of global revenues, underlining both opportunity and procurement complexity for OEMs and contract manufacturers. Fragmentation benefits buyers in the short term (competitive pricing, specialized suppliers) but complicates standardization, spare-parts availability, and global service coverage — critical considerations when sourcing equipment intended to run for a decade.
Technology variety is another defining trait. The market spans batch, continuous, catalytic/thermal debinding solutions, and vacuum sintering systems capable of temperatures approaching 1,600°C. Equipment design decisions — atmosphere control, part-throughput, load geometry and integration with debinding lines — directly influence production yield and metallurgical outcomes. Selecting a suboptimal furnace architecture is not merely an operational misstep; it translates into scrap, rework and certification delays in regulated end-markets.
What our report delivers — practical contents for 2026 execution
The full PW Consulting report is built to be operationally prescriptive rather than merely descriptive. Highlights include:
- Market sizing and forecast (2020–2032) with sensitivity scenarios tied to alloy adoption rates and aerospace/medical qualification timelines;
- Procurement playbook and TCO models for furnace investments — from capital cost to energy, consumables, service and throughput-adjusted unit cost;
- Supplier scorecards and selection matrices that map technical capability (e.g., catalytic debinding, hydrogen atmosphere handling, vacuum integrity) against commercial attributes (lead times, global service footprint, customization capability);
- Plant-level integration guidance: recommended floor layouts for combined debind/sinter lines, recommended utility profiles, and retrofit pathways to improve energy efficiency;
- Regulatory and compliance checklist, including readiness for evolving standards and procurement clauses that affect defence and export-controlled supply chains;
- Investment cases and scenario-styled business cases for three archetypal buyers — captive OEMs, contract manufacturers, and specialist MIM producers — each with CapEx payback periods and sensitivity to throughput and alloy mix;
- Risk matrix and mitigation playbook covering tariffs, single-supplier exposure, spare-part lead times, and materials-standard shifts;
- Executive dashboards and bespoke datasets available for license to support board-level presentations and funding decisions.
Competitive landscape — who matters and why
The supplier set remains diverse, with distinct technology specialisms. Understanding vendor strengths is necessary to match furnace capability to product and market needs. Key manufacturers covered in the study include:
- Elnik Systems, LLC (Pineville, NC, USA) — recognized for integrated debinding and sintering platforms, including one-step debind/sinter cycles; appeals to producers seeking compact lines and simplified process flows.
- Nabertherm GmbH (Lilienthal, Germany) — offers paired debinding and sintering series with both thermal and catalytic options and matched footprint planning, supporting seamless transfer and process repeatability in higher mix environments.
- CARBOLITE GERO (Germany) — positions with application-specific furnaces for catalytic debinding and staged sintering, attractive to customers emphasizing materials qualification and repeatable thermal profiles.
- CM Furnaces Inc. (Bloomfield, NJ, USA) — notable for continuous series and batch platforms optimized for hydrogen atmospheres; suited to high-throughput MIM producers seeking continuous-line economics.
- TAV Vacuum Furnaces S.p.A. (Caravaggio, Italy) — vacuum sintering systems capable of high temperatures, with chamber material choices (e.g., graphite vs. all-metal) that matter for specific alloy processing.
- Seco/Warwick Group (Poland) — delivers customizable vacuum solutions and has demonstrated market traction in aerospace through recent bespoke deliveries, underlining its ability to support qualification-driven, high-value production ramps.
Each of these suppliers presents a different trade-off between standardisation and custom capability, cost and serviceability, which is why our supplier scorecards — complete with technical test results and field-service metrics — are a cornerstone of the report.
Recent industry developments that change the playbook
Three developments in 2025–2026 demand recalibration of purchasing and sourcing strategies:
- Standards update — The Metal Powder Industries Federation released the 2025 edition of MPIF Standard 35, expanding material standards to encompass additional titanium and stainless grades. This materially affects qualification plans, weld/sinter parameters and process windows for MIM parts in regulated end-markets.
- Strategic equipment deliveries — Major vendors have executed bespoke deliveries for aerospace and high-reliability segments. Such deliveries signal vendor willingness to provide bespoke engineering support — an important procurement negotiation lever, but also a potential gateway to vendor lock-in if long-term support terms are not secured.
- Industry convenings — Technical guides and conferences scheduled through 2026 (e.g., Euro PM2026) are focal points for alloy and process innovations; attendance and engagement at these events are high-value for R&D and sourcing teams seeking to accelerate qualification timelines.
Regulatory & trade considerations
Policy dynamics are non-trivial. The interplay of updated material standards, anticipated tariff implications (including Section 301-era sensitivities) and Department of Defense contract clauses requires integrated legal-operations planning. For commercial teams this means factoring potential indirect costs — certification delays, requalification runs, and alternate sourcing premiums — into 2026 capital approvals.
Recommendations for executives in 2026
Translate insights into action across four pragmatic channels:
- Procurement discipline: adopt multi-vendor shortlists and include life-cycle service guarantees and spare-part SLAs in procurement contracts to limit single-supplier exposure.
- Investment prioritisation: prioritise equipment that supports the highest-probability alloy and qualification pathways for your firm; use TCO models rather than lowest-CAPEX selection logic.
- Regulatory readiness: incorporate the 2025 MPIF updates into qualification timelines now; accelerate material compatibility tests where titanium and high-performance stainlesses are in your roadmap.
- Operational resilience: invest in modular line architectures that enable staged capacity additions and retrofit for energy improvements while minimising downtime.
Who should read the full PW Consulting report
Our study is intended for C-suite and strategy teams at OEMs, procurement and plant operations leaders at contract manufacturers, corporate development teams evaluating M&A or JV options, and private-equity investors seeking equipment-level diligence. For these stakeholders, the report converts technical nuance into capital allocation, sourcing and product strategy choices — delivering quantifiable payback scenarios tied to equipment selection.
Closing — the value proposition for 2026
Decisions taken in 2026 about furnace selection, supplier partnerships and qualification sequencing will lock in manufacturing flexibility and cost structures for years. The MIM furnace market is expanding from roughly USD 192 million in 2025 and, with a projected 6.7% CAGR across 2026–2032, into the high hundreds by the end of the decade. Yet growth alone does not equal certainty: regulatory updates, tariff environment, and the fragmented supplier base introduce execution risk that must be actively managed.
PW Consulting’s full Metal Injection Molding Furnace Market study provides the tactical playbooks, vendor scorecards and financial models needed to convert that market growth into competitive advantage. This article teases our findings and strategic recommendations; the full report contains the detailed segment intelligence, scorecards, and model inputs required to execute procurement and investment decisions with confidence. Reach out to access the complete dataset and bespoke advisory packages that map these insights to your organisation’s 2026 imperatives.
For detailed analysis of this topic, please visit the official page: Metal Injection Molding Furnace Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com