

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
Vacuum Suction Cups Market to Reach USD 253.5 Million by 2032, Driven by 6.5% CAGR

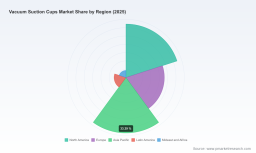
Vacuum Suction Cups Market — Strategic Outlook for 2026 Decision‑Makers
As PW Consulting’s Senior Strategy Advisor and Head Industry Analyst, I present a condensed strategic briefing on our new Vacuum Suction Cups Market study — a practical, decision‑centric synthesis designed to inform procurement, product, and M&A choices across 2026. The study uses 2025 as the base year, reviews the 2020–2025 historical window, and projects through 2026–2032 under a 6.5% compound annual growth assumption. This brief demonstrates the study’s utility for executive teams while intentionally withholding detailed segmentation findings to preserve our full report’s commercial value.
Vacuum Suction Cups Market
Why this study matters in 2026
-
Automation acceleration: As factories continue to automate pick‑and‑place, packaging, and lifting tasks, demand characteristics shift from one‑size‑fits‑all suction cups toward differentiated product families tailored to surface, throughput, and cleanliness requirements.
Vacuum Suction Cups Market -
Electronics and battery handling: The rise of sensitive components and battery cell manufacturing makes electrostatic discharge (ESD) protection and pass‑marking performance prime procurement criteria for 2026 purchasing cycles.
Vacuum Suction Cups Market -
Hygiene and regulatory pressure: Food, meat and dairy packaging lines increasingly demand materials and designs that meet strict hygienic standards — creating procurement, testing, and supplier qualification challenges for engineering and compliance teams.
-
Supply‑chain resilience and raw materials: Volatility in elastomers and specialty polymers, plus sustainability expectations, require new sourcing strategies and product‑level substitutions that preserve performance while controlling cost.
What the report delivers — practical, executable outputs
-
Transparent market sizing and forecasting framework (historical consistency checks plus probabilistic scenario models for 2026–2032).
-
Actionable demand maps by application class and end‑market (note: detailed splits and tables are available in the full report).
-
Supply‑chain heat maps identifying critical raw inputs, single‑source risks, and alternative material pathways.
-
Regulatory and standards matrix (food‑grade, ESD, industry‑specific hygiene) with supplier compliance checklists and audit templates.
-
Product and technology roadmap: material innovations, bellows versus flat geometries, modular connectors, and the integration of sensors for condition monitoring.
-
Competitive benchmarking: qualitative and quantitative profiling of leading manufacturers (R&D strengths, channel models, aftermarket services, and selected capability gaps).
-
M&A and partnership playbook: target screening criteria, valuation sensitivities, and integration checklists for bolt‑on and capability plays.
-
Commercial toolkits: procurement term sheets, supplier scorecards, technical acceptance protocols, pilot evaluation templates, and a pricing‑sensitivity model you can customize to your cost base.
-
Appendices with engineering aids: recommended test procedures, inspection criteria, and sample bill‑of‑materials templates for OEM integrations.
Market dynamics: what to watch in 2026
The market’s trajectory through 2026 is driven by three intersecting dynamics. First, product design is polarizing: established designs (flat, bellows, oval) remain necessary, but specialized materials and micro‑geometries are becoming the differentiator for high‑value applications. Second, material science is a competitive front: silicone and nitrile derivatives are central to many specifications, while novel formulations that reduce marks, improve ESD shielding, or meet food‑safety standards are moving from R&D into commercial releases. Third, channel and service economics are evolving — OEMs, systems integrators, and aftermarket suppliers are competing not only on unit price but on integration speed, qualification support, and lifecycle service.
Recent industry moves underscore these trends. Leading suppliers have introduced new compounds and families explicitly aimed at sensitive electronics, heavy flat surfaces, and battery components. These product introductions are not cosmetic — they change qualification timelines, reduce rework in high‑value assembly lines, and raise the technical bar for second‑tier suppliers.
Competitive landscape — strategic takeaways
-
Schmalz (Germany): A clear innovation leader in specialty materials and application‑specific forms. Recent introductions focused on ESD‑protective compounds demonstrate a strategy of competing on material IP and quality claims that reduce marks on sensitive substrates.
-
Piab (Sweden): Product family expansion targeting demanding surface handling and miniaturized ESD needs positions Piab to capture advanced electronics and battery cell handling segments. Their launches emphasize surface adaptability and miniaturization, signaling an offensive aimed at higher‑margin niches.
-
Festo (Germany): Strength lies in modular integration and systems compatibility, making them a preferred partner for automation vendors and OEMs that require plug‑and‑play vacuum solutions integrated into broader motion systems.
-
SMC Corporation (Japan): Scale and range give SMC an advantage in broad industrial accounts requiring high availability. Their portfolio breadth supports large OEMs with standardized platforms and high‑volume replacement parts strategies.
-
Coval (France): Deep catalogue breadth and custom‑reference capability enable Coval to serve unique handling challenges and projects that require fast specialization without long development cycles.
-
Vacuforce, ANVER, Sommer‑Technik, VMECA: These regional and niche players compete on specialized applications, responsiveness, or price competitiveness. Their strategies typically favor local service, configurable options, and targeted OEM partnerships.
Strategically, the market is neither a winner‑takes‑all oligopoly nor fully fragmented chaos. Top vendors command meaningful presence, but there is substantial space for specialists and challengers who bring material innovations, systems‑integration capabilities, or superior after‑sales services.
Implications for corporate strategy in 2026
-
Product strategy: Prioritize R&D that addresses ESD performance and hygienic compliance. Shorten qualification cycles by investing in joint validation pilots with key OEM customers.
-
Supply‑chain strategy: Implement dual‑sourcing for critical elastomers and build flexible substitution clauses into supplier contracts. Use hedging and inventory buffers selectively for high‑risk inputs.
-
Commercial strategy: Differentiate through bundled services — technical onboarding, digital tooling for selection, and long‑term spare‑parts agreements. For OEMs, embed suction components into bundled automation offers to capture system‑level margin.
-
M&A and partnerships: Target bolt‑ons that add material IP, rapid prototyping, or localized production footprints in key assembly hubs. For buyers, prioritize targets with established qualification records in regulated industries.
-
Operational readiness: Build internal test labs, formalize technical acceptance procedures, and codify product interchangeability rules to reduce line stoppages and expedite supplier swaps.
Scenario framing and risk management
Our baseline forecast — incorporated in the detailed report — assumes steady global demand expansion under current automation trajectories. Upside arises if accelerated EV and battery manufacturing scales faster than expected or if new hygiene regulations push faster refresh cycles. Downside risks center on raw material shocks, trade restrictions, or rapid substitution by radically different gripping technologies. A pragmatic risk playbook in 2026 includes strategic inventory, tiered supplier contracts, and pre‑qualified substitution families that meet core performance and regulatory criteria.
Why PW Consulting’s study is uniquely actionable
-
We combine a reproducible forecasting model with primary interviews across OEMs, integrators, and materials suppliers to deliver both macro foresight and micro operational guidance.
-
The deliverable includes ready‑to‑use commercial templates, supplier scorecards, and scenario models that translate directly into boardroom decisions and procurement RFPs.
-
Critically, the study balances openness and discretion: it shows the strategic contours and near‑term levers executives must act on, while preserving detailed segment tables and account‑level intelligence for licensed clients.
In practice, the value of the full report for 2026 decision‑makers lies in its ability to shorten decision cycles: it replaces guesswork about material choices, supplier risk, and product positioning with tested templates and supplier diagnostics that support rapid pilots and confident sourcing moves.
Next steps
If your team is preparing capital allocations, supplier selection, or product roadmaps for 2026, the full PW Consulting Vacuum Suction Cups Market report will supply the quantitative detail and supplier‑level intelligence you need to act. Our analysts are available to walk through scenario results, run a tailored supplier‑risk simulation for your bill of materials, or co‑design a pilot qualification program aligned with your engineering cadence.
Contact PW Consulting to schedule a briefing and access the full dataset and appendices. The summary above signals the strategic nuances that matter — the full study provides the granular evidence base to convert those nuances into operational advantage.
For detailed analysis of this topic, please visit the official page: Vacuum Suction Cups Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com