

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Global Beer Market Reaches USD 860 Billion in 2025

Beer Market 2026 Strategic Preview — Actionable Intelligence for Executive Decision-Making
As PW Consulting’s Senior Strategy Advisor and Chief Industry Analyst, I present a concise strategic preview of our Beer Market study designed to inform board-level decisions and commercial plans across 2026. This preview highlights the thesis, the macro trends that matter, competitive impulses, and the tactical playbooks we recommend for near-term execution. The full report contains the underlying models, granular segment and regional splits, and executable growth roadmaps; this article intentionally surfaces high-value insight while preserving the detailed segmentation to drive you to the complete intelligence package.
Beer Market
Market trajectory and what it implies for 2026
Between 2020 and 2025 the global beer market expanded from roughly USD 724.1 billion to USD 860.0 billion, driven by a mix of volume recovery and value migration. Our base-year analysis (2025) and forecast through 2032 underpin a steady compound annual growth rate of 4.91%. Under our central case, the market is projected to reach approximately USD 920.4 billion in 2026 and climb toward about USD 1,170.3 billion by 2032.
Beer Market
What does this mean for corporate leaders planning in 2026? First, the sector is growing at a pace that supports both organic investment and selective M&A; it is large enough for scale plays to be rewarded and dynamic enough for agile, niche entrants to carve durable positions. Second, the pace of value creation will be increasingly driven by premiumization, non-alcoholic alternatives, and packaging and supply-chain cost management rather than by broad-based volume growth alone.
Beer Market
Why this report is strategically valuable for 2026 planning
- Prioritized investment guidance: Our forecast and scenario work help you test capex choices against plausible demand pathways and cost shocks.
- Margin resilience levers: We map where cost pressure is most acute (raw materials, packaging, tariffs) and quantify mitigation options—procurement hedging, packaging conversion, and SKU rationalization.
- Channel and portfolio playbooks: Actionable strategies for optimizing on‑trade vs off‑trade mix, accelerating premium and non‑alcoholic SKUs, and reconfiguring distribution footprints.
- M&A and competitive positioning: A heatmap that aligns acquisition targets, integration synergies, and anti‑trust exposure to maximize return on deployed capital.
- Rapid-deployment tools: Excel-based models, scenario dashboards, and practical checklists that enable 90‑day sprint implementation.
Competitive landscape — concentration and strategic implications
The market exhibits a moderate-to-high concentration profile, with the top three players accounting for roughly 46% of market share and the top five about 58%. That concentration produces both stability and friction: leading players can leverage distribution scale and procurement leverage, while mid‑sized and craft players benefit from agility, route-to-market creativity, and localized brand equity.
Key incumbents we analyzed include global brewers who are shaping the market’s topology and signaling where competition and opportunity will be fiercest over the next 12–24 months:
- Anheuser‑Busch InBev (Leuven): Continues to pursue capacity investments and workforce development to support growth in strategic SKUs such as ultra‑low carbohydrate and lifestyle brands. Recent capital commitments to expand U.S. capacity and local manufacturing underscore a dual strategy of scale and local relevance.
- Heineken N.V. (Amsterdam): Demonstrates continued diversification into non‑alcoholic and premium formats, with financials confirming growth in these segments. Expect Heineken to invest behind brand elevation and global premium rollouts while protecting margin through disciplined mix management.
- Carlsberg Group (Copenhagen): The group strategy is centered on portfolio diversification and market share expansion in selective markets. Carlsberg’s public commentary emphasizes the importance of packaging economics and raw material exposure in shaping competitiveness.
- Molson Coors (Golden, Colorado): Positions itself on a mix of mainstream and craft portfolios, with a senior management focus on North American scale advantages and route-to-consumer innovations.
- Constellation Brands (New York): A key importer and marketer of major international brands; regulatory shifts affecting import tariffs materially change margin outlooks and channel strategy.
- The Boston Beer Company (Boston): A leader in craft and flavored malt innovation—its profit guidance has been subject to tariff and input-cost volatility, spotlighting the vulnerability of specialty players to trade and procurement shocks.
Dynamics and cost pressures shaping strategic choices in 2026
Our analysis synthesizes the most consequential industry dynamics executives must monitor and manage in 2026:
- Input-cost volatility: Malt remains the dominant raw-material cost driver in brewing, with barley constituting a significant share of malt composition. Price swings in barley and malt have direct and immediate margin implications for all tiers of producers.
- Packaging economics: Aluminum cans and glass bottles are not neutral choices—they embed materially different cost structures. For major producers, aluminum comprises a large share of packaging cost; conversion and canning economics are therefore central to SKU profitability and sustainability commitments.
- Trade and tariff uncertainty: Tariff movements are no longer peripheral. The reversal of certain U.S. import duties in April 2026 illustrates how regulatory changes can quickly alter competitive advantage for importers and local producers alike. Conversely, projected tariff liabilities can erode guidance for smaller players.
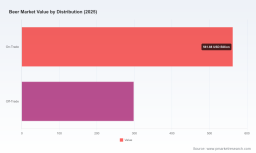
- Channel rebalancing: The on‑trade continues to recover post‑pandemic in many markets, but off‑trade remains indispensable for scale. Finding the right inventory cadence and promotional intensity across channels will determine 2026 share shifts.
What the full report provides (practical, operational, revenue-impacting)
- Transparent, auditable models for global market sizing (2020–2032) with scenario toggles for price, volume, and channel elasticity.
- Packaged playbooks: SKU rationalization, premiumization roadmaps, and non‑alcoholic launch templates with expected payback periods and margin impact.
- Supply‑chain stress tests and procurement strategies including malt and aluminum hedging frameworks and contract design.
- CapEx prioritization matrix that aligns facility upgrades and new capacity with demand adjacency and distribution economics.
- Competitive dissection of the leading global brewers with strategic options (defend, partner, acquire, niche) aligned to CR3/CR5 dynamics.
- M&A playbook and valuation yardstick calibrated to integration synergies, brand equity erosion risk, and regulatory exposure.
- Country and channel dashboards (interactive) for tailored market-entry or expansion decisions—note: detailed regional and category splits are reserved for full report subscribers.
Practical recommendations for 2026 — a prioritized checklist
- Reassess capex allocations now: Prioritize capacity investments that increase flexibility (contract canning lines, hybrid packaging) and shorten time-to-shelf. Use our scenario model to test payback across price and mix assumptions.
- Hedge intelligently: Implement forward purchase programs for malt and aluminum exposure where possible; evaluate collar strategies for key commodities rather than binary fixed-price contracts.
- Accelerate portfolio tilt: Move incremental dollars toward premium and non‑alcoholic SKUs with curated distribution pilots in high-margin channels; measure trade spend efficiency at SKU level.
- Optimize channel economics: Recalibrate on‑trade activation vs off‑trade shelf investments based on localized recovery and margin profiles; pilot digital D2C activations where regulation and logistics permit.
- Scan M&A opportunities: Target assets that provide either immediate route-to-market expansion or technology-driven cost takeouts (e.g., packaging conversion capabilities, cold‑chain efficiency).
- Institutionalize tariff monitoring: Embed trade-policy scenarios into quarterly planning; have contingency plans for rapid cost pass-through or promotional rebalancing.
In closing — how to convert this preview into 90‑day action
Use this preview as a provocation: the market is large and growing at close to a 5% CAGR, but the real value in 2026 will be created by companies that treat cost volatility, packaging economics, and portfolio mix as opportunities, not just risks. The full PW Consulting Beer Market report contains the segmented models, supplier cost benchmarks, competitor playbooks, and executable sprint plans you need to convert insight into revenue and margin outcomes in the coming year.
For immediate access to the full dataset, downloadable models, and tailored advisory engagements, visit the report page or contact our strategy team to commission a 90‑day activation plan aligned to your specific market footprint. The full market segmentation and the proprietary scenario models are available exclusively in the complete study.
For detailed analysis of this topic, please visit the official page: Beer Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com