

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
Kiosk Market to Reach USD 1,089.4M by 2032 at 15.6% CAGR — PW Consulting

Kiosk Market 2026: A Strategic Preview for Decision Makers
As organizations accelerate service automation and contactless experiences, the kiosk market has shifted from a niche hardware play to a strategic platform for customer engagement, payments modernization and distributed computing at the edge. PW Consulting’s latest Kiosk Market research (base year 2025, forecast 2026–2032) synthesizes historical growth, near-term inflection points and a seven-year forecast built to inform board-level choices in 2026. This preview outlines why the study matters for your 2026 strategy, the high‑level market trajectory, competitive forces to watch, and the pragmatic tools inside the full report that executives rely on when allocating capital, partnerships and product roadmaps.
Kiosk Market
Market trajectory: scale, speed and structural concentration
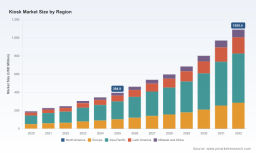
The kiosk market has entered a sustained growth phase. From a high‑single‑hundreds million base in 2025, the market is forecast to expand at a compound annual growth rate (CAGR) of 15.6% through 2032, with the dollar run‑rate expected to cross into the billion‑dollar range before the end of the forecast horizon. This pace reflects a confluence of factors — enterprise digitization programs, rapid rollouts of self‑ordering in QSR and retail, and expanded public‑sector deployments for citizen services. Market concentration is meaningful: the top three vendors capture a clear majority share and the top five consolidate roughly two‑thirds of industry revenue, a structure that favors established OEMs and integrated systems providers but still leaves pockets of opportunity for specialized innovators.
Kiosk Market
Why this matters for 2026 decisions
- Capital allocation and rollout timing: With double‑digit growth baked into the outlook, 2026 is the year to decide whether to accelerate rollouts or optimize for profitability. Buyers must weigh faster deployments against rising component and logistics costs driven by semiconductor tariff pressure.
- Procurement and supply‑risk management: Tariff changes and component constraints are increasing build and operating costs for kiosk hardware. Procurement teams should prioritize vendor resilience, alternative sourcing for hardened processors and contractual protections for price volatility.
- Product and accessibility differentiation: Regulatory and social expectations are increasingly demanding inclusive designs; recent Gen‑2 accessible self‑ordering launches illustrate how accessibility can be a market differentiator and a compliance baseline.
- Edge compute and connectivity strategy: As kiosks evolve into distributed edge nodes, decisions about embedded compute, IoT management platforms and broadband connectivity matter more. Recent regulatory moves that lower broadband modernization burdens can change deployment economics for networked kiosks.
Key demand and supply dynamics shaping 2026 strategy
- Demand multipliers: Retail and hospitality seeking to reduce labor cost and improve throughput, banking automation, transportation touchpoints and healthcare self‑service are primary demand drivers. Business cases increasingly hinge on integration with payments, loyalty and analytics rather than hardware alone.
- Platformization of kiosk capabilities: Expect customers to evaluate kiosks as a platform — hardware + software + cloud management + payments — rather than discrete terminals. Vendors offering lifecycle management, secured payment stacks and analytics gain pricing power.
- Compliance and payment standards: New rules around in‑field payment protections (such as PCI PIN on Glass interpretations) and accessibility standards are raising the technical bar, influencing procurement specs and third‑party certification needs.
- Cost and infrastructure headwinds: Semiconductor tariffs and shifts in data‑center policy (including new levies and accountability requirements in some jurisdictions) are increasing total cost of ownership for networked kiosk solutions and shifting tradeoffs between centralized processing and edge compute.
- Regulatory tailwinds: On the positive side, recent policy actions easing broadband modernization barriers can accelerate deployments by reducing regulatory friction for connectivity upgrades that kiosks depend on.
Competitive landscape — who to benchmark and why
Market structure favors a blend of globally integrated suppliers, hardware specialists and verticalized system integrators. The full report includes vendor heatmaps and strategic playbooks; below are high‑level profiles and tactical implications for buyer and partner strategies.
Kiosk Market
- KIOSK Information Systems (Phoenix, AZ): End‑to‑end design, manufacturing and nationwide support capabilities make them a strong choice for large, distributed deployments where single‑vendor accountability matters. Recent partnerships and new ergonomic product lines position them to address reliability and accessibility concerns in large rollouts.
- Elo Touch Solutions (Milpitas, CA): Strong in touchscreen and self‑service hardware, particularly where display performance and touch reliability are decisive. Their portfolio suits retailers and QSRs prioritizing human‑interface quality.
- LG Electronics: A consumer‑electronics leader extending accessible self‑ordering kiosks; their focus on inclusive design and strong manufacturing scale is attractive for clients placing accessibility at the center of differentiation.
- Diebold Nixdorf & NCR Corporation: Both bring banking and retail software ecosystems together with hardware, making them go‑to options where integration with core banking, POS and payment networks is mission‑critical. Their cloud/IoT management capabilities enable fleet operations at scale.
- Specialists and OEMs (Olea, Acrelec, Meridian, ZIVELO, AOPEN, Posiflex, and others): These firms compete on customization, ruggedization, payment integration and vertical specialization (e.g., QSR, healthcare, government). Their agility often outpaces larger incumbents in niche use cases.
For vendors and enterprise buyers alike, three competitive imperatives emerge: (1) develop clear platform offerings that bundle hardware, secured payments and fleet management; (2) demonstrate supply‑chain resilience and component alternative strategies; and (3) invest in accessibility and compliance certifications as go‑to‑market differentiators.
Recent industry moves that signal where 2026 decisions should focus
- Product partnerships and co‑engineering deals that colocate hardened processing units with ergonomic kiosk shells demonstrate a market shift toward reliability and serviceability as primary purchasing criteria.
- Accessibility‑focused product launches show early movers capturing reputational and contract advantages in regulated verticals and public procurement.
- New hosted payment and gift‑card add‑ons indicate demand for turnkey, cloud‑native services layered on kiosk hardware, creating recurring revenue possibilities for vendors and ongoing data value for enterprise buyers.
- Component tariffs and data‑center policy shifts are altering deployment economics, making localized edge computing and alternative procurement approaches more attractive.
What’s in the full PW Consulting Kiosk Market report — practical deliverables
The full study is designed as an operational playbook for 2026 planning cycles. Key deliverables include:
- Validated market sizing and a seven‑year forecast segmentation framework mapped to buyer use cases and procurement flows (note: the preview intentionally omits granular split figures to preserve subscription value).
- Decision‑ready vendor benchmarking: CR3/CR5 concentration analysis, vendor capability matrices, partner ecosystems, and risk heatmaps tailored to enterprise procurement teams.
- Deployment model economics: TCO templates for indoor, rugged outdoor and payment‑integrated kiosks that incorporate hardware, connectivity, software licensing and lifecycle support assumptions.
- Regulatory & compliance checklist: actionable guidance on payment security (PIN on Glass implications), accessibility requirements and connectivity compliance across major jurisdictions.
- Procurement playbooks and contract clauses: sample RFP language, SLA expectations for remote monitoring and firmware security commitments, and penalty/price‑adjustment language for component cost volatility.
- Use‑case ROI calculators and pilot design templates: step‑by‑step approaches to pilot small fleets, measure throughput and convert pilots to scaled rollouts with a clear payback horizon.
Strategic recommendations for 2026
- Prioritize platform partners: Choose vendors that offer lifecycle management, cloud orchestration and payment integrations to reduce integration risk and accelerate time‑to‑value.
- Hedge component exposure: Build alternate sourcing, long‑lead procurement and price escalation protections into supplier agreements to mitigate semiconductor tariff and component cost impacts.
- Design for inclusivity and compliance: Make accessibility and payment‑security certification non‑negotiable requirements in procurement specs — these reduce deployment friction and improve public‑sector win rates.
- Test edge vs centralized models: Run controlled pilots to determine the right balance between on‑device compute and cloud processing given local connectivity economics and data‑sovereignty constraints.
- Use data to commercialize deployments: Instrument kiosks for analytics and loyalty integration from day one — kiosk hardware becomes a channel for monetizable behavioral and transaction data.
Final words — the decision window for 2026
2026 represents a pivotal year: the market’s strong growth rate and increasing vendor concentration create both risk and leverage for enterprises and investors. The choices made now — around partner selection, procurement strategy, and product accessibility — will determine whether organizations capture outsized returns from kiosk rollouts or face escalating costs and integration friction. PW Consulting’s full Kiosk Market report translates the macro growth path, competitive dynamics and regulatory shifts into concrete actions and ready‑to‑use tools that senior leaders need to make confident, defensible decisions in 2026. For access to the complete segmentation, vendor scorecards and deployment economics, consult the full report on our website.
For detailed analysis of this topic, please visit the official page: Kiosk Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com