

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Microwave Oven Market Poised for 3.5% CAGR Through 2032

Microwave Oven Market 2026: A Strategic Preview for Executive Decision‑Making
Executive snapshot
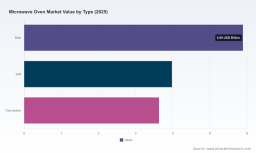
Between 2020 and 2025 the global microwave oven market expanded materially, moving from roughly USD 8.5 Billion to about USD 13.5 Billion (base year 2025). Looking ahead, our forecast through 2032 anticipates continued growth at a steady compound annual growth rate (CAGR) of approximately 3.5% across the 2026–2032 projection window, with an expected market value in the low‑to‑mid double‑digits of USD Billions by the end of the period. For corporate leaders planning 2026 investments, product roadmaps, or M&A activity, these macro dynamics create a clear mandate: optimize for moderate, durable growth while preparing for episodic regulatory and trade disruptions.
Microwave Oven Market
Why this preview matters for 2026 decisions
- Time horizon alignment: firms that align 2026 operating and capital plans to a mid‑single‑digit CAGR through 2032 preserve optionality in product innovation, channel development, and geographic expansion.
- Margin preservation: the market’s steady expansion suggests incremental revenue opportunities, but margin pressure will come from component cost volatility, tariffs, and competitive pricing—factors that require operational levers (sourcing, mix, automation) to protect profitability.
- Regulatory and safety posture: recent regulatory movements—and persistent safety standards—mean compliance and product strategy cannot be deferred. Decisions taken in 2026 on certification, labeling, and energy strategy will have multi‑year consequences.
Market trajectory and structural drivers
The microwave oven market’s growth over the past half‑decade has not been driven by a single inflection; rather, it reflects a portfolio of secular and cyclical drivers. Urban household formation, ongoing replacement cycles in mature markets, and the sustained appetite for compact and multifunction cook‑appliances underpin baseline demand. Simultaneously, technology adoption—convection capabilities, air‑fry integrations, IoT connectivity and smart‑home interoperability—tilts premiumization opportunities toward manufacturers that can marry differentiated features with scalable manufacturing.
Microwave Oven Market
From a 2026 planning perspective, three structural forces deserve elevated attention:
Microwave Oven Market
- Product convergence: microwave ovens are increasingly evaluated as multifunction kitchen platforms (e.g., convection + microwave + air frying), which raises R&D priority and SKU rationalization challenges.
- Channel evolution: omnichannel retailing and value‑chain partnerships (private label OEM supply, retailer exclusives, direct‑to‑consumer) change margin calculus and inventory strategies.
- Input cost and trade volatility: component supply lines for magnetrons, PCBs, and specialized panels remain exposed to tariff adjustments and regional production shifts—creating episodic cost spikes that must be hedged strategically.
Operational and regulatory dynamics you must model in 2026
Two regulatory developments and one trade dynamic are especially salient for executive planning:
- U.S. energy regulation: the U.S. Department of Energy proposed rescission of prior energy conservation standards for microwave ovens in 2025. That proposal changes the incentives around energy‑efficiency investments and product positioning in North America; firms should model both a scenario where prescriptive efficiency standards are reinstated and one where flexible labeling and voluntary programs become the norm.
- Safety standards: FDA radiation safety performance requirements remain in force under 21 CFR 1030.10, mandating manufacturer certification and labeling. Compliance costs and reputational risk from any lapse are non‑trivial and should be embedded in product launch timelines.
- Trade cost pass‑through: tariffs introduced on certain imports in 2025 increased core goods consumer prices, with recent analysis indicating an approximate 3.1% uplift in price levels through early 2026. Organizations must evaluate local assembly, near‑shoring, or strategic inventory positioning to blunt the impact on sell‑through and margins.
Competitive landscape — what matters to strategy
The market remains populated by a mix of large multinational branded OEMs, dedicated appliance conglomerates, and regional specialists. Leading players operate across three strategic archetypes: global brand owners with strong distribution and product‑development muscle; high‑volume OEM/manufacturers that supply multiple brands; and niche innovators focused on integrated or space‑saving solutions. Below we summarize the strategic posture of six core participants that every competitor and investor should watch in 2026.
- Midea Group (Foshan, Guangdong, China) — https://www.midea.com
Strategic position: a dominant OEM/manufacturer role combined with branded product offerings. Strength lies in scale manufacturing, a broad model range (including countertop Versa Series models) and deep OEM relationships. Strategic implications for rivals: competing on price and speed-to-market requires either similar scale or focused differentiation; for investors, Midea’s dual role makes it a logical partner or acquisition target for retailers seeking stable supply.
- Galanz (Shunde, Guangdong, China) — https://www.galanz.com
Strategic position: specialized high‑volume OEM with extensive private‑label relationships. Galanz’s playbook emphasizes manufacturing efficiency and retail partnerships. For 2026, expect continued pressure on global private‑label margins and potential consolidation of distribution deals in value channels.
- LG Electronics (Seoul, South Korea) — https://www.lg.com
Strategic position: technology and brand leader, especially in built‑in and convection microwave segments and in smart‑home integration (SmartThinQ). LG’s advantage is premium positioning and cross‑category bundling in connected home ecosystems—an attractive proposition for channel partners targeting higher ticket averages.
- Sharp Corporation (Ibaraki, Japan) — https://www.sharpusa.com
Strategic position: product innovation focused on form factor and convenience (e.g., Convection Microwave Drawer™). Recent February 2026 product launches that target compact living solutions signal an offensive in small‑space premium segments—areas where incumbents without differentiated designs may struggle to compete.
- Whirlpool Corporation (Benton Harbor, Michigan, USA) — https://www.whirlpool.com
Strategic position: full‑spectrum appliance company with multi‑brand distribution (Whirlpool, KitchenAid, Amana) and some domestic manufacturing. Whirlpool’s leverage lies in integrated kitchen sets and service networks—critical advantages when selling higher‑value built‑in solutions or offering extended warranty services.
- GE Appliances (Louisville, Kentucky, USA) — https://www.geappliances.com
Strategic position: broad product portfolio including convection and air‑fry options, with deep North American dealer relationships. GE Appliances benefits from brand recognition and channel depth—useful levers to accelerate new product uptake when combined with targeted marketing and trade incentives.
Strategic levers for 2026 planning
Based on our analysis, executives should prioritize a short list of tactical and strategic levers to deploy in 2026:
- Portfolio engineering: simplify SKUs to reduce manufacturing complexity while preserving a premium lane for feature‑rich, higher‑margin models. Prioritize modular designs that allow region‑specific adaptations without full reengineering.
- Sourcing and footprint: accelerate supplier diversification and consider near‑shoring for key components exposed to tariffs. Where feasible, convert fixed cost to variable through contract manufacturing partnerships.
- Regulatory hedging: maintain full compliance with FDA safety standards and prepare alternative energy‑efficiency value propositions in markets where prescriptive standards are in flux.
- Channel optimization: rebalance investments between dealer/distributor incentives and direct digital channels to improve margin capture and customer data flows.
- Innovation cadence: invest in targeted features with clear consumer willingness‑to‑pay (smart connectivity, multi‑functionality, compact designs) and accelerate time‑to‑market by co‑development with Tier‑1 OEMs or platform partners.
- M&A and partnerships: evaluate bolt‑on acquisitions that add design IP, compact appliance technology, or regional distribution; consider strategic alliances with large OEMs for shared capacity or exclusive product runs.
What the full report delivers (practical, actionable content)
Our full market research pack is built for decision‑makers who need executable insight rather than descriptive statistics. Highlights include:
- Detailed historical demand analysis (2020–2025) and scenario forecast (2026–2032) with modeled sensitivity to input cost and regulation.
- Go‑to‑market playbooks: SKU rationalization templates, channel profit bridges, and promotional elasticity models relevant to large and mid‑market players.
- Cost and sourcing deep dives: component price trends, supplier concentration maps, and recommended hedging tactics.
- Competitive benchmarking: product feature scorecards, R&D focus matrices, and commercial positioning for leading brands and OEMs.
- Regulatory and trade scenario planning: prebuilt decision trees showing the P&L impact of regulatory reinstatement versus deregulation, and tariff pass‑through simulations.
- M&A screening toolkit: acquisition candidate filters and pro forma synergies templates tailored to appliance industry dynamics.
How to use this intelligence in 90 days
For executives needing rapid, actionable outcomes, we recommend a three‑phase 90‑day plan:
- 30 days — immediate risk triage: quantify exposure to tariff and regulatory scenarios for your top SKUs; secure alternative suppliers for critical components.
- 60 days — margin and portfolio actions: implement SKU simplification pilots, refine channel incentives, and test premiumized feature bundles in select markets.
- 90 days — strategic investments: finalize near‑shore or contract manufacturing contracts where ROI exceeds thresholds; greenlight targeted R&D sprints for compact and smart‑enabled models.
Conclusion — the value proposition of the full study
Microwave ovens remain a core appliance category with steady growth and profitable upgrade paths. The 2026 decision window is defined less by explosive market expansion and more by the quality of strategic choices—where you build, how you price, which features you prioritize, and how you manage regulatory exposure. Our full study provides the quantitative backbone—demand models, sensitivity tests, and competitor benchmarks—plus the pragmatic toolkits you need to convert insight into action.
To preserve the most commercially sensitive segmentation and granular competitive metrics for subscribing clients, we have intentionally withheld detailed regional and application splits from this preview. For the complete dataset, downloadable models, and implementation templates that will enable confident 2026 planning, visit the full report page or contact our advisory team to schedule a tailored briefing.
For detailed analysis of this topic, please visit the official page: Microwave Oven Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com