

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Pressure Vessels Market to Hit USD 769M by 2032, Growing at 4.93% CAGR

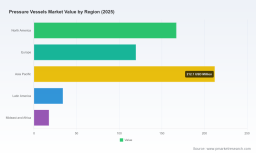
Pressure Vessels Market: Strategic Imperatives for 2026 — A PW Consulting Preview
As companies prepare capital allocation, supply-chain realignment, and technology investments for 2026, understanding the pressure vessels market’s trajectory is a decisive strategic input. PW Consulting’s latest market study—anchored on a 2025 base year, a rich 2020–2025 historical dataset, and a 2026–2032 forecast horizon—translates macro momentum into operational choices. In short: the industry is growing, technical and regulatory complexity is increasing, and competitive dynamics reward scale, certification depth, and service capability. This preview explains why the full study will matter for boardrooms and C-suites planning the coming 12–36 months, while intentionally reserving detailed segment allocations to the full report.
Pressure Vessels Market
What the headline numbers tell decision-makers
By 2025 the global pressure vessels market had expanded substantially from the start of the last decade, reflecting recovery in industrial capex and durable demand across energy, chemical, and process industries. Our base-year estimate places the market size in mid-2025, and the forecast model projects steady expansion through 2032 at a compound annual growth rate (CAGR) of approximately 4.93%. Under our central scenario, market size grows meaningfully by 2032, reflecting a combination of retrofit and replacement cycles, new-build in selected end-markets, and an increasing role for engineered and high-specification vessels.
Pressure Vessels Market
Why these headline metrics matter for 2026 planning: they provide an empirically grounded view of near-term demand visibility and medium-term expansion. For capital-intensive businesses, the CAGR and base-year market scale are the baseline for sizing investment, estimating payback periods on new fabrication capacity, and determining whether to pursue organic growth, strategic partnerships, or targeted M&A.
Pressure Vessels Market
Key market dynamics shaping 2026 decisions
- Input cost volatility and margin pressure.
Raw material pricing—steel and specialty alloys—continues to be the single largest cost driver for manufacturers. Industry studies indicate that carbon steel alone represents a substantial share of production cost, forcing manufacturers to build proactive sourcing and hedging strategies into their 2026 procurement plans. Procurement teams must incorporate scenario-based cost models into bid decisions and long-lead contracts.
- Regulatory tightening and compliance as a competitive moat.
The 2025 edition of the ASME Boiler and Pressure Vessel Code (BPVC) Section VIII introduced new mandatory provisions for design and construction. Subsequent interpretive guidance and practitioner webinars in early 2026 have already influenced engineering practices. Simultaneously, the timing of API inspector certification cycles has shifted, affecting service and inspection capacity. For OEMs and fabricators, certification readiness and demonstrable compliance capability are table stakes; for buyers, supplier pre-qualification must be rethought to include code-readiness.
- Technology diffusion: additive manufacturing and digital twins.
Certification of additively manufactured components for high-pressure applications is moving from novelty to regulated practice. Recent third-party certifications for large AM valves illustrate the pace at which advanced manufacturing methods can become commercially viable. Alongside AM, digital engineering—CAE-driven design by analysis, integrated documentation workflows, and digital twins for asset life-cycle management—is increasingly influencing TCO and uptime metrics.
- Service and aftermarket economics.
As installed bases age in mature markets and new fleets are built in growth geographies, aftermarket service, inspection, and retrofitting will command a rising share of lifetime revenue. Companies that embed inspection capability, rapid replacement cycles, and remote diagnostics into their offerings will capture higher-value recurring revenue streams.
Competitive landscape: who matters and why
The pressure vessels market is characterized by a mix of specialist fabricators, diversified heavy-equipment EPCs, and precision component suppliers. Our competitive mapping highlights distinct archetypes:
- ASME-certified specialist fabricators — firms with deep shop-floor capability and client-facing customization expertise. These providers excel in turnaround times for bespoke equipment and serve process-intensive buyers requiring tight documentation and traceability.
- Large EPC and heavy-equipment manufacturers — multi-code suppliers that integrate pressure vessels into larger process and power projects. Their competitive advantage lies in project execution capability, scale, and relationships with major oil & gas and power customers.
- Precision and engineered-component suppliers — firms focused on high-tolerance components and integrated systems (including filtration and valve packages), often supplying higher-margin specialized applications.
Representative names included in our analysis illustrate these archetypes—ranging from regional ASME-certified fabricators focused on customized vessels, to multinational heavy-equipment manufacturers serving power and nuclear sectors, to precision-component firms serving niche industrial applications. While this preview avoids publishing granular market shares, the full report synthesizes supplier scorecards, capability matrices, and strategic positioning maps that show strengths, weaknesses, and near-term moves for each major player.
Market structure and consolidation signals
The market displays a balance between local fabricators and a set of stronger national/global players. Concentration metrics indicate a moderately fragmented market with significant headroom for consolidation in targeted subsegments. For corporate strategists, this implies two parallel approaches: defend and deepen capabilities where scale and certification create durable differentiation; and pursue bolt-on acquisitions or partnerships in geographies or niche technical segments where fragmentation keeps valuations attractive.
What the PW Consulting report delivers (practical takeaways)
This study is designed for executives who must translate market signals into actionable plans. It does not merely present forecasts; it provides tools and frameworks to operationalize strategy.
- Market model and sensitivity analysis — transparent scenario models that let you test alternative steel-price paths, capex pipelines, and demand shocks.
- Regulatory impact matrix — line-of-sight on how ASME BPVC 2025 changes and API certification schedules affect design, documentation, and inspector availability across product classes.
- Supplier and project heat maps — where to deploy capital for new fabrication capacity, where to prioritize aftermarket investments, and which geographies require expanded service footprints (note: we reserve segment-level allocations for the full report).
- Competitive scorecards — capability assessment on certification, production footprint, technical specialization, and aftermarket services for the leading firms in the market.
- M&A playbook and valuation benchmarks — scenarios for consolidators, integration checklists, and a three-tier target-screening approach to identify high-impact acquisitions.
- Commercial and procurement playbooks — contract structures, risk-sharing models, and bidding strategies designed to protect margin in a volatile raw-material environment.
Practical strategic recommendations for 2026
- Short-term (0–12 months):
Lock down long-lead inputs through flexible supply agreements and indexed pricing clauses. Accelerate certification programs and ensure documentation systems comply with ASME BPVC 2025 requirements. Begin re-scoping supplier pre-qualification to incorporate updated code-readiness and inspector availability.
- Medium-term (12–24 months):
Invest in digital engineering capabilities—CAE, design-by-analysis workflows, and digital-documentation systems—to reduce cycle times and lower engineering rework. Build or partner for aftermarket service capability, including remote monitoring and inspection-as-a-service offerings.
- Strategic (24–36 months):
Evaluate M&A in fragmented subsegments where scale yields procurement leverage and certification capabilities. Consider vertical moves into filtration/valve integration or aftermarket service platforms to capture higher lifetime value.
Risks and watch-items for boards
- Persistent steel and alloy price volatility that erodes thin fabrication margins.
- Regulatory non-compliance risk as rules evolve—companies without proactive engineering and documentation updates face rework, penalties, or lost contracts.
- Capacity imbalances—localized overbuild or labor shortages that drive lead times and push buyers to substitute suppliers.
- Technology adoption mismatch—late investment in digital engineering and additive manufacturing can leave firms uncompetitive on cost and lead time for complex components.
Why the full report is essential for 2026 decisions
This preview sets out the structural drivers and strategic choices. The full PW Consulting report contains the quantitative backbone required to operationalize these recommendations: a transparent market model, granular segmentation and regional demand scenarios, detailed supplier profiles and scorecards, and executable M&A targets. We intentionally withhold core segment-level allocations in this preview to protect the actionable value of our primary analysis—clients who need transaction-ready intelligence, bid-level price sensitivity matrices, or supplier contract templates will find them in the complete study.
Closing: the immediate next steps for executives
- Request the full report to access the segment-level demand model and supplier scorecards needed to underwrite capital projects and M&A.
- Use our short checklist to assess certification readiness for ASME BPVC 2025 changes and API inspector availability—this is already influencing 2026 procurement windows.
- Engage PW Consulting for a rapid (4–6 week) diagnostic if you are considering capacity expansion, an acquisition, or a major procurement tender in 2026.
Pressure vessels remain foundational equipment across energy, chemicals, and process industries. The market is sufficiently large and growing at a stable mid-single-digit CAGR, but evolving regulation, sourcing risk, and technological shifts mean that smart timing and disciplined execution will determine who captures the next wave of value. PW Consulting’s full study converts that macro view into operational playbooks—visit our report page to obtain the detailed segment, regional, and supplier intelligence your 2026 strategy requires.
For detailed analysis of this topic, please visit the official page: Pressure Vessels Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com