

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Coronary Stents Market Poised for 6.5% CAGR Through 2032

Coronary Stents Market 2026: Strategic Preview for Boardroom Decision-Making
As PW Consulting’s Senior Strategy Advisor and Chief Industry Analyst, I present a forward-looking synthesis of the Coronary Stents market designed to accelerate executive decisions in 2026. This briefing communicates the strategic contours you need to evaluate opportunities, prioritize investments, and mitigate regulatory and reimbursement risk — while preserving the granular segmentation and proprietary forecasts that drive actionable plans. For full segment-level tables, regional splits, and modeled scenario outputs, please consult the complete report.
Coronary Stents Market
Why this study matters to 2026 corporate strategies
-
Timing and scale: With a well-defined historical baseline (2020–2025) and a clear forecast window (2026–2032), the market exhibits a steady compound annual growth rate (CAGR) of 6.5%. That pace reflects a balance of durable demand for percutaneous coronary intervention and incremental gains driven by device innovation, procedural code changes, and evolving reimbursement.
Coronary Stents Market -
Concentration and competitive dynamics: The market remains highly concentrated (CR3 ~76%, CR5 ~85%), which amplifies the strategic implications of product launches, regulatory clearances, and targeted commercial plays. For challengers and incumbents alike, marginal improvements in clinical differentiation or supply-chain resilience can translate to material share shifts.
Coronary Stents Market -
Decision horizon: 2026 is a pivotal inflection year. New procedural codes, updated reimbursement rules, and recent PMA/CE actions create both opportunities (improved RVU credits for complex PCI) and obligations (heightened evidence requirements for Class III devices). Boards must align R&D, regulatory timing, and market entry sequences around these inflection points.
Market trajectory: What the headline numbers tell you
Our modeling — calibrated to 2025 as the base year — projects continued expansion through 2032. The market’s growth profile is driven by a combination of demographic trends, rising procedural volumes in select geographies, and iterative device innovation (polymer science, ultra-thin struts, bioresorbable and hybrid platform refinements). For strategy teams, the takeaway is simple: the market is large enough to support multiple value pools (premium innovation, cost leadership, and niche lesion/clinical subsets), but scale benefits accrue quickly to firms that lock in clinical evidence and favorable reimbursement early.
Dynamics shaping strategic choices in 2026
-
Regulatory posture and pathway complexity: Coronary drug-eluting stents remain in the Class III regulatory category requiring PMA in the U.S. Recent PMA supplement approvals and CE clearances underscore the operational imperative of designing trials that demonstrate both safety and clinically meaningful endpoints (e.g., target lesion failure, endothelial healing). Companies planning U.S. launches must synchronize clinical milestones with submission pathways to avoid costly market access delays.
-
Reimbursement coding shifts: The introduction of a new complex PCI CPT code for 2026 (with materially higher RVU credits for multi-lesion or bifurcation procedures) impacts the economics of treating complex disease. Commercial teams should model price realization under both legacy and new coding structures and prepare payer briefs quantifying procedural value and device-specific cost offsets.
-
Clinical differentiation as a commercial lever: Recent product progress — upgraded polymers, bioabsorbable coatings, and next-generation platforms optimized for deliverability and healing — means clinical evidence is again the primary lever for premium positioning. FDA and CE actions earlier in 2025 have already reshaped value propositions for some flagship platforms, increasing the importance of head-to-head evidence and real-world registries.
-
Supply-chain and manufacturing resilience: As firms scale new platforms, capacity planning, subcontractor qualification, and quality oversight determine time-to-market. Strategic investors should stress-test supplier single points of failure and evaluate regional manufacturing footprints aligned to regulatory and tariff risk.
Competitive landscape: What incumbents and challengers are doing
The competitive map is dominated by a handful of global players with deep clinical programs and broad distribution networks, alongside focused innovators pursuing niche differentiation. Recent corporate activity illustrates the interplay between product development and regulatory strategy:
-
Medtronic accelerated an incremental innovation cycle with CE clearance for an upgraded polymer on a well-established platform in early 2025 — an example of how iterative improvements can extend lifecycle value and address thrombosis risk concerns.
-
Boston Scientific secured U.S. regulatory approval for a bioabsorbable polymer platform in 2025, a strategic move that supports claims around reduced long-term inflammation and positions the company for premium reimbursement conversations.
-
Abbott’s 2025 launch of a new-generation platform emphasized deliverability and endothelial healing in complex lesions, signaling an agenda of clinical differentiation for high-touch lesion subsets.
Smaller and regional manufacturers are not passive: targeted product positioning, competitive pricing in fast-growing territories, and local evidence generation remain viable paths to share gain. The full report dissects each major competitor’s product portfolio, clinical pipeline, regulatory status, and strategic moves — including patent families and licensing exposures — to inform M&A and partnership decisions.
What the report provides — practical, board-ready outputs
-
Market sizing and scenario modeling: Topline market values (historical and forecast) are provided by year, with transparent modeling assumptions. Several scenarios isolate the impact of accelerated adoption, adverse reimbursement moves, or clinical setbacks on revenue and share outcomes.
-
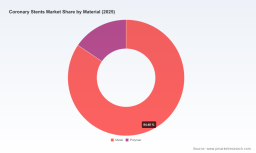
Segmentation and value-pool mapping: We map value by device type, material, and clinical application and quantify where margin and volume converge to create the most attractive commercial opportunities. (Note: this preview intentionally omits the granular segment tables and regional splits included in the full report.)
-
Regulatory and reimbursement playbooks: Device-by-device regulatory pathways, PMA/CE timelines, and payer submission templates are included — along with recommended evidence-generation strategies to optimize time-to-payor-acceptance.
-
Competitive heatmaps and product dossiers: Comparative performance matrices, launch readiness checklists, and an interpreted chronology of recent regulatory events provide a rapid assessment of competitor positioning.
-
Go-to-market and commercial scenarios: Channel strategies, pricing levers, contracting templates, and a quantified ROI model for field force deployment by geography.
-
M&A and partnership shortlist: Data-driven candidate profiles for bolt-on acquisitions, technology licensing, and co-development options, prioritized by strategic fit and execution risk.
Immediate strategic imperatives for 2026
-
Prioritize evidence generation for high-value claims: If your platform targets complex lesions, bifurcations, or high-bleeding-risk patients, invest in pragmatic randomized trials and real-world registries now so that pivotal data align with reimbursement cycles and guideline updates.
-
Prepare regulatory sequences that mirror commercial priorities: For U.S. market access, negotiate PMA strategy and supplement pathways early. For EU and other jurisdictions, leverage CE/Notified Body timing to support global rollouts while maintaining data consistency.
-
Recalibrate commercial models to new procedural economics: Update pricing and contracting models to reflect enhanced RVU credits for complex PCI and to capture the margin benefits of procedure-driven reimbursement changes.
-
Defend and extend differentiation through targeted partnerships: Consider alliances for polymer technology, delivery-platform miniaturization, or local manufacturing to accelerate market entry in high-growth territories.
-
Stress-test supply-chain resilience: Ensure second-source options for critical components and build inventory strategies that align to regulatory filing milestones and launch windows.
Risks, uncertainties, and what to watch
-
Regulatory reversals or unexpected post-market findings can compress near-term value capture; monitor PMA supplements and global post-market surveillance reports closely.
-
Payer pushback on pricing, or slower-than-expected uptake of new CPT codes in institutional billing systems, could delay revenue realization and complicate sales forecasting.
-
Competitive launches that combine robust clinical data with aggressive contracting could force margin concessions; identify defensive tactics and counteroffer playbooks in advance.
How PW Consulting’s report turns insight into action
This study is structured to move teams from insight to execution in weeks, not months. It pairs granular financial modeling and competitor dossiers with executable playbooks: regulatory submission calendars, evidence-generation budgets, commercial roll-out templates, and an M&A shortlist aligned to strategic priorities. Where boards need rapid decisions, we deliver prioritized next steps and scenario-tested action plans.
Next steps
The full Coronary Stents Market report contains the segment-level tables, regional and application splits, and downloadable model files that underpin the summary above. For corporate development, commercial strategy, or regulatory planning workshops in 2026, PW Consulting can provide tailored briefings that extract the report’s most relevant insights for your portfolio and timetable.
Contact our team to schedule a deep-dive presentation and obtain the detailed segmentation and forecast models necessary to finalize your 2026 investment and go-to-market decisions.
For detailed analysis of this topic, please visit the official page: Coronary Stents Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com