

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Steering Wheel Switch Market to hit $593.1M by 2032 — CAGR 7.25%

Automotive Steering Wheel Switch Market — Strategic Briefing for 2026 Decision-Making
As OEMs and Tier‑1 suppliers set strategic priorities for 2026, the steering wheel switch market sits at a rare intersection of hardware evolution, software‑defined user experience, and regulatory change. This briefing, prepared by PW Consulting’s senior strategy team, synthesizes the directional signals and hard market facts that should inform near‑term investments and partnerships. It is designed to demonstrate the depth of analysis in our full Automotive Steering Wheel Switch Market study while deliberately withholding the granular segment tables and model-level forecasts that are available in the complete report.
Automotive Steering Wheel Switch Market
Market snapshot — trajectory and scale (base year 2025)
The market for steering wheel switches has shown steady expansion through the past five years and is forecast to continue on a mid‑single digit upward trajectory as vehicle electrification, software integration, and new HMI modalities reshape product scope. Using 2025 as the report’s base year, our market model captures the 2020–2025 historical run and extends forecasting through 2026–2032. Key macro takeaways:
Automotive Steering Wheel Switch Market
- The market demonstrated sustained recovery and growth across 2020–2025 despite supply chain shocks and rising component complexity.
- Our long‑range forecast to 2032 is built on an assumed compound annual growth rate (CAGR) of 7.25%, reflecting secular demand from EVs, ADAS‑ready architectures, and vehicle software monetization.
- All monetary values in the analysis are expressed in USD and reported at the million‑dollar level to support comparability across supplier scorecards and scenario runs.
Why 2026 is a strategic inflection point
Three concurrent shifts crystallize 2026 as the year when steering wheel switches graduate from mechanical commodity to strategic module:
Automotive Steering Wheel Switch Market
- Product architecture shift — Steer‑by‑wire prototypes have moved into series production readiness. Modular steer‑by‑wire systems change how switches are specified: electrical compatibility, fail‑safe requirements, and certification pathways now affect upstream suppliers more than before.
- HMI and software convergence — AI‑enabled voice, context‑aware controls, and biometric sensors are being integrated into the steering column and wheel. The value of a switch is increasingly determined by its firmware, sensor fusion, and over‑the‑air update capability rather than purely tactile characteristics.
- Platformization and customization — OEMs demand modular control interfaces that can be customized across model lines without bespoke hardware for every derivative. This raises the bar for suppliers offering scalable, configurable switch platforms.
Recent industry moves underline these trends: a leading safety supplier unveiled a foldable steering wheel concept for autonomous modes, a major supplier launched a modular control interface platform, and another supplier publicly announced a production‑grade steering solution compatible with steer‑by‑wire systems. These events are not isolated; they form a coherent narrative of platform consolidation, systems integration, and new regulatory considerations.
What this means for different decision‑makers in 2026
- OEMs: Reassess supplier qualification criteria to elevate software maturity, functional safety pedigree, and updateability. Embed switch module requirements into broader vehicle domain architecture roadmaps to avoid late-stage rework.
- Tier‑1 suppliers: Prioritize modular electrical architectures and invest in scalable HMI software stacks. Consider fast‑follow M&A to acquire sensor or firmware capabilities rather than building from scratch.
- Component suppliers: Focus on cost‑to‑integrate, miniaturization of actuation, and improving EMC/ESD performance for EV environments. Build certification roadmaps aligned with ISO functional safety and emerging steer‑by‑wire standards.
- Software and UX providers: Position for platform deals by demonstrating secure OTA update systems, biometric integration, and data‑driven personalization of steering‑wheel controls.
- Investors and M&A teams: Target assets that combine hardware know‑how with software IP, and prioritize companies that offer configurable platforms and clear upgrade paths for AV and EV applications.
Competitive landscape — forces shaping supplier positioning
The market structure is neither a pure oligopoly nor a fragmented aftermarket: the top three players hold a meaningful slice of market activity, and the top five expand that concentration further. Our concentration metrics indicate moderate consolidation among leading suppliers, but with substantial greenfield opportunity for firms able to prove platform capabilities and software integration. In practice this means suppliers with systems‑level competencies and strong OEM relationships will capture disproportionate value as switch functionality migrates into the vehicle’s software domain.
Profiles of representative suppliers illustrate typical strategic postures:
- Established HMI specialists have decades of experience delivering multifunction switch assemblies and are evolving toward capacitive, tactile, and hybrid solutions that integrate with vehicle electronics.
- Systems integrators and safety suppliers are converging steering hardware with active safety functions — recently announced foldable and steer‑by‑wire compatible wheel concepts reflect an effort to own both mechanical and electronic interfaces.
- OEM captive teams and tiered component makers are adopting modular platforms to reduce per‑model variation and shorten time to market for new HMI features.
While we profile specific companies in the full report — highlighting their go‑to‑market models, IP strengths, and recent product launches — this briefing intentionally omits proprietary scorecard ratings and revenue breakdowns to preserve the report’s role as a strategic intelligence asset.
Risk vectors and supply‑side dynamics
- Raw material and labor cost pressure — The industry is experiencing higher costs as electronics integration increases inside traditionally mechanical assemblies; suppliers must prioritize DFM and supply‑chain elasticity.
- Regulatory and safety hurdles — New form factors such as foldable wheels and steer‑by‑wire interfaces introduce complex certification pathways; early engagement with regulators and harmonized testing protocols reduces time to market.
- M&A and competitive escalation — Intensified consolidation activity is accelerating platform rollouts; companies that delay investment risk becoming feature suppliers rather than system owners.
What the full PW Consulting report delivers (practical contents)
Our full study is deliberately structured as an operational toolset for 2026 planning cycles. Highlights include:
- Quantitative market-sizing model (historical 2020–2025, base year 2025) and scenario forecasts through 2032, with downloadable model files in business‑ready format.
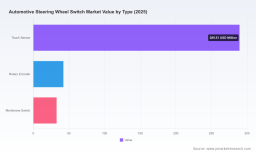
- Segment‑level forecasts across product types, applications and geographies (note: detailed segment tables are available in the full report).
- Supplier scorecards that blend financial, technical and go‑to‑market indicators — including patent strength, software stack maturity, and OEM relationships.
- Technology roadmap and R&D investment priorities for hardware, firmware, and sensor fusion required to support ADAS/AV and biometric HMI functionality.
- Commercial playbooks: sample sourcing contracts, modularity checklists, and cost‑breakdown templates for build vs buy decisions.
- M&A target screening criteria and integration risk matrices tailored to steering wheel switch portfolios.
- Regulatory and testing playbook aligned to emerging steering‑by‑wire and functional safety standards.
How to use the research in 2026 strategic planning
Use the report as both a forecasting asset and a tactical guide:
- Align product roadmaps with the six‑to‑twelve month windows for OEM platform freezes highlighted in the model; prioritize embeddable software and modular form factors in Q1‑Q2 2026.
- Run supplier procurement RFPs that evaluate OTA readiness, safety case documentation, and configurability rather than solely unit cost.
- Map M&A targets using our scorecard — prioritize deals that close capability gaps in sensor integration, embedded firmware, or platform tooling.
- Implement a short list of pilot programs (EV model, high‑trim variant, and retrofit concept) to validate new control concepts with live user testing and regulatory oversight.
Concluding perspective and next steps
The steering wheel switch is evolving from a well‑understood mechanical subassembly into a strategic, software‑aware control domain. For leaders setting 2026 priorities, the imperative is clear: invest in modular architectures, secure software and safety competencies, and pursue partnerships that accelerate time‑to‑platform. Our full Automotive Steering Wheel Switch Market study supplies the granular demand schedules, supplier financials, and prioritized action lists required to turn these imperatives into executable programs.
To access the complete dataset, supplier scorecards, and the downloadable forecasting model — including the segment breakouts and scenario analysis intentionally excluded from this briefing — visit the PW Consulting report page. The detailed intelligence will enable procurement, R&D and corporate development teams to make high‑confidence, time‑sensitive decisions in 2026.
For detailed analysis of this topic, please visit the official page: Automotive Steering Wheel Switch Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com