

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
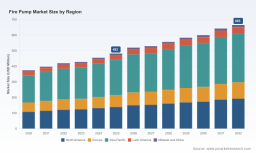
PW Consulting: Fire Pump Market to Reach USD 665 Million by 2032 at 4.96% CAGR

Fire Pump Market 2026: Strategic Imperatives for Resilient Growth
As PW Consulting’s lead industry analyst, I present an executive preview of our Fire Pump Market study — a high-resolution, decision-ready briefing designed to shape executive action in 2026. This preview surfaces the critical takeaways and strategic choices that will determine market leaders over the 2026–2032 outlook period, while retaining the detailed subsegment intelligence and model outputs for subscribers and clients who access the full report.
Fire Pump Market
Why this study matters for 2026 decision‑makers
-
Market momentum: With a 2025 base-year sizing and a compounded annual growth rate of approximately 4.96% across the 2026–2032 forecast window, the fire pump market is on a steady expansion path. This creates predictable revenue corridors for incumbents and a lower-risk entry platform for well-capitalized challengers.
Fire Pump Market -
Strategic inflection points: 2026 is no longer just another year of incremental investment. Converging forces — regulatory updates, raw-material volatility, rising demand for integrated and monitored systems, and selective project awards in energy and marine sectors — are accelerating decisions on supply‑chain footprint, product roadmaps, and aftermarket services.
Fire Pump Market -
Consolidation and differentiation: The market shows moderate concentration among the top players, leaving room for targeted M&A that can rapidly scale capabilities, channel reach, or technical breadth. Our CR3 and CR5 metrics indicate meaningful market share clustering at the top, while also leaving white space for specialized and regional players.
Market trajectory — what the headline numbers tell us
Using 2025 as the base year (revenues reported in USD Million), PW Consulting’s top‑line model projects continued growth through 2032. The forecast path reflects resilient end‑market demand across commercial, industrial, and marine applications, and assumes continued investment in fire protection driven by regulatory compliance and new construction activity. For strategy teams, the implication is clear: plan for steady volume growth, but position to capture disproportionate value through higher‑margin systems, services, and digital offerings.
Key dynamics shaping competitive advantage
-
Regulatory landscape and compliance: NFPA 20 remains the definitive guidance for stationary fire pump selection and installation, and changes to ASSE 15010 have begun to alter inspection and testing regimes since early 2025. Companies that embed compliance engineering and certification support into their commercial offers will shorten sales cycles and lower buyer friction.
-
Raw‑material volatility: Steel cost fluctuations are a near‑term operational risk. Recent market observations show notable price movement into 2026. Manufacturers with hedging strategies, multi-sourcing, or component redesigns that reduce steel intensity will defend margins more effectively.
-
Product architecture and system integration: Buyers increasingly prefer packaged pump skids, integrated control panels, and NFPA‑compliant system-level solutions. Suppliers that bundle engineering‑to‑commissioning services and offer clear total cost of ownership (TCO) propositions can command premium pricing.
-
Digitization and aftermarket services: Remote monitoring, predictive maintenance, and compliance reporting are becoming table stakes in major projects. Solutions like real‑time pump monitoring and automated testing logs materially reduce client operational risk and create recurring revenue streams.
-
Project concentration: Large contracts in energy and shipbuilding can materially shift supplier revenue in a given year. Winning these requires integrated project capability, global delivery networks, and demonstrated reference performance.
Competitive landscape — who matters and why
The competitive set spans global OEMs, regionally dominant manufacturers, and specialized niche suppliers. Core players include legacy pump manufacturers and integrated system suppliers; each brings a distinct pathway to growth:
-
Pentair: A global supplier with well‑known fire pump brands and a portfolio that spans horizontal and vertical configurations. Their strength lies in brand recognition and broad commercial channels.
-
Grundfos and Xylem: Large pump platforms that incorporate fire pump variants. Advantage: large installed base and global aftermarket networks.
-
Peerless Pump and Armstrong Fluid Technology: Known for engineered solutions and monitoring capabilities. Peerless’ monitoring offerings exemplify the shift toward data‑enabled aftermarket services.
-
Sulzer and Flowserve: Industrial incumbents positioned to capture energy and offshore opportunities through integrated skids and project execution capability.
-
Regional specialists — NAFFCO, Kirloskar Brothers, SPP Pumps, Waterous, CET Fire Pumps, Rosenbauer: These firms dominate specific geographies and end‑use niches (portable units, truck‑mounted systems, municipal supply) and act as distribution or partnership candidates for global players seeking local access.
Two recent developments illustrate where competition and demand are converging. In January 2026, Armstrong launched a new range of constant‑speed vertical‑in‑line fire pumps targeted at both 50Hz and 60Hz markets, reflecting demand for higher pressure ratings in packaged applications. In late 2025, Sulzer secured a multi‑skid contract linked to major FPSO projects, underscoring the premium for integrated delivery in energy sector programs. These moves highlight product innovation and project capability as decisive competitive levers.
Report deliverables — what you’ll get in the full study
Our full Fire Pump Market report is built as a practical playbook for strategy, commercial, and operations leaders. Key deliverables include:
-
Bottom‑up market sizing and validated revenue forecasts (2026–2032) with sensitivity scenarios mapped to commodity, regulatory, and construction cycle swings.
-
Segment analyses by region, type, and application, with buyer‑level demand drivers and replacement versus new‑build dynamics (note: detailed subsegment tables and share data are reserved for report subscribers).
-
Competitive profiles for the primary manufacturers, including capability matrices, channel footprints, R&D focus areas, and recent contract and product milestones.
-
Supply‑chain risk assessment with steel‑exposure modeling, multi‑sourcing options, and cost‑pass‑through scenarios for procurement teams.
-
Regulatory mapping showing NFPA and ASSE impacts on specification, testing regimes, and O&M obligations, plus country‑level compliance checkpoints for major markets.
-
Commercial playbooks: pricing levers, bid/no‑bid frameworks for large projects, and bundled services monetization templates.
-
M&A and partnership screening: a shortlist of targets and fit‑criteria to accelerate capability or geographic entry, supported by financial and strategic rationale.
Strategic recommendations for 2026
-
Prioritize aftermarket and digital services: Shift margin emphasis from hardware alone to subscription‑style monitoring, compliance reporting, and predictive maintenance. These services shorten payback for buyers and increase customer lifetime value.
-
Defend procurement with design‑to‑cost: Evaluate component redesigns and alternate materials to lower steel intensity where feasible, and implement forward contracts or indexed pass‑through clauses to manage volatility.
-
Target selective M&A: Use the moderate market concentration as cover to acquire niche specialists that add system integration, geographic access, or monitoring IP rather than broad roll‑up strategies that erode margins.
-
Embed compliance into the sales process: Offer NFPA‑aligned engineering packages, on‑site commissioning plans, and ASSE‑compliant testing services as differentiators in competitive tenders.
-
Build modular, packaged offers for project work: Prefabricated skids and tested packages reduce site risk and win larger, time‑sensitive contracts in energy and marine sectors.
-
Develop channel partnerships in high‑growth corridors: Strengthen relationships with system integrators, EPCs, and local service providers to capture installation and recurring service revenues.
What to expect from the full intelligence
This preview surfaces the strategic levers. The full PW Consulting Fire Pump Market report provides the granular analytics required to operationalize these recommendations: downloadable models, regional demand breakdowns, price and margin ladders, supplier scorecards, and country‑level regulatory checkpoints. Importantly, subsegment share tables and proprietary demand-driver elasticities are held in the full report to preserve client value and ensure you can act immediately with validated inputs.
Next steps — how to use this insight in Q1 2026
-
Immediate: Run a rapid profitability scan of your product portfolio to identify candidates for bundled service piloting and quick margin wins.
-
90‑day: Reassess supply‑chain contracts with steel suppliers and logistics partners; initiate design reviews to reduce exposure to raw‑material swings.
-
6‑9 months: Pilot a monitored service offering with a small cohort of clients in commercial and industrial verticals; use early telemetry to refine pricing and SLA structures.
-
12 months: If acquisition is in scope, begin diligence on targets that fill gaps in integration, digital monitoring, or regional presence — using our M&A fit framework to short‑list targets.
For commercial teams, regulatory leads, and strategy units preparing budgets and capital plans in 2026, this study converts market momentum into executable initiatives. To access the full dataset, segmented forecasts, and the supplier playbook that underpins the recommendations above, please consult PW Consulting’s full Fire Pump Market report and models.
For detailed analysis of this topic, please visit the official page: Fire Pump Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com