

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: EV Battery Market to Hit USD 100.09 Billion by 2032 at 3.82% CAGR

Electric Vehicles Battery Market — Strategic Outlook for 2026 Decision-Making
As companies prepare capital allocation, product roadmaps, and supply-chain commitments in 2026, the Electric Vehicles (EV) battery market presents a paradox: steady headline growth underpinned by volatile inputs and fast-moving technology inflection points. Our PW Consulting market study (base year 2025; forecast 2026–2032) projects the global EV battery market to expand from USD 76.99 Billion in 2025 to roughly USD 100.09 Billion by 2032, representing a compound annual growth rate (CAGR) of approximately 3.82%. These headline figures conceal a high degree of tactical risk and strategic opportunity that corporate leaders must reconcile this year.
Electric Vehicles Battery Market
Why this study matters for 2026 strategy
-
Timing of investment decisions. With manufacturing lead times measured in quarters and multi-plant investments spanning years, 2026 is the inflection point for firms that want to influence the supply curve through 2030. Our analysis converts horizon projections into time-phased investment triggers and capex-to-return profiles tailored for OEMs, cell producers, and Tier‑1 suppliers.
Electric Vehicles Battery Market -
Supply‑chain shock preparedness. Raw-material volatility and regulatory intervention—not long-term demand—are driving short-term dislocations. The study quantifies how price shocks, export controls, and quota mechanisms translate into margin compression and capacity reallocation scenarios.
Electric Vehicles Battery Market -
Commercial differentiation. The next wave of commercial wins will hinge less on capacity alone and more on chemistry choice, modular system design, charging profiles, and lifecycle economics. The report isolates where differentiation unlocks premium pricing or reduces total cost of ownership for buyer segments.
How to read the headline numbers
The market trajectory shown above reflects aggregate revenue across cell formats, pack integration, and aftermarket services. Growth is positive but decelerates relative to earlier post-pandemic rebounds—illustrating a maturing market where technology cycles, regulatory shifts, and raw-material cycles now dictate winners and losers. Importantly, while overall demand grows toward 2032, our scenario work highlights years of near-term churn where capacity reallocation and chemistry substitution materially affect regional availability.
Key dynamics shaping 2026 decisions
-
Regulatory and policy friction. Changes in tariff regimes and sourcing rules have tangibly shifted purchasing behavior in 2025–2026. In particular, U.S. policy changes around EV tax credits and tightened import scrutiny materially altered incumbent procurement patterns. Concurrently, export controls and restrictions on select battery components introduced from 2023 and updated through late 2025 remain a persistent downside risk to cross-border flows and just-in-time supply models.
-
Raw‑material volatility. Cobalt and lithium price spikes in late 2024–early 2026 have re-opened input-cost debates across cathode chemistries and recycling economics. Cobalt price moves and lithium re-pricing have already driven procurement teams to re-evaluate long-term contracts, spot exposure, and vertical integration options.
-
Chemistry and format evolution. Rapid commercialization cycles for novel chemistries and form factors (including sodium-ion and condensed high‑energy designs) are forcing OEMs and cell suppliers to balance near-term cost advantages with long-term technological optionality.
-
Capacity reallocation. Several large manufacturers repurposed gigawatt-hours of capacity toward specific chemistry lines in 2025. That shift reduced availability of other chemistries in the short term and introduced opportunities for agile entrants to capture displaced demand.
Competitive landscape: profiles and strategic postures
The market remains moderately concentrated at the top: the three largest suppliers account for a majority share of industry revenue, and the top five firms represent a significant portion of supply capability. Competitive behavior in 2026 will revolve around differentiated chemistries, localized manufacturing, and integrated OEM partnerships. Below is an executive read on the firms we consider pivotal for 2026 planning.
-
CATL (Ningde, China) — World-leading scale, aggressive chemistry roadmap. CATL combines LFP, NCM, advanced condensed-cell designs, and now sodium-ion commercialization. Recent launches emphasize ultra‑long range and rapid charge cycles, signaling a strategy to own both high-energy and cost-leading segments across fleet and passenger applications.
-
BYD (Shenzhen, China) — Proprietary cell-pack integration and vertical control. BYD’s blade battery and system-level integration continue to emphasize safety and charge-performance trade-offs, supporting both captive vehicle production and selective third‑party supply agreements.
-
LG Energy Solution (Seoul, South Korea) — Format diversity and near-market capacity expansion. LGES is extending its footprint in North America and Europe with cylindrical and pouch formats targeted at high-volume OEMs. The firm’s strategic moves are focused on supply locality and long-term contractual relationships.
-
Panasonic Energy (Osaka, Japan) — Cylindrical-cell specialist with deep OEM ties. Panasonic’s emphasis on multiple cylindrical form factors positions it to serve segments prioritizing energy density and production familiarity, notably in North America and Japan.
-
SK On (Seoul, South Korea) — High‑nickel NCM capability and US facility investments. SK On aims to capture early volumes through targeted OEM partnerships and localized manufacturing to reduce cross-border exposure.
-
Samsung SDI (Yongin, South Korea) — Technology-focused supplier moving into premium OEM programs. Recent multi‑year supply agreements with luxury OEMs highlight a move toward high-performance chemistry and system integration.
-
EVE Energy (Huizhou, China) — Prismatic cell player with flexible product mix. EVE targets EV and energy storage markets with a focus on prismatic LFP and NCM cells, leveraging agility in product customization.
-
Northvolt (Stockholm, Sweden) — Sustainability and European nearshoring. Northvolt’s emphasis on low‑carbon production and regional supply addresses OEMs with stringent sourcing and lifecycle-emissions requirements.
Recent signals that should change board-room priorities
-
Product innovation is accelerating: a leading supplier commercialized condensed high‑energy cells and introduced mass-produced sodium-ion variants in early 2026—moves that force OEMs to re-assess platform compatibility and warranty risk.
-
Supply agreements are consolidating premium relationships: long‑term offtake deals with luxury OEMs illustrate a two‑track market where scale players lock in volume while others pursue specialized, higher‑margin niches.
-
Policy and sourcing shifts are non-linear: regulatory moves in 2025 effectively reshaped chemistry adoption in major markets and caused reallocations of existing plant capacity toward lower-cost chemistries; this dynamic is expected to recur as policy cycles continue.
Report deliverables — practical tools for 2026 execution
-
Time‑phased demand model (2026–2032) with scenario toggles for policy, price shocks, and adoption curves—designed to produce capex trigger points for greenfield, brownfield, and conversion projects.
-
Supply‑side playbook mapping incumbent manufacturing footprints, near‑term capacity projects, and idiosyncratic constraints such as precursor bottlenecks.
-
Raw‑material sensitivity and hedging matrix that links price movements in lithium, cobalt, and precursor chemicals to margin scenarios at cell and pack levels.
-
Competitive scorecards and rapid-entry checklists for JV, M&A, and technology-licensing pathways—focused on minimizing execution risk in cross-border deals.
-
Commercial negotiation templates for long‑term offtake, technology supply, and recycling offtake that incorporate dynamic price floors and supply‑assurance clauses.
Recommended 6‑month agenda for executive teams
-
Run three market scenarios (baseline, policy‑tight, and material‑shock) against existing product roadmaps; identify which product programs to accelerate, pause, or sunset.
-
Prioritize supply diversification where single‑source exposure aligns with high-cost inputs or politically sensitive origins. Where diversification is infeasible, convert spot exposure to indexed long‑term contracts with contingency clauses.
-
De-risk manufacturing through flexible lines that enable chemistry conversion within defined engineering and capex envelopes.
-
Lock pre-competitive partnerships addressing precursor processing, recycling, and reuse to reduce vulnerability to export controls and quotas.
-
Elevate battery-system IP and software monetization: differentiate on thermal management, fast‑charging algorithms, and second-life services rather than chemistry alone.
Where the report intentionally holds back — and why
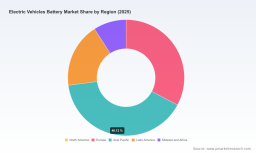
In line with our “trailer” principle, this introduction establishes the strategic context and primary levers executives should consider in 2026. To preserve competitive value for subscribers and engage commercial dialogue, the full report contains granular regional and application splits, model inputs, and downloadable scenario spreadsheets that are not reproduced here. These withheld items include detailed percentage shares by region, chemistry and application, and the time‑phased capacity tables that drive our supply‑demand balances.
Final note: action vs. observation
Headline growth alone will not protect margins or strategic position in 2026. Boards and executive teams must translate the macro trajectory into actionable toggles—finance, sourcing, manufacturing, and commercial—that can be implemented within quarter-level timeframes. Our report translates the USD 2025 baseline and the 2026–2032 forecast into the specific playbooks companies need to move from observation to execution.
To access the full dataset, scenario workbooks, and company benchmarking dashboards that underpin this strategic summary, visit our Electric Vehicles Battery Market study page or contact a PW Consulting engagement lead for a tailored briefing.
For detailed analysis of this topic, please visit the official page: Electric Vehicles Battery Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com