

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: PGMEA electronic materials market to expand at 6.2% CAGR through 2032

Strategic Outlook 2026: PGMEA for Electronic Materials — A Tactical Primer for Decision-Makers
Executive summary
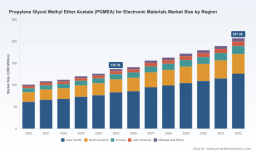
Propylene Glycol Methyl Ether Acetate (PGMEA) has evolved from a niche solvent to a strategic input in the electronics value chain. Between 2020 and 2025, the PGMEA market expanded materially, and our base-year analysis (2025) shows the market at approximately USD 136.78 Million. PW Consulting’s forecast projects a compound annual growth rate (CAGR) of 6.2% for 2026–2032, driving a continued upward trajectory through the forecast horizon. For executives planning capital allocation, procurement strategies, or M&A activity in 2026, this study translates macro growth into concrete tactical choices — while reserving the granular segment-level matrices for full-report subscribers.
Propylene Glycol Methyl Ether Acetate (PGMEA) for Electronic Materials Market
Why this matters for 2026 decisions
-
Timing matters. The projected 6.2% CAGR over 2026–2032 implies demand expansion sufficient to support both incremental capacity and targeted premiumization strategies. Firms that move earlier to secure supply, differentiate product grades, or lock in strategic partnerships will capture disproportionately higher margin pools.
Propylene Glycol Methyl Ether Acetate (PGMEA) for Electronic Materials Market -
Purity premium dynamics. Electronic-grade PGMEA continues to command a meaningful price premium versus industrial grades because of ultra-low impurity thresholds required by semiconductor and advanced-display processes. Pricing dynamics for these grades define margin and supplier negotiation levers for OEMs and specialty chemical suppliers alike.
Propylene Glycol Methyl Ether Acetate (PGMEA) for Electronic Materials Market -
Regulatory and ESG pressures will reshape sourcing. Tightening emissions rules in North America and Europe, alongside regulatory controls such as pre-manufacture notifications under the U.S. Toxic Substances Control Act for novel grades, create both compliance obligations and barriers to entry — factors that should be baked into due diligence and business case models in 2026.
Market dynamics and risk signals
Several cross-cutting dynamics will determine supply, pricing, and strategic posture over the next 18–36 months:
-
Upstream feedstock volatility — Propylene oxide and acetic acid are the principal inputs for PGMEA. Price volatility in these feedstocks transmits quickly to production costs and, therefore, to negotiated prices with electronics manufacturers. Procurement teams must integrate active feedstock hedging, supplier cost-pass mechanisms, and scenario-based cost models into 2026 contracting.
-
Regional supply asymmetries — Asian producers are the dominant physical suppliers of PGMEA to the global electronics industry. Freight, insurance, and tariff considerations create effective regional price differentials. Buyers seeking price stability or greenfield investments should analyze regional logistics and customs exposures as part of capacity-planning decisions.
-
Regulatory tightening — North American and European environmental rules are increasing compliance costs for manufacturers and downstream formulators that use PGMEA in coatings and chemical processes. Compliance capital, monitoring systems, and emissions-control technology investments need line-item consideration in 2026 budgets.
-
Market concentration — The PGMEA industry exhibits meaningful concentration among a handful of global players. Current concentration metrics indicate that the three largest suppliers control a majority share of the market, and the top five collectively hold a significant portion. This structure amplifies the strategic value of bilateral supplier relationships, long-term contracts, and targeted co-investment arrangements.
-
Price points for high-purity grades — Electronic-grade PGMEA commands a premium in the market due to stringent quality specifications for semiconductor manufacturing. Buyers and sellers must incorporate grade-differentiated pricing and quality assurance clauses into commercial terms.
Competitive landscape: capabilities and strategic moves
The competitive field is populated by global chemical majors and specialty producers that blend scale, integrated feedstock access, and high-purity manufacturing capability. Key participants include Dow Inc., Eastman Chemical Company, LyondellBasell, Shell, BASF, KH Neochem, and Shinko Organic Chemical Industry. Our analysis highlights several strategic positions:
-
Integrated feedstock advantage: Large integrated producers leverage propylene-based operations to optimize cost curves and resilience during feedstock shocks. This offers them a defensive margin advantage especially on industrial-grade volumes.
-
Specialty-purity differentiation: Certain suppliers focus on ultra-high-purity electronic grades supported by dedicated manufacturing lines, rigorous QA/QC, and tailored logistics. These capabilities underpin premium pricing and sticky customer relationships in semiconductor supply chains.
-
Recent capacity moves: Strategic capacity expansions in Asia (e.g., notable investments by Eastman in 2025 to meet rising high-purity demand in electronics) signal supplier intent to capture the premium electronic-grade segment and indicate an emerging competitive battleground in the region.
-
Service and co-development plays: Market leaders are pairing supply with formulation support, consignment stock models, and collaborative qualification programs to accelerate customer adoption and shorten procurement cycles in complex electronics applications.
Strategic playbook for 2026 — actions that create optionality
Based on scenario modelling and supplier capability assessments, we recommend a pragmatic, staged approach to secure market position and capture margin upside in 2026:
-
Prioritize grade segmentation in sourcing: Distinguish contracts for electronic-grade vs industrial-grade volumes. Electronic-grade requirements justify longer-term, higher-trust partnerships and tighter service-level agreements; industrial-grade volumes are suitable for spot or index-linked procurement.
-
Hedge upstream exposure: Implement layered hedging strategies for propylene oxide and acetic acid where feasible, or negotiate cost-pass and formula-based pricing clauses with key suppliers to share feedstock risk.
-
Strengthen qualification pipelines: For semiconductor and advanced-display customers, shorten qualification cycles by investing in joint qualification labs, shared test protocols, and pre-approved vendor lists to reduce time-to-supply.
-
Evaluate nearshoring vs. hub strategy: For companies sensitive to freight/tariff volatility and regulatory divergence, nearshoring select capacity or establishing regional fill-and-pack hubs can lower landed cost and mitigate supply disruption risk.
-
Embed regulatory capital plans: Anticipate emissions-control and reporting requirements in North America and Europe by budgeting for abatement equipment, monitoring systems, and compliance expertise in 2026 CAPEX planning.
-
Explore bolt-on M&A and JV opportunities: Given the market’s measured concentration, small-to-medium transactions — especially those that add high-purity manufacturing lines or regional footprint — can accelerate market access with limited greenfield timeline risk.
-
Develop sustainability and substitution pathways: Pursue low-VOC formulations, solvent-recovery systems, and R&D into alternative solvents or blends to de-risk potential regulatory constraints and appeal to environmentally conscious OEMs.
What PW Consulting’s full report provides (practical components)
The full PW Consulting PGMEA for Electronic Materials market study is designed as a decision-ready resource for corporate strategists, procurement leaders, and investors. Highlights include:
-
Robust market sizing and historical time series (2020–2025) and a transparent forecast model through 2032 built on a 6.2% CAGR baseline.
-
Demand-driver decomposition, with use-case dynamics for semiconductor wafer processing, IC packaging, and advanced displays, plus sensitivity runs for key end-market scenarios.
-
Supply-side mapping with plant-level capacity intelligence, lead-times, purity capabilities, and an annotated supplier scorecard covering technology, geographic footprint, and commercial strategies.
-
Price and margin modeling that links feedstock pricing to finished-product economics, including recommended contracting structures and sample negotiation clauses.
-
Regulatory matrix and compliance playbook covering pre-manufacture notification requirements, emissions regulation impacts, and recommended compliance investments by jurisdiction.
-
Actionable go-to-market and procurement playbooks: supplier segmentation, inventory optimization templates, and a 90–180 day operational plan for implementation.
-
Scenario-based investment cases for capacity expansion, strategic JV structures, and M&A candidates — with IRR, payback, and risk-adjusted valuations under multiple market scenarios.
-
Appendices with data tables, methodology notes, and a detailed glossary to speed internal adoption of findings.
Takeaway and next steps
For 2026, PGMEA represents a specialty-chemicals opportunity where technical differentiation, supply security, and regulatory foresight create durable competitive advantages. The market’s projected growth provides cover for targeted investments, but the timing and structure of those investments are sensitive to feedstock volatility, regional logistics, and regulatory shifts.
PW Consulting’s full study contains the granular segment matrices, regional and application-level demand analytics, and supplier-specific metrics required to build precise procurement and investment models. This preview intentionally omits those granular tables to protect competitive insights — but the full report provides them in downloadable form along with scenario-ready financial models and contract templates.
How to engage
-
Commission a briefing: Arrange a 60–90 minute workshop with our PGMEA team to translate findings into an actionable 2026 roadmap tailored to your portfolio.
-
Request the full dataset: Subscribers receive the detailed segmentation tables, supplier scorecards, and the working forecast model to run custom scenarios.
-
Start a pilot: For procurement or R&D teams, PW can design a 12-week pilot to validate supplier qualification, establish hedging mechanics, or scope a nearshoring study.
Contact PW Consulting to convert this industry momentum into strategic advantage. The macro trajectory is clear; the competitive edge will come from how quickly and precisely organizations translate these dynamics into contracts, capacity, and compliant, high-purity supply chains.
For detailed analysis of this topic, please visit the official page: Propylene Glycol Methyl Ether Acetate (PGMEA) for Electronic Materials Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com