

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
Irrigation Controllers Market Poised for 8.82% CAGR Through 2032 — PW Consulting

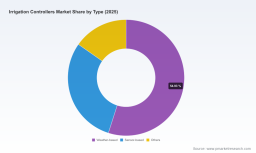
Irrigation Controllers Market 2026: Strategic Imperatives for Executive Decision‑Makers
Executive snapshot
By 2025 the global irrigation controllers market had reached an inflection point. After steady expansion from a clear five‑year baseline, the market stood at approximately USD 260 Million in 2025 and—supported by automation, regulatory pressure, and municipal incentives—is projected to grow at a compound annual growth rate (CAGR) of roughly 8.82% through our 2026–2032 forecast window. Under PW Consulting’s scenarios, that trajectory pushes the market toward a materially larger opportunity by the end of the decade, reflecting both increased unit penetration and higher average selling prices as smart, sensor‑enabled solutions proliferate.
Irrigation Controllers Market
Why this matters for 2026 decisions
- Timing: 2026 is the pivot year when several regulatory, procurement and rebate dynamics converge, materially changing buyer economics for end users and procurement cycles for installers, OEMs, and distributors.
- Capital allocation: Companies planning product investment, M&A, or channel expansion need a near‑term evidence base that ties expected revenue upside to unit economics, not just surface level adoption metrics.
- Risk management: Tariff, certification, and municipal rebate changes are creating a bifurcated cost environment; margins and supply chain choices made in 2026 will influence competitiveness for the next five years.
Market trajectory & what the headline numbers hide
The headline figures—from a 2020 baseline to approximately USD 260 Million in 2025, and continuing at a near 9% CAGR through our forecast—tell a straightforward growth story. But beneath the topline are accelerants and constraints that matter to strategy teams:
Irrigation Controllers Market
- Technology migration: A structural shift toward internet‑connected, weather‑ and sensor‑integrated controllers is increasing average selling prices and creating new service and data revenue opportunities for OEMs and integrators.
- Commercialization rhythm: Adoption remains uneven across buyer segments and channels; the near term is dominated by retrofit demand and municipal/commercial projects tied to rebate windows, while residential and agriculture digitalization follow separate adoption curves.
- Concentration and competitive dynamics: The market shows meaningful concentration among a small set of suppliers (CR3 ~62.5%, CR5 ~78.2%), which creates both defensive pressures for incumbents and entry opportunities for new entrants with differentiated value propositions.
PW Consulting’s full study dissects these layers with scenario models that convert the topline CAGR into quantified outcomes under varying assumptions for rebate rollout, certification adoption, and component cost inflation.
Irrigation Controllers Market
Regulatory and incentive forces shaping 2026
Several regulatory and programmatic events are altering the economics of irrigation controls—affecting product design parameters, procurement cycles, and the available margin pool for manufacturers and channel partners.
- Certification & labeling: An update to WaterSense criteria in early 2026 tightens independent certification requirements for controllers, raising the bar for product performance and opening preferential procurement channels for certified devices.
- Municipal rebates: Emerging municipal rebate programs in the US are accelerating retrofit demand by lowering first‑cost barriers for end users and creating a new sales lever for installers and OEMs. These programs often prescribe specific certification and documentation workflows, which affects go‑to‑market design.
- Procurement shocks: Trade actions implemented in 2025—specifically tariffs on steel and aluminum—have increased components and assembly costs for manufacturers, pressuring margin unless passed through or offset by operational gains.
- Federal sector validation: Evidence cited by federal programs indicates that advanced controllers can achieve 15%–40% water use reductions in institutional settings, establishing a high‑value reference case that many states and municipalities are now using to justify incentive schemes.
Competitive landscape: what leading vendors are doing
The market is anchored by a set of established players that balance legacy installed bases, channel relationships, and newer software‑driven offerings. Below is a synthesized strategic read on each major competitor covered in our research (profiles and sources are included in the full report):
- Hunter Industries — Strong in smart Wi‑Fi and internet‑connected residential and commercial controllers, Hunter leverages product families that integrate cloud services and third‑party ecosystem compatibility. Strategic consideration: defend installed base with subscription‑friendly services and expand enterprise telemetry to capture recurring revenue.
- Rain Bird Corporation — A modular product approach gives Rain Bird flexibility across retrofit and OEM channels. Rain Bird’s portfolio strategy suggests opportunities in platform modularity and certified retrofit kits; partner‑enablement and installer economics are key levers.
- The Toro Company — Toro’s central control offerings target higher‑value commercial landscapes and large‑scale properties. Toro’s updated 2026 catalog points to product rationalization and pricing strategies that will affect enterprise procurement cycles.
- Netafim — With a heritage in precision agriculture, Netafim’s controllers and digital farming tools are positioned for irrigation efficiency gains in specialty crops and drip systems. For Netafim, scaling connectivity services and analytics is the near‑term priority.
- Galcon — Galcon’s cross‑segment product breadth—residential through golf—gives it nimbleness in channel play. The company can leverage specialization in niche applications to capture premium margins where standard controllers under‑perform.
- HydroPoint Data Systems — Positioned as a data and services provider, HydroPoint couples weather‑based control with analytics. Its route to growth is through expanded SaaS deployment and integration with municipal water management programs.
Each competitor’s strength map is detailed in the report with scorecards across product, channel, service capabilities, and buy‑box economics—providing a direct template for partnership, M&A targets, or defensive playbooks.
Operational implications for manufacturers and channel partners
From a go‑to‑market and operations lens, 2026 requires concrete actions rather than high‑level intent:
- Product roadmap: Prioritize certification pathways, OTA update architectures, and modular hardware platforms that minimize SKU complexity while enabling localized rebate compliance.
- Cost and supplier management: Reassess material sourcing and component design to mitigate tariff exposure; consider verticalization or near‑shoring for critical assemblies.
- Channel economics: Redesign installer incentives to reflect rebate processing complexity and subscription conversion potential; align distributor stocking with program seasonality to avoid inventory shortfalls.
- Services & data monetization: Build analytics products that can be bundled with controllers to deliver short‑term ROI claims to institutional buyers (demonstrated water savings can directly unlock municipal and federal procurement).
What PW Consulting’s report delivers (practical, actionable content)
Our report is structured around board‑level decision needs and day‑to‑day execution. Highlights include:
- Transparent market sizing and validated growth scenarios (base year 2025; forecast 2026–2032) with sensitivity runs tied to rebate penetration, certification adoption, and component cost trajectories.
- Demand‑side buyer economics by segment (residential, commercial, agricultural) and the install/use/certify workflows that drive purchase decisions—presented as executable playbooks for product managers and sales leaders.
- Competitive scorecards and partner maps for leading vendors, plus a pipeline of potential disruptors observed at recent industry events.
- Supply chain and cost impact analysis: material cost elasticity, tariff scenarios, and procurement response options with prioritized vendor negotiation tactics.
- Regulatory impact matrix: a concise view of certification, rebate, and code changes—tied to fast action checklists you can deploy within 60–120 days.
- Financial templates: go/no‑go investment calculators, ROI models for subscription offerings, and a short list of high‑probability M&A targets with rationale (only summarized here; full profiles in report).
Signals from the field
Recent industry activity reinforces the strategic cues above. Trade shows co‑located with major water industry events are creating concentrated buyer exposure for controllers and connected services. Startup competitions at industry events have accelerated interest in low‑power cellular and alkaline battery designs suitable for remote agricultural sites. Meanwhile, catalog and pricing updates from leading vendors in early 2026 reflect tightening component supply and pricing discipline.
How to use this research in 90 days
- Immediate (0–30 days): Run the PW Consulting rebate/ROI tool for your top five SKUs and identify which SKUs become rebate‑eligible under WaterSense updates.
- Short term (30–90 days): Execute supplier re‑quotes under tariff scenarios and update channel margin agreements to reflect rebate processing costs. Pilot one subscription analytics offering on a closed commercial account to validate recurring revenue assumptions.
- Board level (60–120 days): Present a 12‑month product and M&A roadmap tied to the report’s scenario outcomes; include contingency thresholds that trigger price increases or CAPEX deferral.
Conclusion — the strategic choice for 2026
The irrigation controllers market presents a clear growth runway, but the competitive and regulatory landscape now rewards execution precision. In 2026, firms must make three linked choices: (1) invest selectively in certified, connected product platforms; (2) realign channels and pricing to capture incentive‑driven retrofit demand; and (3) de‑risk supply chains against tariff volatility. PW Consulting’s full market study turns these strategic imperatives into operational checklists, competitive scorecards, and financial models.
Next steps
For executives preparing 2026 budgets and strategic plans, the full PW Consulting irrigation controllers market report contains the proprietary segmentation, regional and application breakdowns, and vendor financial proxies that underpin the scenarios summarized here. This article deliberately omits detailed sub‑segment figures to preserve the report’s role as an actionable decisioning resource. Contact PW Consulting to obtain the complete dataset, scenario models, and one‑to‑one briefings tailored to executive and operational teams.
For detailed analysis of this topic, please visit the official page: Irrigation Controllers Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com