

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Full-Body Scanner Market to Expand at 9.8% CAGR Through 2032

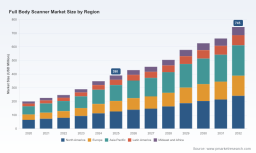
Full Body Scanner Market 2026: Strategic Imperatives for Procurement, Deployment and Competitive Positioning
As global security architectures evolve under pressure from passenger flows, mass events and shifting public-safety mandates, full body scanners have moved from niche checkpoint enhancements to core infrastructure investments. PW Consulting’s latest Full Body Scanner Market study—anchored on a 2025 base year and a seven-year forecast horizon (2026–2032)—translates the market’s structural trajectory into practical decision levers for enterprise leaders and public-sector procurement teams planning in 2026.
Full Body Scanner Market
Why 2026 is a Pivotal Year for Enterprise Decisions
Two factors converge to make 2026 a strategic inflection point. First, the market’s medium-term growth path is robust: our topline model shows a steady compound annual growth rate (CAGR) of 9.8% across the 2026–2032 forecast window, with the global market rising from the 2025 base to materially higher levels by 2032. Second, regulatory and event-driven procurement cycles—illustrated by updates to checkpoint standards and high-profile security contracts—are compressing typical purchase timelines and shifting decision criteria from pure cost to lifecycle assurance, throughput optimization and compliance resilience.
Full Body Scanner Market
What This Means for Buyers and Investors
- Procurement timing matters: With accelerated certification updates and event-specific rollouts, 2026 procurement calendars must move beyond annual tender cycles. Buyers who align capex plans with certification roadmaps and contract windows will secure preferential pricing and integration lead time.
- Retain optionality in technology selection: The market is expanding across distinct technology families. But vendors’ differentiation increasingly rests on software—AI threat detection, privacy-preserving image processing, and systems integration—rather than on device hardware alone. Procurement specs should therefore prioritize modular software licensing, upgrade paths and third-party interoperability.
- Operational total cost of ownership (TCO) beats unit price: Throughput, false alarm rates, maintenance contracts and data governance liabilities will dominate operational costs. The optimal 2026 acquisition will optimize across these axes, not merely minimize sticker price.
Market Scale and Growth: The High-Level Picture
Our market-size model, compiled from 2020–2025 historicals and forward forecasts for 2026–2032, provides a clear top-line growth narrative. Using USD as the reporting currency and expressing revenues in millions, the market’s expansion at a near-double-digit CAGR underlines the substantive commercial opportunity and the steady replacement-plus-new-install base that procurement teams must plan for. While the full report contains granular annual tables and scenario-based revenue runs, the strategic takeaway is simple: the addressable market enlarges consistently over the next decade, creating both vendor opportunity and buyer choice complexity.
Full Body Scanner Market
Competitive Landscape: Leaders, Challengers and Market Structure
The competitive map is characterized by globally recognized engineering-centric players and a widening field of specialized entrants focused on software and niche form factors. Market concentration remains low relative to other security segments—our concentration metrics indicate a fragmented landscape where the top three and top five vendors together account for a modest share of industry revenue—pointing to sustained vendor competition and frequent procurement dislocations in price and service terms.
Three vendors merit special attention in 2026:
- Smiths Detection (Hemel Hempstead, United Kingdom): Known for transmission X‑ray people screening systems, Smiths’ B-SCAN series emphasizes non-invasive detection of concealed threats. Their engineering heritage and long-standing airport relationships make them a pragmatic choice where X‑ray throughput and object characterization are procurement priorities.
- Rohde & Schwarz (Munich, Germany): Their QPS Walk2000 and QPS201 millimeter-wave systems combine walk-through coverage with AI-assisted detection of metallic and non-metallic objects. Notably, Rohde & Schwarz’s millimeter-wave approvals and 2026 contract awards tied to major event and airport deployments underscore their momentum in certificated, high-throughput solutions.
- Leidos (Reston, Virginia, United States): With the Pro:Vision people screening family, Leidos packages high-throughput, non-ionizing screening solutions geared to airports and high-traffic checkpoints. Their certification achievements and emphasis on throughput-focused designs position them strongly for large-scale checkpoint modernization programs.
Each of these vendors brings distinct strengths—hardware pedigree, regulatory-certified offerings, or integration scale—that procurement teams should weigh against operational priorities. The full report includes a vendor scorecard and a procurement readiness matrix that aligns vendor capabilities with common buyer decision profiles.
Regulatory and Event Dynamics Reshaping the Market
Regulation and major events are the primary accelerants of demand. Certification milestones have immediate procurement implications: devices that secure regional aviation-approved detection capabilities or new national standards often become default specifications in tenders. Likewise, major global events and concentrated security upgrades (airports, corrections facilities, critical infrastructure) create clustered demand waves that upset typical supply lead times.
For example, the emergence of newly certified walk-through millimeter-wave systems and updates to checkpoint guidance have tightened the window for deployments that must meet both throughput and compliance objectives. Meanwhile, legislative actions at state levels that authorize body imaging in new operating environments are broadening addressable markets outside traditional aviation use cases.
Technology and Integration Trends to Watch in 2026
- AI-first detection: Machine-learning models that reduce false positives and adapt to local threat profiles are becoming the decisive differentiator.
- Privacy-preserving imaging: Systems that separate threat cues from identifiable imagery, and that support auditable anonymization and data minimization, will gain preferential procurement consideration in privacy-sensitive jurisdictions.
- Systems interoperability: Integration with access control, video analytics and centralized command-and-control platforms is increasingly required by large-scale operators.
- Service-as-a-Platform offerings: Outcome-based maintenance and analytics subscriptions are reshaping vendor revenue models and buyer budgeting practices.
Operational Risks and Mitigations for 2026 Procurement
Key operational risks center on supply lead times, certification timing, and obsolescence of detection algorithms. To mitigate these risks, 2026 procurement strategies should include staged rollouts, contractual SLAs tied to certification milestones, and modular upgrade clauses for software and sensor modules. Our report provides a risk-quantified procurement playbook and model contract language designed to protect buyers against delayed certification or vendor lock-in.
What the Full Report Delivers (Executive to Tactical)
PW Consulting’s full study converts our high-level findings into hands-on tools for 2026 decision-makers. Notable deliverables include:
- Detailed historical time series (2020–2025) and an itemized forecast (2026–2032) with scenario variants keyed to adoption and regulatory outcomes;
- Vendor scorecards, comparative technical matrices and procurement readiness assessments;
- Operational models to estimate throughput, false alarm impact, lifecycle maintenance and staffed operating costs;
- Event-driven procurement playbooks (e.g., mass-event airport deployments), including logistics, staging and integration checklists;
- Compliance tracker and certification timelines that map device approvals to regional procurement windows;
- Financial templates for capex approval, vendor TCO comparisons and five-year depreciation models;
- Strategic scenario planning tools that allow buyers to stress-test procurement choices against certification shifts, supply constraints and event-driven demand surges.
To preserve actionable advantage for report subscribers, the full document also contains the granular regional, application and device-type splits that inform our segmentation-based recommendations. Those tables and the vendor-specific revenue models are intentionally reserved for the full subscription so that clients can act from privileged, granular intelligence.
How to Use This Insight in 2026 Planning
- Align procurement windows with certification calendars: Prioritize vendors whose certification timelines match your deployment dates.
- Specify modularity in RFQs: Insist on software upgrade guarantees and interoperability standards to future-proof investments.
- Model operational impacts: Use throughput and false-alarm scenarios to size staffing and downstream screening procedures.
- Negotiate outcomes, not just equipment: Capture service-level and performance-based clauses to manage long-term costs.
- Prepare for event-driven surges: For organizations exposed to major events or seasonal peaks, include contingency clauses and rapid-deployment options in contracting.
Closing Perspective: From Analysis to Action
In 2026, decisions on full body scanners will be as much about governance, integration and total cost as they are about sensor performance. The market’s growth path and the regulatory cadence create windows of advantage for buyers who act decisively and with a clear procurement strategy. PW Consulting’s Full Body Scanner Market study equips security leaders with the scenario-tested insights, vendor intelligence and procurement tools necessary to convert market growth into resilient capability.
For procurement teams, CISOs and infrastructure planners ready to convert this intelligence into a defensible procurement strategy, PW Consulting’s full report contains the quantitative models, vendor scorecards and deployment playbooks required to act in 2026. Detailed segmentation tables and downloadable financial models are available in the subscriber edition.
For detailed analysis of this topic, please visit the official page: Full Body Scanner Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com