

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
Automotive Steel Market to hit USD 163.64M by 2032; 3.1% CAGR (2026-2032) - PW Consulting

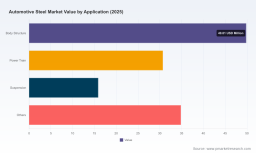
Automotive Steel Market: Strategic Imperatives for 2026 Decision‑Makers
As PW Consulting’s Senior Strategic Advisor and Chief Industry Analyst, I present a forward‑looking synthesis of the Automotive Steel Market that will matter to executives making investment, procurement, and product‑development choices in 2026. This briefing frames the key strategic tensions, supply‑side dynamics, competitive moves, and the practical playbooks required to navigate an industry that is neither contracting nor booming but evolving steadily. The base year for our modeling is 2025; the historical window is 2020–2025 and our forecast horizon runs 2026–2032. Over that forecast period the market tracks to a compound annual growth rate (CAGR) of 3.1% (USD, revenue unit: Million), with modelled market totals and scenario bands available in the full report.
Automotive Steel Market
Why this market matters in 2026
Automotive steel remains the linchpin of vehicle structural integrity, safety systems, and cost‑efficient lightweighting. For OEMs, tier‑1 suppliers and steel producers, decisions made in 2026 about capacity allocations, contractual structures and technology roadmaps will determine competitiveness through at least 2030. The market’s profile to 2025 shows material recovery from the disruptions of the early 2020s and a measured upward trajectory thereafter: PW’s topline series uses 2025 as the base year and projects steady expansion across the forecast window, providing a predictable backdrop for strategic planning (details and time‑series tables are in the full dataset).
Automotive Steel Market
High‑level market anatomy
-
Stability with moderate growth: Our forecast assumes a mid‑single‑digit CAGR in volumes and value through 2032, reflecting demand resilience from light‑vehicle production, fleet replacement cycles and incremental material substitution for lightweighting.
Automotive Steel Market -
Consolidation and concentration: Market concentration remains meaningful; the top three players control a material share of supply and the top five raise that to a more dominant position. This structural reality creates bargaining asymmetries that buyers and smaller producers must plan around.
-
Capital intensity and allocation choices: New capacity additions, relines for advanced high‑strength grades, and galvanizing lines continue to be the primary levers steelmakers use to secure OEM allocations. The winners will be those who align incremental capacity with OEM roadmaps for safety and weight reduction.
Dynamics shaping the 2026 strategic agenda
The market’s near‑term behavior is being driven by three interlocking dynamics: raw material and coil pricing volatility; OEM procurement strategies (including the growth of long‑term fixed arrangements); and technology adoption at the materials level (AHSS, press‑hardened steels, and coatings). Each carries implications for pricing, margins and supply security.
-
Raw material and pricing pressure: Early 2026 saw notable supplier price actions in hot‑rolled coil markets, signalling persistent cost pressure on feedstock. Producers are responding with price adjustments and allocation strategies while buyers re‑examine hedging and spot exposure policies.
-
Procurement and contractual hedging: Several major steelmakers have secured multi‑year supply arrangements with OEMs. These contracts serve as hedges against tariff and price volatility and are shaping the allocation of automotive‑grade steel from existing and new capacity.
-
Technology adoption and specification drift: OEMs continue to push for higher‑performance grades to balance crashworthiness with mass reduction. Symposiums and technical forums in 2026 have amplified collaboration between steel producers and OEM engineering teams, accelerating technical adoption curves for press‑hardened and advanced high‑strength steel.
Competitive landscape — who matters and why
The competitive set includes integrated global producers, regionally dominant mills, and vertically integrated suppliers who collectively influence price formation and availability. The market structure benefits firms that can combine product breadth (advanced high‑strength sheets, galvanized lines), geographic reach, and OEM relationships.
-
ArcelorMittal — a leader in advanced high‑strength and flat‑rolled automotive products focused on body‑in‑white and structural components. Their technical capability positions them to be a design partner for OEMs pursuing next‑generation lightweight architectures.
-
Nucor Corporation — North America’s large EAF producer that is deploying capacity specifically for automotive grades and actively managing pricing and allocation in 2026. Strategic expansions targeting hot‑rolled coil capacity with automotive allocation underline a supplier seeking to lock in OEM supply relationships.
-
Nippon Steel and JFE Steel — Japanese integrators with deep OEM ties and advanced sheet technologies, driving performance grades for safety‑critical structures.
-
Tata Steel and POSCO — regionally influential suppliers with portfolios spanning micro‑alloyed high‑strength steels and coated products.
-
Cleveland‑Cliffs — commanding the North American automotive steel conversation through galvanizing capability, OEM awards and multi‑year contract wins that strengthen their role as a preferred supplier for exposed applications.
-
Hyundai Steel, voestalpine and China Baowu — each bringing differentiated strengths in high‑performance grades, regional scale, or cost competitiveness.
Recent 2026 developments exemplify competitive dynamics: public price hikes in hot‑rolled coil and targeted capacity allocation by major producers; new multi‑year supply contracts and supplier awards with OEMs; and industry symposia that have accelerated technical collaboration on press‑hardened and AHSS solutions. These moves are not isolated — they are signals of how suppliers are managing margin preservation, allocation discipline and technical differentiation.
Strategic implications and recommended actions for 2026
Companies that treat 2026 as a year to optimize optionality rather than crystallize single‑path strategies will be better positioned. Below are practical moves we counsel for each major stakeholder group.
-
OEMs and Tier‑1s — pursue layered procurement portfolios: combine shorter rolling contracts to capture spot dips with strategic long‑term agreements to secure capacity for critical grades. Include performance clauses tied to qualification timelines and value‑in‑use metrics.
-
Steel producers — prioritize allocation frameworks: use portfolio segmentation to allocate premium grades to customers with co‑development roadmaps; monetize differentiation via engineering partnerships and technical services.
-
Investors and M&A teams — seek bolt‑on assets that reduce time‑to‑supply for automotive grades (galvanizing lines, slitting/blanking capabilities) and prioritize targets with stable OEM contracts or demonstrable technical IP.
-
Procurement and risk officers — rehearse hedging strategies that reflect the new baseline for coil prices and test stress cases where supply is diverted to long‑term contract holders. Also, build supplier scorecards that weigh allocation commitments alongside unit pricing.
-
R&D and product managers — lock design‑for‑manufacturing linkages early with steel partners, and quantify trade‑offs among AHSS, press‑hardened options and alternative materials for each sub‑system; prioritize demonstrable cost‑per‑kg and lifecycle benefits.
What the PW Consulting report delivers — practical, transaction‑ready intelligence
The full PW Consulting Automotive Steel Market study is designed to support immediate 2026 decision cycles. It combines market‑grade time‑series, supplier heatmaps, procurement playbooks, and scenario modelling that translate directly into RFPs, CAPEX decisions and negotiation strategies. Key deliverables include:
-
Top‑down and bottom‑up demand models (2020–2025 historical series; 2026–2032 forecast) aligned to vehicle production scenarios and material substitution pathways.
-
Price‑and‑cost sensitivity matrices mapping hot‑rolled coil moves to finished automotive steel margins under alternate feedstock price and contract mix assumptions.
-
Supplier concentration analysis (CR3, CR5 metrics) and an OEM allocation tracker identifying where supply imbalances are likely to appear.
-
Negotiation playbooks and sample contract language for multi‑year agreements, spot purchases, and capacity reservation clauses — enabling procurement teams to act in quarter‑level cycles.
-
Technology adoption roadmaps and a decision rubric for grade selection across body structure, powertrain and exposed components — with value‑in‑use calculators for material substitution assessments.
-
Risk registers and mitigation plans covering tariff exposures, feedstock shocks and concentrated supplier failure scenarios.
Importantly, the report balances strategic depth and confidentiality: it surfaces the material drivers and actionable recommendations you need, while directing readers to the source portal for the complete segmented datasets and supplier‑level tables. That approach preserves proprietary negotiation advantage for clients while enabling immediate strategy deployment.
Closing observation — treat 2026 as an option‑creating year
The automotive steel market in 2026 is not a binary story of disruption versus decline. Instead, it is a nuanced evolution where technical differentiation, contractual design, and allocation management define winners. Firms that execute layered procurement strategies, accelerate engineering partnerships with producers, and incorporate scenario‑based hedging will preserve margin, secure supply and accelerate product innovation.
For executives preparing budgets, CAPEX submissions or strategic sourcing mandates this year, the task is to convert the market’s modest CAGR and concentrated supply base into options: flexibility to capitalize on price troughs, secured capacity for high‑value grades, and clear technological choices for next‑generation vehicle programs.
Access to the comprehensive datasets, supplier allocations and graded scenario outputs in the full PW Consulting Automotive Steel Market report will materially shorten your path from insight to execution. Contact PW Consulting’s industry team to obtain the complete analysis and tailored briefings that operationalize the recommendations above.
For detailed analysis of this topic, please visit the official page: Automotive Steel Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com