

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Insulated Lunch Box Market Poised for 6.4% CAGR (2026–2032)

Insulated Lunch Box Market — Strategic Briefing for 2026 Decision-Makers
Executive snapshot
As corporate procurement, product development and channel strategy teams plan for 2026, the insulated lunch box market presents a clear, investable growth story anchored in steady demand for portable, safe and sustainable food storage. Our latest PW Consulting market study — built on a 2020–2025 historical base and a forward projection through 2032 — shows the market expanding at a mid-single-digit compound annual growth rate (CAGR) into the next planning cycle. From a base-year position in 2025, the market is forecast to continue a consistent upward trajectory through 2032, reflecting a combination of consumer lifestyle shifts, regulatory pressure, and material- and technology-driven product differentiation.
Insulated Lunch Box Market
Why this matters for 2026 strategy
-
Portfolio prioritization — The category is mature but not saturated. A predictable growth profile enables disciplined resource allocation: companies can pursue differentiated premium plays (performance, durability, brand positioning) while protecting volume businesses with price and channel optimization.
Insulated Lunch Box Market -
Channel rebalancing — Evolving consumer purchase behavior and the aftermarket (replacement cycles, gifting, corporate-branded programs) are shifting the optimal mix of DTC, specialty outdoors/foodservice channels and mass retail. 2026 is the year to lock in channel economics and exclusive assortments that secure distribution without eroding margin via indiscriminate discounting.
Insulated Lunch Box Market -
Regulatory-driven innovation — New food-contact safety regulations and packaging waste policies are forcing material and design reassessment. Early movers who align product roadmaps to safer, low-leach materials and recyclable/upcyclable formats will avoid compliance costs and capture preference among health- and sustainability-conscious consumers.
Market dynamics at a glance (data-driven context)
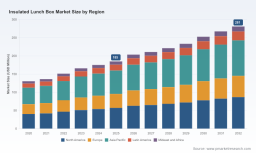
Between 2020 and 2025 the market demonstrated resilient expansion, with notable acceleration in years when consumer mobility and at-home meal prep trends reinforced demand for portable food storage. Using 2025 as the baseline, our forecast models — integrating macro consumption patterns, material cost trajectories and regulatory scenarios — project continued growth through 2032 at approximately a 6.4% CAGR. The outcome is a mid-hundred-million-dollar global market in 2025 that expands meaningfully by 2032, creating tangible topline opportunities for incumbents and challengers alike.
Structural market concentration remains moderate. The top three and top five suppliers do not command overwhelming share, leaving meaningful pockets of opportunity for niche specialists, private labels and regional champions. This market geometry favors targeted specialization and smart partnerships over brute-force national rollouts.
Key trends shaping competitive advantage
-
Material evolution — Beyond insulation performance, material choice is now a strategic battleground: hygiene, perceived safety, lifecycle environmental impact and rising stainless-steel demand are reshaping purchase criteria. Product teams should invest in material roadmaps that balance performance, cost and recyclability; supplier qualification must include traceability and compliance metrics tied to evolving regulations.
-
Thermal performance meets convenience — Consumers increasingly expect lunch systems that preserve temperature for extended periods while offering leak-proof, compartmentalized convenience. Winning designs pair validated thermal retention with everyday usability (easy cleaning, modularity, light weight).
-
Premiumization vs. democratization — Two parallel trajectories exist: premium durable products positioned at outdoor/professional users, and accessible, feature-rich options for school and workplace use. Each requires a distinct go-to-market playbook: storytelling and brand collaboration for premium, and value engineering plus channel promotions for volume segments.
-
Regulatory and tariff shifts — Recent food-contact safety rulings and customs reclassifications are changing landed cost math and acceptable materials. Procurement and regulatory teams must model these policy shifts to avoid margin surprises and ensure shelf-compliant reformulations.
-
Retail and review influence — Editorial testing and authoritative product reviews continue to drive conversion in a category where performance claims are meaningful to buyers. Brands must prioritize independent testing and transparent claims substantiation.
Competitive landscape — what incumbents and challengers are doing
The competitive fabric is diverse: legacy consumer-packaged-goods brands, outdoor lifestyle specialists, heritage appliance makers and purpose-built start-ups all stake claims. Each major player brings a distinct strategic playbook.
-
Iconic insulated-thermos brands continue to leverage trusted temperature technology and premium positioning. Their strength lies in recognized performance claims, broad distribution and household penetration. For 2026, they will likely double down on premium adult-targeted SKUs and corporate licensing partnerships.
-
Outdoor and premium performance players are building on their rugged brand equity to capture higher-margin professional and recreational users. Their product narrative emphasizes durability, extended retention and warranty-backed value — positioning that commands price resilience.
-
Design-forward consumer brands are competing on aesthetics and daily lifestyle fit. They pursue collaborations, seasonal drops and influencer-led marketing to keep aspirational positioning fresh and to expand into adjacent categories (bottles, bags, tabletop).
-
Utility-focused and value brands target mass channels with simplified features and cost-optimized materials. Their play is scale and distribution; margin expansion depends on cost control and private-label partnerships.
-
Regional specialists and appliance innovators deliver category-redefining features such as superior vacuum insulation or airtightware integration; they are the most likely acquisition targets for global players seeking feature-led entry points.
Notable competitive signals to monitor in 2026: independent test updates and product reviews that influence mainstream buying, and strategic launches that couple material innovation with demonstrable compliance to new food-contact rules.
Regulatory, supply chain and cost considerations
-
Food-contact safety requirements: New mandates are tightening acceptable material lists and forcing manufacturers to validate non-leaching properties. Companies must be able to produce compliance dossiers and batch-level traceability to maintain shelf access.
-
Tariff and customs reclassification: Recent reclassifications have materially changed duty exposure for certain product formats. Pricing teams should incorporate different landed-cost scenarios into SKU-level profitability models, and sourcing strategies should include alternative manufacturing footprints where tariff savings are meaningful.
-
Material price volatility: Key inputs (stainless steel, engineered plastics, insulation foams) have experienced cyclical swings. Procurement should pursue hedging where possible, dual-sourcing for critical components, and value-engineering for mid-tier SKUs to preserve margin.
-
Sustainability imperatives: Governmental pressure to reduce single-use plastics and consumer preference for recyclable materials accelerate adoption of alternative-material designs. Brands that can demonstrate cradle-to-cradle thinking will gain shelf and pricing preference.
What the PW Consulting report delivers (practical content)
-
Quantitative model — An editable financial model with historical (2020–2025) and forecasted topline scenarios (through 2032), sensitivity testing by material-cost scenarios and alternative regulatory outcomes.
-
Go-to-market playbooks — Channel-specific commercialization blueprints for premium, volume and institutional segments, including pricing ladders, promotional cadence and distributor negotiation guidance.
-
Competitive profiles — Strategic assessments of the major players, capability maps, and playbook implications (where to partner, where to compete directly, and likely M&A targets).
-
Innovation and product roadmap tracker — A catalog of recent and near-term product introductions, independent test outcomes and feature diffusion timelines to help prioritize R&D and patent monitoring.
-
Regulatory impact analysis — Scenario planning tools and compliance checklists tailored to the U.S., EU and key APAC jurisdictions, emphasizing food-contact safety and material restrictions.
-
Supplier and cost playbook — Benchmarked supplier scorecards, alternative-material sourcing options and cost-to-serve calculators that operational teams can deploy immediately.
-
Decision-support deliverables — Executive one-pagers, investor-ready slide decks and an implementation roadmap to accelerate time-to-value from insight to action.
Recommended actions for 2026 (prioritized)
-
Fast-track compliance audits and material requalification programs to mitigate regulatory risk and enable accelerated product introductions in regulated markets.
-
Segment the portfolio into clear strategic buckets (premium, mid-market, institutional) and assign distinct P&L owners to ensure accountability for margin and growth targets.
-
Lock in strategic supplier agreements for key materials (especially stainless steel and advanced insulation components) with contingency capacity to protect against cost spikes.
-
Invest in independent thermal and safety testing, and use verified results as a clear marketing differentiator — editorial endorsements significantly influence conversion in this category.
-
Pursue selective partnerships and bolt-on acquisitions to acquire capability (e.g., vacuum-insulation tech, specialty manufacturing) rather than building from scratch when speed-to-market is critical.
Concluding note — the value of the full report
This briefing outlines the strategic contours of the insulated lunch box market as you plan for 2026. Our comprehensive PW Consulting report provides the full quantitative backbone, competitive due diligence and executable playbooks necessary to convert insight into market share and profitable growth. The executive summary above purposefully highlights directional intelligence while reserving the granular segmentation and SKU-level economics for the full research package — the level of detail you need for board-level planning and M&A diligence.
For teams preparing 2026 budgets and go-to-market roadmaps, the full report is the operational tool to prioritize investments, de-risk supply chains and capture the material and regulatory shifts shaping the category. Contact PW Consulting to access the full dataset, customizable models and tailored advisory support to activate these findings within your organization.
For detailed analysis of this topic, please visit the official page: Insulated Lunch Box Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com