

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Pulmonary Function Testing Market to Reach USD 5,948M by 2032 (CAGR 6.8%)

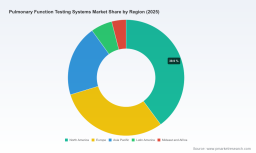
Pulmonary Function Testing Systems Market — Strategic Executive Preview for 2026 Decisions
Executive summary
As healthcare providers and medical-device investors approach 2026, the pulmonary function testing (PFT) systems market presents a clear, data-backed growth story shaped by demographic tailwinds, evolving clinical pathways, and rapid device digitalization. Our latest market model (base year 2025; historical window 2020–2025; forecast period 2026–2032) captures these dynamics and projects a sustained compound annual growth rate (CAGR) of 6.8% through 2032. Measured on a global basis, the market more than doubles from the early-2020s baseline and approaches the high single‑digit billions (USD) by the end of the forecast horizon — a trajectory that underpins near-term tactical choices and mid-term strategic bets alike.
Pulmonary Function Testing Systems Market
Why this research matters for decisions in 2026
-
Investment prioritization: With PFT systems transitioning from standalone devices to networked diagnostic platforms, capital allocation across hardware, software, and services must be calibrated against a multi-year adoption curve. Our forecast provides the growth envelope for sizing R&D and go‑to‑market budgets.
Pulmonary Function Testing Systems Market -
Product roadmap validation: Device miniaturization, smartphone integration, and cloud-based analytics are shifting purchasing criteria. The report identifies which technology attributes correlate with accelerated uptake and where incumbents risk being commoditized.
Pulmonary Function Testing Systems Market -
M&A and partnering strategies: Fragmentation and pockets of innovation create attractive targets for bolt-on acquisitions (device + software) and licensing partnerships. The analysis surfaces where consolidation is most likely to generate scale and technical differentiation.
-
Regulatory and procurement readiness: Stricter device classification in major markets and tightening clinical-evidence expectations mean product compliance is now a market access prerequisite. Our regulatory matrix helps prioritize certification sequences that shorten time-to-contract with large hospital systems and group purchasing organizations (GPOs).
What the report delivers — practical, operational outputs
This research has been crafted as an execution-oriented toolkit for commercial, product, and corporate development leaders. Key deliverables include:
-
Transparent market-sizing model (2020–2032) with scenario layers that isolate technology substitution, reimbursement pressure, and site-of-care shifts.
-
Demand-driver heatmap and clinical pathway mapping that connects epidemiology, screening initiatives and hospital workflow to equipment purchasing decisions.
-
A regulatory playbook aligning EU MDR, international ISO standards for spirometry and lung volumes, and U.S. market-clearing pathways to product‑development timelines.
-
Reimbursement impact assessment and a buyer economics calculator that models lab-level margins under differing fee schedules and test mixes.
-
Competitive benchmarking and feature‑gap analysis across hardware accuracy, connectivity, software analytics, and service models — with strategic implications for pricing and channel strategy.
-
Go‑to‑market playbooks for hospital systems, ambulatory clinics, occupational health programs, and consumer/home-care distribution.
-
M&A scorecard and a prioritized short list of capability gaps where acquisition is the fastest route to market advantage.
-
Operational checklists for sterilization, reusable-device protocols, and procurement RFx preparation aligned to leading accreditation standards.
Market structure and concentration — what leaders should note
The PFT systems market remains relatively fragmented. The top three and top five firms together account for a modest share of global revenue, indicating significant room for competitive repositioning by mid-sized firms and new entrants. Low concentration creates two strategic imperatives: first, differentiate through integrated solutions (device + analytics + services); second, exploit regional procurement inefficiencies with targeted commercial models. Fragmentation also keeps valuations of potential targets in a range that makes smaller bolt‑on acquisitions accretive for established players.
Competitive landscape — who is moving the market
-
Vitalograph (Maidenhead, United Kingdom): A long-standing supplier across professional spirometry, plethysmography and oscillometry. Recent partnerships point to a strategy of extending diagnostic breadth via alliances and selected product co‑commercialization.
-
Jaeger Medical (Hochberg, Germany): Known for PC‑based spirometry and full PFT systems. Its clinical-grade positioning keeps it relevant for hospital and laboratory procurement cycles.
-
MGC Diagnostics (St. Paul, Minnesota, USA): Offers integrated PFT systems with enterprise software platforms for cardiopulmonary testing — a playbook focused on high-acuity clinical settings and research customers.
-
Norav Medical (Delray Beach, Florida, USA / Mainz‑Kastel, Germany): Specializes in compact, USB‑powered spirometers optimized for rapid deployment and distributed testing models; recent device introductions underscore the trend toward miniaturization and regulatory-grade portable testing.
-
MIR (Medical International Research) (Italy, with North American presence): Emphasizes smart, smartphone‑compatible spirometry and oximetry for mixed clinical and home-care channels.
Each of these players illustrates a strategic axis: depth of clinical-system integration, portability and cost-efficiency, or digital platform capabilities. Recent corporate moves — strategic partnerships, product launches, and regulatory clearances — confirm that incumbents and innovators are pursuing differentiated routes to volume and service revenues.
Recent developments and implications
-
Strategic partnerships and product diversification are accelerating. Collaborative launches expand device portfolios quickly without always incurring full R&D cycles.
-
Miniaturized, standards‑certified devices are lowering unit economics and enabling new sites of care (primary care, occupational health, home monitoring), while increasing the addressable market for suppliers that can scale manufacturing and service operations.
-
Integration of PFT with other physiological signals (e.g., wireless ECG) and trial-centric devices hints at expanding use cases in clinical research and telehealth, shifting buyer value propositions toward data and interoperability.
Standards, regulation and payer dynamics — non‑negotiables for market access
Regulatory frameworks and international standards are shaping product roadmaps. The European MDR has tightened the clinical-evidence and conformity assessment bar in Europe, while international ISO standards for spirometry and lung-volume measurements remain procurement prerequisites for institutional buyers. Accreditation bodies and hospital infection‑control protocols mandate strict cleaning and reprocessing guidance for reusable devices — a factor that materially affects TCO and product design choices.
On the payer side, fee schedules in major markets have not kept pace with device and technician cost inflation, pressuring test‑site margins and amplifying demand for operational efficiencies. Vendors that can demonstrate lower per-test cost, remote-testing workflows, or bundled service contracts will have a competitive edge during purchasing negotiations.
Strategic implications and recommended next steps for 2026
-
Prioritize modular platforms: Design modular devices that can be upgraded with analytics and connectivity modules to protect installed-base value and accelerate cross‑sell.
-
Embed evidence generation into product launches: Regulatory clearance is necessary but not sufficient; prospective, payer-relevant health‑economic studies materially improve contracting outcomes with health systems and insurers.
-
Invest in channel engineering: Differentiate commercial models for hospitals, outpatient clinics, occupational medicine and consumer channels. Service bundles and remote-calibration offerings will be decisive in price negotiations.
-
De-risk supply chains: The shift toward portable, electronic devices increases dependence on semiconductor and sensor availability. Strategic sourcing and inventory strategies are now core to market reliability claims.
-
Use M&A to acquire software capabilities: The highest value accruals will come from combining measurement accuracy with analytics and patient-management workflows.
How to use this preview
This executive preview is designed to align leadership around the high‑value strategic choices facing PFT-system stakeholders in 2026. It surfaces the market direction, key competitive moves, regulatory constraints, and actionable recommendations. To preserve decision advantage, detailed tables showing regional/type/application splits, company-level market shares, and downloadable forecasting models are reserved for the full PW Consulting report and dataset.
Next steps
For teams planning product launches, channel expansions, or capital allocation in 2026, the full report provides the granular inputs (time‑series market sizing, payer-impact models, procurement RFx templates, and vendor scorecards) required to convert strategy into executable plans. Contact PW Consulting to obtain the full dataset, scenario workbooks, and a tailored briefing that maps our findings to your portfolio and growth targets.
For detailed analysis of this topic, please visit the official page: Pulmonary Function Testing Systems Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com