

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Wireless Router Market to hit USD 271.95M by 2032 (8.9% CAGR)

Wireless Router Market 2026: Strategic Preview for Decision-Makers
Executive snapshot
The wireless router market is moving from incremental upgrades to platform-level reinvention. Our market model (base year 2025) shows a global addressable market of USD 150.0 Million and a trajectory that accelerates through the coming decade—reaching roughly USD 272.0 Million by 2032 at a compound annual growth rate of 8.9% (forecast period 2026–2032). That pace reflects a confluence of technology maturation (Wi‑Fi 6E/7, integrated 5G/FWA), shifting operator economics, emergent regulatory frameworks around spectrum, and a new wave of customer expectations for managed connectivity, security, and AI-driven optimization.
Wireless Router Market
Why this matters for 2026 corporate strategy
-
Timing for product investment. The market’s post‑2025 growth window rewards investments that convert early Wi‑Fi 7 capabilities and multi‑access convergence into differentiated value—particularly through software, managed services, and partnership models that extend lifetime revenue beyond one‑time device sales.
Wireless Router Market -
Channel & partner activation. Channel economics are rebalancing: service providers and large retailers remain critical, but direct‑to‑consumers subscription models and operator bundling are increasing the share of recurring revenue within router ecosystems.
Wireless Router Market -
Regulatory read‑through. Spectrum policy and spectrum‑sharing regimes are no longer peripheral. Changes in spectrum management and classification of broadband services materially impact go‑to‑market and R&D priorities—especially for vendors building multi‑band, satellite‑coexistent, or licensed/unlicensed hybrid products.
Market trajectory and leading demand vectors
From 2020 through 2025 the market exhibited steady expansion, and our scenario analysis points to an acceleration driven by three intersecting vectors: higher per‑unit ASPs for premium multi‑band routers, faster replacement cycles among prosumer and enterprise edge segments, and broader deployment of managed home gateway services by operators. Geographic demand patterns and adoption curves vary, but the global headline numbers are consistent: sizeable, sustained growth with significant upside for vendors that can stitch hardware, software and recurring services into a cohesive proposition.
Technology & product dynamics
-
Parallel standards adoption. Wi‑Fi 6E laid groundwork for 6 GHz utilization; Wi‑Fi 7 introduces meaningful throughput and latency improvements that unlock new use cases (real‑time AR/VR, dense apartment complexes, low‑latency gaming). Vendors who integrate multi‑band radios with intelligent spectrum management will capture price premiums.
-
Convergence with cellular. The rise of 4G/5G FWA gateways and hybrid router architectures makes multi‑access capabilities table stakes for certain channels. Fixed wireless access suppliers and enterprise edge players are increasingly part of the router competitive set.
-
Software differentiation. The product is no longer a single SKU. OTA upgrade capability, cloud‑based analytics, AI network optimization, and security subscriptions are decisive for customer retention and margin expansion.
Regulation, spectrum & systemic risks
Regulatory actions in 2025–2026 have shifted the framing around spectrum and service classification. Recent orders and policy proposals emphasize spectrum sharing, more permissive use of mid/high bands, and coordination mechanisms across jurisdictions. Specifically, calls for AI‑assisted spectrum management and a “use it or share it” mindset in some jurisdictions lower technical barriers to dynamic multi‑tenant deployments, but also create compliance burdens for vendors deploying spectrum‑aware radios.
Separately, the reclassification of broadband internet access services in certain jurisdictions alters the regulatory perimeter for vendor and operator behavior—affecting obligations related to traffic management, disclosure, and potentially pricing. The net effect is a market where technical capability must be matched by regulatory operating models and compliance toolsets.
Competitive landscape — who matters and why
The market remains moderately fragmented. Our concentration analysis indicates the top three vendors account for a meaningful minority of market share, and the top five capture a larger but still non‑dominant portion—leaving room for focused specialists, ODMs, and operator partnerships to win differentiated positions.
-
NETGEAR (San Jose, CA) — Known for a dual‑track strategy: consumer/prosumer performance SKUs and SMB/edge solutions. Their strength lies in brand recognition and a broad retail footprint; success depends on converting premium hardware into subscription services.
-
ASUS / ASUSTeK (Taipei) — A reputational leader in high‑performance and gamer‑oriented routers. They excel at feature‑led innovation and enthusiast communities; scaling their propositions into managed channels is a near‑term strategic lever.
-
TP‑Link (Shenzhen) — Global volume player with aggressive cost and channel execution. Recent SKU introductions signal leadership in commercializing Wi‑Fi 7 at scale; their ability to defend margins while investing in software services will determine platform economics.
-
Calix (San Jose, CA) — Primarily an operator‑oriented supplier, integrating access hardware with cloud management platforms. Their play is strategic: act as a systems integrator for operators pursuing higher ARPU through managed home services.
-
Arris (Suwanee, GA) — Focused on MSO and telco CPE, with strengths in operator certification cycles and large‑scale deployments. Their competitive moat is operational scale and relationships with service providers.
-
Arcadyan Technology (Taipei) — An ODM/contract manufacturer with capability to turn designs into volume shipments; critical for brands seeking rapid time‑to‑market without expanding capex.
-
Sagemcom (Boulogne‑Billancourt) — European operator partner with deep regulatory and certification experience across EU markets; valuable for vendors targeting operator bundles and where regulatory nuance matters.
-
Inseego (San Diego, CA) — Brings expertise in 4G/5G FWA and enterprise gateways; a strategic fit for operators and enterprises migrating to hybrid fixed‑wireless edge architectures.
-
GL.iNet (Shenzhen) — Niche specialist focused on open‑source, privacy, and developer communities; a pipeline partner for differentiated verticals (IoT, travel, specialized security applications).
Recent developments to watch
-
TP‑Link’s late‑2025 commercial release of a Wi‑Fi 7 SKU underscores how device makers are racing to monetize new spectrum opportunities and performance claims. Expect product roadmaps to emphasize 6 GHz and multi‑radio integration.
-
Regulatory moves in 2025–2026 (spectrum sharing modernizations and EU proposals advocating coordinated management) will shape both technical design and go‑to‑market permissions—especially where coexistence with satellite services or dynamic spectrum access is involved.
Strategic implications and recommended actions for 2026
-
Prioritize software & services. Mature hardware portfolios without subscription or cloud monetization will face margin pressure. Design product roadmaps where hardware is an on‑ramp to recurring revenue.
-
Architect for regulatory agility. Build compliance and spectrum‑awareness into product lifecycles. Regulatory scenarios are material risks/opportunities—plan for multiple regional outcomes and embed configurability in firmware and certification roadmaps.
-
Segment go‑to‑market by value, not just by geography. Target operator bundles, enterprise edge, and prosumer channels with customized product suites and support models rather than a one‑size SKU approach.
-
Evaluate partnership and M&A selectively. Consolidation opportunities exist in software orchestration, security services, and ODM relationships. Use small, strategic acquisitions to accelerate capabilities rather than broad market share plays.
-
Invest in measurable field trials. Quantify real‑world gains from Wi‑Fi 7, mesh architectures, and hybrid fixed‑wireless solutions across representative customer cohorts to substantiate ASP premiums and deployment playbooks.
What PW Consulting’s full report delivers (practical, executable outputs)
This research is designed as a decision‑grade tool for executives crafting 2026 plans. Highlights include:
-
Proprietary market model with historical 2020–2025 calibration and granular 2026–2032 forecasts (scenario and sensitivity layers).
-
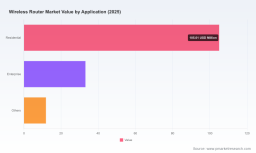
Strategic segmentation framework and adoption curves that identify near‑term and medium‑term white spaces (note: detailed segment breakouts and revenue share tables are available in the full report).
-
Competitive benchmarking and capability maps across product, software, channel, and service dimensions—plus vendor SWOTs and partner tiering.
-
Regulatory impact assessment with playbooks for spectrum compliance, certification pathways, and contingency scenarios tied to recent policy developments.
-
Go‑to‑market blueprints for three distinct strategic archetypes: Operator‑centric integrator, Premium Consumer/Prosumer platform, and Volume OEM with managed services overlay.
-
Investment & M&A tracker with prioritized targets, valuation heuristics, and five‑year synergy case templates.
-
Implementation checklists and a one‑page decision matrix executives can use to align R&D, product, sales, and regulatory teams within 90‑day sprints.
Conclusion — the signal through the noise
The next 18 months are decisive. The market is large enough to support both scale players and focused specialists, and fast enough in its evolution that first movers who pair Wi‑Fi 7 and hybrid access capabilities with cloud services and regulatory‑aware architectures will set durable expectations in the market. However, success will not come from hardware alone: commercial models, partner ecosystems, and compliance strategies will determine who captures the recurring value of tomorrow’s router market.
Access the full intelligence
This preview is intended to highlight the strategic options and to demonstrate the depth of analysis in PW Consulting’s full Wireless Router Market report. For the complete dataset, segmentation breakdowns, vendor scorecards, and executable playbooks, please consult our full publication and model package.
For detailed analysis of this topic, please visit the official page: Wireless Router Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com