

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Electric Car Chargers Market Poised for 22.5% CAGR Through 2032

Electric Car Chargers Market: Strategic Intelligence for 2026 Decision-Making
As jurisdictions, fleets, utilities and real-estate owners accelerate plans to electrify transportation, 2026 will be a pivotal year for companies that need to translate strategic intent into executable programs. PW Consulting’s latest Electric Car Chargers Market research frames that window of opportunity with a concise, actionable intelligence package: market trajectory, regulatory inflection points, competitor positioning, and buyer-side operational playbooks. This introduction previews the strategic value of the full study — showing the depth of our analysis while preserving the granular segmentation and models that organizations must consult directly to shape procurement, partnership and go-to-market moves in 2026.
Electric Car Chargers Market
Why 2026 Is a Strategic Pivot
Our market model uses 2025 as the base year and a 2026–2032 forecast horizon. The sector is on an unmistakable growth path: market size expanded rapidly over the previous half-decade and PW Consulting projects continued acceleration through 2032 at a compound annual growth rate (CAGR) of 22.5%. In absolute terms, the market has grown materially from the early 2020s and is set to more than quadruple by the end of the forecast period. These are not abstract numbers — they translate into capacity deployments, network software contracts, manufacturing volume requirements, and large-capital public infrastructure investments.
Electric Car Chargers Market
For executives planning 2026 budgets, three operational realities follow directly from this trajectory: (1) lead times for hardware and civil works will lengthen as demand surges; (2) policy and procurement timelines (especially federally enabled infrastructure programs) will create scheduling constraints that cannot be reshuffled without cost; and (3) software and services — billing, operations, and energy management — will emerge as durable margin pools irrespective of hardware commoditization.
Electric Car Chargers Market
Core Dynamics Shaping Supplier and Buyer Strategies
-
Regulatory and procurement inflection. Federal procurement rules and domestic content requirements are tightening. Agencies have proposed raising domestic content thresholds for federally funded EV charger projects, and implementation calendars tied to October 2026 will alter eligible supplier sets. For public-works procurement teams and private vendors pursuing federal projects, this is an operationally decisive change: it affects sourcing, supplier qualification, and near-term M&A or partnership calculus.
-
Standards and interoperability enforcement. Jurisdictions are moving from voluntary guidance to mandatory technical conformance for specific programs — for example, hardware conformance rules for Level 2 chargers now apply in certain utility incentive programs. That means product roadmaps must demonstrate formal compliance, and testing/certification timelines must be built into product and go-to-market plans.
-
Charging mix and grid integration stress. DC fast charging and managed AC charging present different technical and commercial challenges: siting, grid upgrades, demand charges, and energy procurement strategies. Vehicle-to-grid and bidirectional technologies are crossing the threshold from pilot to early commercial adoption, creating new value streams for energy arbitrage, resiliency and managed charging.
-
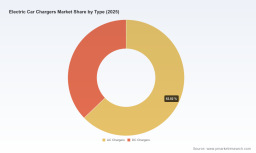
Consolidation pressure without full concentration. The market exhibits moderate concentration: the top three firms account for roughly a third of market value, and the top five for a bit over two-fifths. This implies leading vendors can shape standards and pricing, but there remains substantial opportunity for niche, regional, and vertical-specialist challengers.
Competitive Landscape — What Winning Looks Like in 2026
Our competitive analysis evaluates product capability, channel model, manufacturing footprint, software assets, customer base and partnership ecosystems. Highlights from the vendor landscape:
-
Network and ecosystem integrators (example profile). Companies specializing in large-scale charging networks and cloud-based management systems have leverage in fleet and commercial deployments where integrated billing, reservations and uptime guarantees matter. Their pathway to scale relies on robust operations teams and the ability to bundle services (hardware + O&M + energy contracts).
-
Hardware specialists (example profile). Firms focused on high-power DC fast charging or rugged Level 2 hardware compete on reliability, thermal management, and modular designs that ease site upgrades. High-power manufacturers targeting commercial and fleet markets can capture premium margins but must manage supply chains for semiconductors and power electronics.
-
Residential and energy-enabled vendors (example profile). Players offering smart Level 2 chargers with load-balancing and energy monitoring differentiate through customer-facing apps, integration with home energy systems, and partnerships with solar and battery providers. Bidirectional charging suppliers are positioning for vehicle-to-home and vehicle-to-grid services, creating new commercial propositions to utilities and DER aggregators.
Individual company positioning matters. Vendors that combine validated compliance (domestic content and regional standards), scalable operations, and a partner ecosystem (payments, fleet telematics, utilities) will win prime spots in the 2026 procurement pipeline. Recent market activity underscores this trend: there are expansion partnerships for rapid DC network roll-outs and strategic alliances around payment enablement — both indicative of an ecosystem moving from fragmented pilots to integrated commercial deployments.
Regulatory and Policy Noise to Watch (and Plan For)
-
Proposals to increase domestic content requirements in federal-funded projects — including trajectories that would require full domestic component sourcing — will reshape supplier eligibility for national programs. Procurement teams and vendors must model different waiver and compliance scenarios now to avoid later disqualification or cost shocks.
-
Implementation windows tied to manufactured-product rules create discrete deadlines that should be reflected in 2026 capital plans. For bidders on public grants and make-ready programs, certification and test evidence will be evaluated at contract time — not post-award.
-
Jurisdiction-specific technical mandates — such as hardware conformance requirements adopted by utility incentive programs — mean one-size-fits-all product strategies are becoming untenable. Instead, modular product architectures and certification pipelines are strategic assets.
From Insight to Action: Five Strategic Imperatives for 2026
-
Localize critical supply chains. For firms with federal ambitions, near-term decisions should prioritize supplier qualification, dual-sourcing and potential contract manufacturing arrangements to mitigate domestic-content risk. Consider manufacturing partnerships, tooling investments, or acquisition targets to secure compliant capacity.
-
Invest in interoperability and standards compliance. Make formal certification part of product roadmaps. For technology teams, building ISO and protocol conformance into release schedules de-risks deployment in utility and government-funded programs.
-
Move up the value stack with software and managed services. Hardware margins will compress; integrated services — uptime guarantees, energy optimization, and payments — will create stickiness and recurring revenue. Prioritize platform integrations that enable fleet telematics, utility DR signals and flexible billing.
-
Design financial offers that match buyer constraints. Create flexible financing and O&M models (capex-light leases, availability-based payments) for real estate and fleet customers. Align commercial structures with utility incentive timetables to maximize uptake.
-
Use scenario-based capacity planning. The macro growth path is steep; long lead times in civil, electrical and transformer work mean delivery schedules must be realistic. Build scenario models that tie demand forecasts to procurement cycles and talent acquisition plans.
What PW Consulting’s Full Report Delivers
The full Electric Car Chargers Market study is designed as a practical playbook for decision-makers. It contains:
-
Our detailed market model (historical 2020–2025 and forecast 2026–2032) with revenue and deployment scenarios, sensitivity analysis and bottom-up assumptions for demand drivers.
-
Commercial intelligence dossiers on market participants, including capability matrices, channel footprints, product roadmaps, and M&A/partnership pipelines.
-
Procurement and sourcing playbooks addressing domestic-content compliance, supplier scorecards, and an executable checklist for winning federally funded projects.
-
Site-selection and grid-integration tools: cost/benefit templates for DC vs. AC strategies, energy procurement options, and demand charge mitigation techniques.
-
Go-to-market playbooks for OEMs, installers, utilities and fleet operators — pricing strategies, channel economics, and sample contracting structures to accelerate adoption while protecting margins.
-
Ready-to-use slides and executive summaries for board-level decision-making, and an interactive dataset that lets users re-run our scenarios with custom assumptions.
Closing: How to Use This Intelligence in 2026
2026 will separate organizations that have operationalized electrification strategies from those still planning around it. The market growth trajectory and the regulatory timelines embedded in our model make two things clear: first, the next 12 months are decisive for supplier selection, compliance and capacity planning; second, software and services will define long-term profitability even as hardware volumes scale.
PW Consulting’s full report supplies the granular segmentation, supplier benchmarking and model access necessary to translate these insights into contracts, capital allocations and partnership roadmaps. If your 2026 strategy depends on competitive access to federal programs, rapid DC roll-outs, or durable fleet charging economics, the full study is the operational intelligence you should base those decisions on.
Next Step
Access the full report to unlock the detailed segmentation, vendor scorecards and the interactive forecasting model that underpin the recommendations summarized here. PW Consulting can also deliver a tailored briefing or scenario workshop to connect the insights directly to your 2026 planning cycle.
For detailed analysis of this topic, please visit the official page: Electric Car Chargers Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com