

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Cell Culture Market to Grow at 11.2% CAGR, Reaching USD 58.02B by 2032

Cell Culture Market 2026 Strategic Preview: Turning Acceleration Into Competitive Advantage
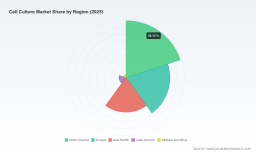
As organizations align budgets and product roadmaps for 2026, the cell culture market is transitioning from steady expansion into a phase of accelerated industrialization. Our latest market modeling shows the sector expanding from an estimated USD 27.58 Billion in 2025 at a compound annual growth rate (CAGR) of 11.2% through our forecast window — culminating in a market roughly double in size by 2032 (approximately USD 58.02 Billion). This preview distills the strategic levers that senior leaders must prioritize now to convert growth into durable market share, while intentionally omitting granular subsegment tables to guide you to the full PW Consulting dataset for transaction‑grade due diligence.
Cell Culture Market
Why this research matters for 2026 decision cycles
-
Accelerating demand converges with regulatory flexibility and supply volatility. The growth runway implied by our 11.2% CAGR creates immediate upside for capacity expansion, but success depends on executing against a narrow set of operational and commercial priorities in 2026.
Cell Culture Market -
Capital allocation choices made in 2026 — greenfield capacity, M&A, partnerships, or targeted R&D — will determine which players capture the disproportionate returns in the next five years. The market is no longer about pure volume: margin recovery, quality assurance under GMP, and differentiated product suites are decisive.
Cell Culture Market -
Investors and corporate strategists require a synthesis of macro growth, competitor positioning, regulatory tailwinds, and supply risk to set realistic timeframes for ROI. This research provides that synthesis and an operational playbook to translate it into 90‑ to 180‑day initiatives.
Key strategic imperatives for 2026
-
Supply‑chain resilience as a market differentiator. Variability in raw material quality and episodic supply disruptions have direct impact on manufacturing yields and timelines. Leading firms will move from tactical stockpiles to diversified, contract‑backed sourcing, validated secondary suppliers, and regional buffer capacity tied to demand scenarios.
-
Embed GMP/CMC compliance early in product development. Recent regulatory moves — including finalized flexible CMC requirements for cell and gene therapies and updated EMA guidance on reagent purity — lower the development friction for advanced therapies but raise the bar for manufacturing traceability and documentation. Firms that adapt processes now reduce late‑stage delays and gain speed‑to‑market.
-
Product modularity and platformization. As bioprocessing moves toward continuous and perfusion approaches, modular equipment and media platforms that support scale‑up/scale‑out will capture premium pricing. Companies should prioritize platform IP, scalable single‑use solutions, and compatibility roadmaps for common bioreactor systems.
-
Differentiation through defined, xeno‑free, and cell‑therapy focused formulations. Demand is shifting from classical serum‑based research products toward defined, animal‑component‑free formulations suited for therapeutic manufacturing and regulatory scrutiny. R&D investments should focus on robustness across cell types and ease of tech‑transfer.
-
Commercial sophistication: segmentation, pricing, and partnership playbooks. With market concentration high, targeted go‑to‑market strategies — channel partnerships for regional breadth, value‑based pricing for CDMOs and biopharma customers, and tiered service models for discovery vs. GMP customers — will determine accelerated uptake.
-
ESG and sustainability as procurement requirements. Sustainability certifications, reduced single‑use waste, and transparent sourcing are increasingly procurement gating factors for large customers and grant funders. Integrating sustainability metrics into product roadmaps is now a revenue motion, not merely a compliance checkbox.
Market structure and competitive dynamics
Competition sits in a moderately concentrated landscape: the three largest players account for roughly half of the market, while the top five approach seven out of ten market dollars. That concentration creates a dual dynamic — incumbents can shape standards and channel terms, but they also leave strategic niches accessible to focused challengers (e.g., specialized media for cell therapy, primary immune cell workflows, or custom GMP services).
-
FUJIFILM Irvine Scientific (Irvine, CA) — Specialized in classical, serum‑free, and perfusion‑optimized media with growing capabilities in custom bioprocess and cell therapy solutions. Recent partnership and collaboration activity in 2026 highlights its push into integrated production platforms.
-
Thermo Fisher Scientific (Waltham, MA) — Offers a broad Gibco portfolio spanning mammalian, primary, stem, and 3D culture products. Strength is breadth and institutional penetration across discovery and manufacturing customers.
-
Merck KGaA / MilliporeSigma (Darmstadt) — Combines classical and custom media with certified GMP production footprints. Plays heavily to regulated, scaled manufacturing customers.
-
Sartorius AG (Göttingen) — Known for animal‑component‑free formulations and integrated consumables/equipment bundles for both research and bioprocess workflows.
-
Corning Incorporated (Corning, NY) — Strength in media and sera optimized for scale; strategic asset for companies focusing on growth optimization across adherent and suspension systems.
-
Lonza (Basel) — Focus on scalable media for primary immune cells and gene‑therapy production, positioning it as a partner for advanced therapeutic manufacturers.
-
PromoCell (Heidelberg) — Niche specialist accelerating into GMP services, indicating where smaller, specialized vendors can monetize deep biological know‑how.
-
STEMCELL Technologies (Vancouver) and Cell Biologics (Chicago) — Both focus on stem cell and xeno‑free formulations; effective attack strategies are vertical integration with service offerings or upstream reagent exclusivity.
Recent moves that matter (select highlights)
-
FUJIFILM Biosciences launched a commercial platform combining research stromal cell lines and media (May 2026) and entered collaborative AAV production work under a Canada–Japan co‑innovation program (April 2026), signaling a push into integrated solutions for viral vector manufacturing.
-
PromoCell’s entry into GMP services in late 2025 demonstrates an attractive route for specialist vendors to capture higher‑value biomanufacturing revenue.
-
Catalog and certification initiatives from broader life‑science suppliers (e.g., Greiner Bio‑One updates in 2026) indicate product refresh cycles tied to sustainability and compliance demands.
Regulatory context and operational headwinds
-
Regulatory accelerators: The FDA’s finalized flexible CMC requirements for cell and gene therapies (effective January 2026) and subsequent draft updates in mid‑2026 reduce some barriers for small‑population therapeutics but bring heightened expectations for chain‑of‑custody and analytical comparability.
-
EMA and EU GMP guidance (including Annex 1 applicability) maintain rigorous contamination control and purity expectations for reagents; suppliers must demonstrate microbial purity and validated processes under GMP to serve advanced therapeutics.
-
Operational friction remains around raw material variability. Firms that invest in raw‑material qualification, analytical screening, and supplier development will see outsized improvements in yield and time‑to‑release.
What the PW Consulting report delivers (practical contents)
-
A transparent, audited market model with historic drivers (2020–2025) and scenario‑based forecasts for 2026–2032 illustrating upside, base, and downside paths reflecting regulatory and supply shocks.
-
Company scorecards and playbooks: strategic positioning, capability maps, commercial footprints, and acquisition targets that align with specific inorganic strategies.
-
Operational toolkits: procurement playbooks, supplier qualification templates, CMC alignment checklists, and modular capacity sizing templates that translate strategy into executable 90‑day plans.
-
Regulatory matrix and risk heatmap contextualizing FDA/EMA changes and regional GMP requirements against product types and customer segments.
-
Go‑to‑market and commercial scenarios with sensitivity analysis for pricing, channel mix, and service bundling (note: detailed subsegment tables and region/app splits are available in the full dataset to registered clients).
How to convert insight into action in 2026
-
For CEOs and CFOs: Prioritize capital allocation toward flexible, single‑use capacity and strategic tuck‑ins that accelerate GMP capabilities. Use scenario modeling from this report to stress‑test capex timing against the regulatory and supply scenarios.
-
For Heads of R&D/CMC: Fast‑track qualification of defined, xeno‑free formulations and codify tech‑transfer templates that reduce validation cycles. Early alignment with regulatory requirements converts development speed into commercial advantage.
-
For Commercial and BD teams: Build partnership scorecards and a two‑track model — pursue high‑value collaborations with CDMOs/biotechs while expanding discovery‑phase revenue through subscription and reagent‑as‑a‑service models.
-
For Supply Chain leaders: Implement multi‑tier sourcing, supplier development, and analytics for raw‑material variability. Locking conditional supply agreements and local buffer capacity for key components should be a 2026 KPI.
Conclusion — The 2026 inflection: Markets reward preparation. The cell culture market’s growth trajectory creates opportunities for both incumbents and focused challengers. Success will hinge on integrating compliance, supply resilience, scalable platforms, and commercially differentiated offerings into a coherent three‑year plan. PW Consulting’s full report converts the high‑level signals summarized here into transaction‑ready numbers, segment breakouts, supplier lists, and playbooks you can act on immediately. For teams preparing 2026 budgets and strategic plans, this research is the operational bridge between market potential and executable advantage.
For detailed analysis of this topic, please visit the official page: Cell Culture Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com