

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Radiator Hose Market to reach USD 272.6M by 2032 at 3.5% CAGR

Radiator Hose Market 2026: Strategic Preview for C-Suite Decision Makers
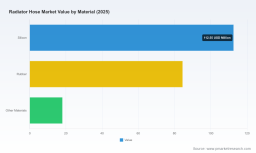
As PW Consulting’s Senior Strategy Advisor and Chief Industry Analyst, I present a concise, decision-focused preview of our comprehensive Radiator Hose Market research. This briefing is designed to orient executives, procurement leaders, and product strategists on how the market is evolving into 2026 and why this matters for near-term capital allocation, supply-chain design, product roadmaps, and M&A activity. The full study contains the granular segment-level datasets and scenario tables that underpin the recommendations below; this preview highlights the strategic conclusions while intentionally withholding the segment-level datapoints to preserve the report’s investigative value.
Radiator Hose Market
Market trajectory at a glance
The radiator hose market has demonstrated steady, resilient growth through the early-2020s recovery cycle and into 2025. Our base-year assessment places global revenue at approximately USD 215.0 million in 2025. The market is projected to expand at a compound annual growth rate (CAGR) of about 3.5% over the 2026–2032 forecast horizon, rising to roughly USD 223.2 million in 2026 and continuing toward an upper-end forecast in the early 270s by 2032. This is a market characterized by incremental unit growth, technology-driven product differentiation, and tightening regulatory pressures that favor higher-performance materials and integration-ready designs.
Radiator Hose Market
Why this matters for 2026 corporate decisions
- Procurement & supply-chain resilience: Tariff shifts and raw-material volatility have raised the effective cost of imported assemblies and increased lead-time risk. For 2026 sourcing strategies, companies must evaluate blended sourcing approaches—combining local OEM partnerships, nearshoring, and dual-sourcing contracts—to protect margins and uptime.
- R&D and product roadmap prioritization: Regulations and customer expectations are accelerating demand for hoses that support tighter thermal tolerances, improved coolant compatibility, and compatibility with electrified powertrains. Prioritizing materials innovation and sensor-integration readiness will unlock OEM contracts and aftermarket premium positioning.
- M&A and partnership targeting: The market is moderately consolidated at the top but remains accessible for strategic acquisitions that deliver material- or channel-specific capabilities (e.g., thermoplastic expertise, EV-ready assemblies, or regional OE penetration).
- Sustainability & product differentiation: Eco-friendly compounds and recycled-content hoses have moved from niche to measurable volume growth. Firms that operationalize circular-material inputs without sacrificing durability will command preferable OEM and aftermarket terms.
Key market dynamics shaping 2026 plays
- Regulatory tightening: Emission and engine-performance standards in major markets are increasing tolerance and durability requirements for coolant-system components. These rules are driving OEMs to mandate higher certifiable performance—particularly in thermal stability and compatibility with advanced coolants—creating a higher bar for supplier qualification.
- Trade policy and tariffs: The introduction of elevated tariff rates in recent years has prompted procurement realignment among both suppliers and carmakers. The net effect is accelerated localization of manufacturing footprint in key vehicle-production regions and a re-evaluation of long-term sourcing contracts.
- Materials and manufacturing evolution: Advances in thermoplastics and silicone compounding, combined with automated molding and assembly, have reduced production costs for higher-spec hose assemblies while improving consistency. These improvements support a premium over commodity rubber hoses for applications that require longevity and thermal precision.
- OEM vs aftermarket dynamics: OEM demand continues to be the primary driver of volume and specification escalation, while aftermarket channels remain an important volume and margin pool—particularly as vehicle fleets age and service intervals expand.
Competitive landscape — how incumbents are positioning
The market exhibits a blend of global industrial champions, vertically integrated OE suppliers, and specialized regional manufacturers. Top-tier players leverage scale, longstanding OE relationships, and product systems expertise; mid-tier and regional firms compete on customization, cost flexibility, and proximity to local OEMs.
Radiator Hose Market
- Gates Corporation (Colorado Springs, USA): A recognized leader in fluid-power and engine hoses, Gates combines deep aftermarket channels with robust OEM programs. Their strength lies in material engineering and breadth across molded, flexible, and braided constructions—allowing cross-application wins as thermal-management requirements evolve.
- Continental AG (Hanover, Germany): Through its ContiTech division, Continental emphasizes premium materials and integration-readiness, including sensor-enabled hoses. Their R&D focus is tailored to manufacturers that demand system-level thermal-management solutions.
- Dayco Products LLC (Lebanon, USA): Known for durable, OE-compliant molded hoses for passenger applications, Dayco’s value proposition centers on fitment fidelity and lifecycle performance—attributes that support OEM qualification cycles.
- Parker Hannifin (Cleveland, USA): With strengths in fluid management and high-pressure solutions, Parker serves both automotive and industrial/marine segments—offering cross-sector technology transfer opportunities.
- Hutchinson SA (Paris, France): Hutchinson’s vertical integration and tight European OEM partnerships make it a go-to supplier for customized thermal-management solutions.
- Toyoda Gosei, Sumitomo Riko, Tokyo Rubber (Japan): These firms are deeply embedded in high-volume OEM supply chains in Asia, with expertise in precision rubber compounds and mass-production methodologies.
- Goodyear & Fairchild Industries: Goodyear couples global OEM reach with sustainability narratives, while Fairchild offers engineering-led, custom assemblies attractive to specialized OEM lines.
Recent market moves underscore strategic priorities: major supply agreements have been signed to secure long-term OEM platforms, and several firms launched eco-focused or heavy-duty aftermarket lines to capture value across vehicle lifecycles. These developments illustrate the two-track strategy suppliers are pursuing—securing volume through OEM platforms while monetizing technological differentiation in aftermarket and specialty segments.
Market structure and opportunity pockets
The competitive structure is best characterized as moderately concentrated at the top. The largest suppliers account for a meaningful share of market revenue, yet there remains open opportunity for specialists and regional players to capture share through targeted capabilities—particularly in material science, short-cycle qualification, and regional manufacturing footprint.
Critical strategic questions for 2026 executives
- How will your sourcing policy mitigate tariff-driven cost inflation while preserving supplier innovation partnerships?
- Which product platforms require immediate redesign to meet emergent thermal and emissions standards; what is the short-list of materials/partners to accelerate those programs?
- Should capital be deployed to vertically integrate compound production, or to secure long-term supply agreements with low-cost regional manufacturers?
- Where is the best risk-adjusted return for M&A—technology (e.g., thermoplastic expertise), channel (aftermarket specialists), or geography (nearshore capacity)?
- How will sustainability objectives be reconciled with cost, performance, and OEM qualification timelines?
What PW Consulting’s full report delivers
Our full Radiator Hose Market study is built to turn insights into executable plans for 2026 and beyond. Key deliverables include:
- Robust market sizing and trend analysis with audited historicals and scenario-based forecasts through 2032, including sensitivity to raw-material pricing and tariff regimes.
- Actionable segmentation layers (by material technology, vehicle class, and regional manufacturing economics) and a supplier matrix that ranks partners by technical capability, scale, cost, and qualification lead-times.
- Regulatory-impact modeling tying emissions and thermal-performance standards to required material upgrades and qualification costs across major markets.
- Competitive benchmarking with supplier profiles, recent dealflow, and stratified go-to-market strategies for capturing OEM and aftermarket revenue.
- Supply-chain resilience playbook: dual-sourcing templates, nearshoring decision trees, and a procurement negotiation framework tailored to radiator-hose procurement cycles.
- Investment and M&A screening toolkit that scores targets across technology synergies, revenue accretion timelines, and integration complexity.
- Commercial playbooks for suppliers and OEMs—including price-to-win models, contract structures for multi-year supply, and aftermarket monetization plans.
Each chapter connects analytical outputs to executable next steps: templates for supplier scorecards, a phased qualification roadmap for advanced-material hoses, and modular financial models that let executives stress-test scenarios on tariff changes, material-cost swings, and EV adoption curves.
Next steps and how to use this preview
This preview is designed to help you prioritize initiatives for 2026 budget cycles—whether that means reallocating R&D spend toward thermoplastic or silicone development, accelerating supplier diversification, or exploring bolt-on acquisitions to close capability gaps. For teams preparing 2026 capital and procurement plans, the most immediate utility is to translate the macro trajectory and regulatory drivers outlined here into concrete supplier and product decisions.
To access the full dataset, segmented forecasts, and the models that underpin the recommendations above, request the complete PW Consulting Radiator Hose Market report. The report contains the granular splits and scenario tables that will enable you to cost and time any strategic option with confidence.
If you would like, our team can schedule a focused briefing to walk your leadership through the forecast sensitivities, the supplier scorecard, and the tailored action plan that aligns with your 2026 priorities.
For detailed analysis of this topic, please visit the official page: Radiator Hose Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com