

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Air Quality Sensor Market to Reach USD 10.14 Billion by 2032 at 7.9% CAGR

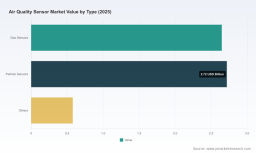
Air Quality Sensor Market — Strategic Outlook for 2026 Decision‑Making
As PW Consulting’s senior strategic advisory team and lead industry analysts, we present a high‑conviction introduction to our latest Air Quality Sensor Market study. Built on a 2025 base year and covering historical trends from 2020–2025 with forecasts through 2026–2032, the study quantifies a market that expanded from roughly USD 3.85 billion in 2020 to USD 5.95 billion in 2025 and is projected to reach about USD 10.14 billion by 2032, growing at a compound annual growth rate (CAGR) of 7.9% over the forecast horizon. This document explains why the research is strategically material for executive decision‑making in 2026 and how leaders should translate its insights into near‑term action.
Air Quality Sensor Market
Why this study matters for 2026 strategic choices
-
Timing meets inflection: the market’s sustained mid‑single digit CAGR masks rapid pockets of adoption across enterprise, industrial and smart‑building use cases. Executives who act in 2026 can lock in distribution, calibration and firmware advantages ahead of the next wave of adoption.
Air Quality Sensor Market -
Decision currency is precision: with adoption increasingly tied to regulatory reporting, workplace health programs, and asset protection, buyers now value validated performance, lifecycle economics and integration ease more than headline price alone. The report quantifies implications for total cost of ownership and return profiles across typical deployment lifetimes.
Air Quality Sensor Market -
Supply‑chain and raw material constraints are strategic levers: new export controls and raw‑material supply dynamics (notably in 2025–2026 policy shifts) materially increase the risk profile for sensor producers and integrators. Our modelling shows how sourcing strategies and design choices alter margin and availability outcomes.
-
Fragmented competitor landscape creates consolidation opportunities: concentration remains low, creating optionality for M&A, branded platform roll‑outs, and channel aggregation to capture economies of scale in calibration and SaaS‑enabled services.
Data‑driven view of market momentum
The market trajectory from 2020 through 2025 reflects broadening deployment beyond traditional environmental agencies into commercial real estate, occupational health, data centers and OEM device platforms. Our base‑case forecast yields an approximately 7.9% CAGR from 2026–2032, a rate driven by three interrelated vectors: regulatory tightening and public reporting requirements; proliferation of sensor‑enabled monitoring in buildings and industrial assets; and ongoing improvements in sensor integration and IoT platforms that lower implementation friction.
Critical to understanding that macro trend is practical granularity: the growth is not uniform by product architecture, by deployment environment, or by go‑to‑market model. The full study preserves that granularity through scenario analyses and sensitivity testing; the executive summary here focuses on strategic implications rather than granular slices.
What the full report delivers to executives (actionable content)
-
Robust market sizing and scenario forecasts with transparent methodology (base year 2025; historical 2020–2025; modeled scenarios to 2032), including upside/downside stress tests for regulation, component supply and technology adoption curves.
-
Go‑to‑market playbooks tailored to hardware OEMs, system integrators, facility managers and SaaS players — actionable channel tactics, pricing ladders, and calibration/service models.
-
Technology and product roadmaps: evaluation of sensing modalities, trade‑offs between MEMS, electrochemical and optical approaches, plus integration and firmware strategies that materially improve deployed accuracy and maintenance cycles.
-
Supply‑chain stress map and mitigation playbook: raw material dependencies, alternative sourcing, long‑lead item hedging and contractual design to reduce exposure to export controls and component shortages.
-
Commercial diligence package for investors: valuation sensitives, consolidation targets, and integration checklists for potential acquisitions.
-
Validation and testing matrix: recommended third‑party evaluation protocols (including field benchmarking and interoperability tests) and implications for warranty and SLA design.
-
Data toolkit (available in the paid report): interactive model, downloadable datasets and a prioritized list of questions for vendor RFPs — enabling teams to produce board‑level recommendations within weeks.
Competitive landscape — what players are doing and why it matters
The market remains structurally fragmented, with a top‑three share that reflects meaningful room for consolidation and differentiation. At a glance, the incumbents and notable challengers are pursuing distinct playbooks: industrial grade robustness and compliance, compact multi‑parameter modules for consumer and smart‑building OEMs, and highly accurate laboratory‑grade particle counters for research and regulatory customers.
-
Honeywell International Inc. (Charlotte, NC, USA) — industrial‑grade AQ systems (e.g., MIDAS, Sensepoint) aimed at commercial and heavy industrial settings. Their strategy centers on integration with building management and safety systems, emphasizing certified performance and aftersales service.
-
Sensirion AG (Staefa, Switzerland) — compact all‑in‑one environmental modules (SEN5x, SEN62 family). Sensirion’s product roadmap targets OEMs seeking turnkey sensor modules that minimize engineering burden and shorten time‑to‑market.
-
Bosch Sensortec GmbH (Reutlingen, Germany) — MEMS multi‑parameter solutions (BME690, BMV080) focused on size, power and integration for consumer and smart‑building devices where space and energy budgets are constrained.
-
Alphasense Ltd (Southampton, UK) — electrochemical and optical sensors for industrial and environmental monitoring; advancing sensor chemistries and recently launching new oxygen sensing chemistries to improve safety and accuracy profiles.
-
Figaro Engineering Inc. (Osaka, Japan) — long history in electrochemical gas detection with a focus on toxic gas monitoring and simple, robust modules favored in cost‑sensitive safety applications.
-
Siemens AG (Munich, Germany) — integrating refined user experiences (touch interfaces, mobile app integrations) with building automation to drive adoption among facility managers.
-
Teledyne Technologies , TSI Incorporated , 3M , and Aeroqual — each addresses adjacent niches from high‑precision scientific instruments to portable networks for outdoor monitoring and data center dust protection. Their strategies range from product specialization to platform bundling.
Recent product activity underscores a broader industry shift from single‑parameter, low‑cost devices to validated, multi‑parameter solutions and service‑enabled value propositions. Examples include Sensirion’s module integrations in late 2025, Alphasense’s oxygen sensor innovation in early 2026, AKCP’s targeted all‑in‑one device for data center protection in February 2026, and Siemens’ refreshed human‑centric sensing interfaces in late 2025. Collectively, these moves signal competing priorities: reliability, serviceability and integration rather than purely cost‑led competition.
Industry dynamics that should be on every 2026 agenda
-
Short‑lived low‑cost sensors: inexpensive devices often exhibit operating lifetimes measured in months rather than years, creating replacement and service markets but also increasing customer churn and trust issues. Product roadmap decisions must account for durability and recalibration economics.
-
Regulatory shifts: export control and raw‑material policy changes enacted in 2025–2026 increase procurement risk for certain sensor components. Companies must model procurement scenarios and qualify alternative suppliers to protect delivery and margin.
-
Third‑party validation rising in importance: independent field evaluation reports are shaping procurement decisions. Vendors that invest in transparent, third‑party testing and publish performance data will gain trust premium in procurement processes.
-
Services and software are becoming differentiators: data quality, analytics and predictive maintenance subscriptions materially increase lifetime value and create sustainable revenue streams beyond one‑time hardware sales.
Ten practical recommendations for executive teams in 2026
-
Prioritize product architectures that reduce recalibration frequency and simplify field servicing; design for real‑world longevity, not just lab accuracy.
-
Implement multi‑sourcing for critical components and include policy‑risk triggers into vendor contracts to mitigate export control shocks.
-
Invest in third‑party validation (AQ‑SPEC and equivalent) as a marketing and procurement prerequisite — it shortens sales cycles with enterprise buyers.
-
Bundle analytics, calibration and spare parts into subscription offerings to capture higher lifetime revenues and reduce churn.
-
Target consolidation opportunities selectively: focus on acquisitions that add calibration labs, software platforms or complementary channel reach rather than bolt‑on hardware alone.
-
Design product and pricing tiers for clear trade‑offs (accuracy, lifetime, connectivity) to avoid commoditization in entry segments.
-
Pilot smart deployment cases in buildings, data centers and industrial sites to prove ROI; use these pilots as reference accounts for scaling.
-
Ensure compliance teams are aligned with product and procurement to fast‑track approvals in regulated markets.
-
Allocate R&D to sensor fusion and firmware compensation algorithms — these often deliver more performance per dollar than marginal hardware improvements.
-
Prepare investor‑facing narratives that translate product roadmaps into cash‑flow milestones tied to subscription uptake and reduced warranty costs.
Why PW Consulting’s report is the pragmatic choice
Our study combines a transparent, defensible market model with operational playbooks, supplier diligence checklists and a field‑validation mindset. We synthesize primary interviews, product dissections, policy scenario planning and a downloadable modelling asset so teams can test specific strategic moves in their own P&L settings. The full report provides the detailed segment tables, regional and application splits, and vendor scorecards required to execute the recommendations above — information we intentionally withhold in this summary to preserve the strategic value of the full dataset.
For executives making procurement, product or M&A decisions in 2026, this report offers the calibrated, operationally focused intelligence needed to convert market growth into durable competitive advantage.
Accessing the full report unlocks the segmentation detail, vendor scorecards, downloadable models and the prioritized list of acquisition candidates referenced here. Contact PW Consulting for the full dataset and a tailored briefing for your leadership team.
For detailed analysis of this topic, please visit the official page: Air Quality Sensor Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com