

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Rubber Conveyor Belt Market to hit USD 4,460 Million by 2032 at 4.05% CAGR

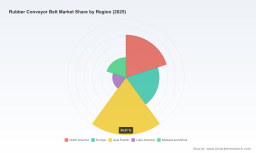
Rubber Conveyor Belt Market 2026: Strategic Preview for Decision-Makers
Executive Summary
As capital planners, procurement leads, and product strategists prepare for 2026, the rubber conveyor belt market presents a measured growth story—one that rewards precision in supply-chain planning, product differentiation, and regional go-to-market strategy. Our baseline analysis shows the market expanded from approximately USD 2,800 Million in 2020 to roughly USD 3,380 Million in 2025 and is projected to approach USD 4,460 Million by 2032. The forecast horizon (2026–2032) is characterized by a compounded annual growth rate (CAGR) of about 4.05%, reflecting steady demand across heavy industrial users, growing logistics infrastructure, and ongoing equipment replacement cycles.
Rubber Conveyor Belt Market
Why this matters for 2026 decisions
-
Procurement timing: With moderate, predictable growth rather than a boom, 2026 is a year to optimize contract cadence and hedging strategies rather than pursue aggressive spot-market buying.
Rubber Conveyor Belt Market -
CapEx versus service models: Stable CAGR favors shifting from CAPEX-heavy blanket purchases toward blended models (longer-life belts, managed services, and performance-based contracts) to improve return on invested capital.
Rubber Conveyor Belt Market -
M&A and capacity plays: The competitive structure—where the top-tier manufacturers command a material share but do not monopolize supply—creates opportunity for targeted acquisitions, joint ventures, or licensing arrangements to secure technical know-how and local market access.
Market trajectory and structural nuances
The market’s steady expansion masks important structural dynamics. Demand is anchored by mining and large-scale material handling, while industrial manufacturing and logistics continue to provide diversification. The growth path is not perfectly linear—short-term fluctuations reflect raw-material supply cycles and project-timing in capital-intensive end markets—but the longer-term trend is clear: rising global material-handling throughput, renewal of aging assets, and selective replacement with higher-specification belts (notably steel-cord reinforced constructions) underpin demand.
Notably, steel-cord constructions are forecast to outpace the average market growth rate, driven by their technical advantages—high tensile strength and low elongation—that enable longer single-flight conveyors, improved energy efficiency, and lower maintenance frequency. These technical traits are central to conversations about total cost of ownership (TCO) and sustainability, and they should inform product roadmaps and procurement specifications for 2026.
What the full report delivers (practical takeaways)
This research is built as a decision-support toolkit for executives and functional leaders. The outputs are designed for immediate operational use and medium-term strategic planning:
-
Market sizing methodology and historical trend validation (base year 2025, historical window 2020–2025, forecast 2026–2032).
-
Scenario-based demand models showing sensitivity to raw-material shocks, regulatory shifts, and mining capex timing.
-
Supply-chain mapping and cost-to-serve matrices that highlight where inventory, lead-times, and logistics create the largest margin leakage.
-
Competitive benchmarking templates that executives can use to assess product portfolios, service footprints, and aftermarket capabilities.
-
Procurement playbooks—RFP templates, scoring rubrics, and negotiation levers that reflect belt life-cycle economics rather than sticker price.
-
CapEx vs Opex decision frameworks and payback analyses for higher-spec belts, conveyor redesigns, and motor/belt efficiency projects.
-
Risk heatmaps: supplier concentration, raw-material dependency, and regulatory exposure with recommended mitigation steps.
-
Actionable KPIs for aftermarket and service business models (MTTR targets, predictive-maintenance penetration curves, spare-part inventory rationalization).
Competitive landscape — who matters and why
The market is moderately concentrated: the largest three suppliers control a significant share of industry sales, and the top five together command a majority of branded business. This structure creates distinct strategic vectors for suppliers and buyers:
-
Tier leaders focus on engineering differentiation, global distribution, and long-term contracts with major miners and logistics integrators.
-
Regional producers leverage price and local-service advantages, often pairing lower-cost manufacturing with rapid field support.
-
Mid-market manufacturers specialize in niche constructions (e.g., aramid, solid woven, specialty compounds) and aftermarket retrofit solutions.
Key players tracked in this study include established global manufacturers with distinct strategic postures:
-
SIG S.p.A. (Gorla Minore, Italy): Specialist in textile and steel carcass constructions for bulk handling; strong engineering pedigree for tailored conveyor solutions.
-
ContiTech (Hanover, Germany): Focused on energy-efficient and heavy-duty models across industrial and mining segments; recognized for belt-cleaner systems and supplier awards in key markets.
-
Zhejiang Double Arrow Rubber Co., Ltd. (Tongxiang, China): High-volume global producer with a broad product palette—fabric, steel cord, solid woven, and aramid belts—backed by international certifications and extensive export channels.
-
Fenner Dunlop Conveyor Belting (EMEA/AMERICAS): Durable offerings for mining and industrial applications with a strong aftermarket and distribution network.
-
The Yokohama Rubber Co., Ltd. (Hiratsuka, Japan): Leveraging a consolidated subsidiary structure in China to stabilize earnings and accelerate local production under medium-term plans.
-
Bando Chemical Industries, Ltd. (Kobe, Japan): Supplier of conveyor and power-transmission belts, pairing materials expertise with industrial customers’ reliability needs.
-
Qingdao Rubber Six Conveyor Belt Co., Ltd. (Qingdao, China): Regional manufacturer with brands that target both domestic and international aftermarket channels.
Recent corporate moves are instructive. Strategic consolidation and local capacity expansion—such as the establishment of wholly-owned conveyor-belt subsidiaries in China—signal a push by global players to shore up local margins and meet country-level market preferences. Similarly, market recognition in targeted geographies underscores the importance of field-proven performance and service in competitive differentiation.
Key dynamics to monitor in 2026
-
Raw-material and input-cost volatility: Price shifts in rubber, textile reinforcements, and steel cord can compress margins if not hedged or passed through in contracts. Longer-term sourcing partnerships and alternative compound development are practical responses.
-
Energy-efficiency and TCO demands: Buyers increasingly evaluate belts through the lens of energy consumption and maintenance cycles. Products that demonstrably lower energy use or downtime win specification share.
-
Aftermarket and services expansion: Service revenue—splicing, condition monitoring, scheduled maintenance—becomes a durable profit pool and a retention mechanism for suppliers.
-
Regulatory and localization pressures: Local content rules and industrial policy can reshape supply footprints quickly; manufacturers with flexible, localizable production models will have the advantage.
-
Technology adoption: Digital condition monitoring and predictive analytics are moving from pilot to procurement criterion, especially for high-value mining conveyors where downtime costs are high.
Implications for corporate strategy
For buyers: 2026 is the year to transition supplier relationships from transactional to performance-based models. Negotiate service-level agreements that align incentives, and prioritize belts and partners that reduce life-cycle cost, not just initial price.
For suppliers: Focus investments on product families that capture higher-margin growth (e.g., steel-cord reinforced systems, high-temperature compounds), strengthen aftermarket capabilities, and pursue selective vertical integration or partnerships to secure critical raw materials and technical IP.
For private capital and corporate development teams: The market structure favors bolt-on acquisitions that add technical capabilities, service footprints, or regional access. Due diligence should prioritize aftermarket revenue stability, backlog quality, and the target’s ability to meet increasingly stringent performance specifications.
Limitations of this preview and next steps
This article is a strategic preview. To preserve the value of the report as an operational asset, detailed subsegment tables, regional splits, and granular application-dollar breakdowns are not reproduced here. The full PW Consulting study includes complete datasets, supplier scorecards, downloadable models, and a set of ready-to-use procurement templates that enable immediate deployment in 2026 planning cycles.
To obtain the full report, detailed tables, and the interactive model that underpins these insights, please access the PW Consulting market portal. The complete dataset will allow you to run bespoke scenarios (e.g., commodity shock impacts, regional demand shifts, supplier failure scenarios) and extract the precise inputs you need for capital allocation, sourcing optimization, and product development roadmaps.
Closing note
Steady market growth, selective technical-driven outperformance (notably in steel-cord constructions), and a competitive landscape that rewards service-rich propositions define the 2026 opportunity set. Executives who act early—refocusing procurement on TCO, investing in aftermarket services, and selectively consolidating supply—will convert the market’s predictability into competitive advantage.
For detailed analysis of this topic, please visit the official page: Rubber Conveyor Belt Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com