

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Hexanoic Acid Market Set for 6.5% CAGR Through 2032

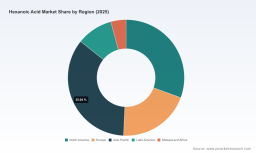
Hexanoic Acid Market: Strategic Outlook for 2026 Decision-Making
As PW Consulting’s senior industry analyst, I present a focused strategic primer on the Hexanoic Acid market intended to orient executive decisions in 2026. This essay synthesizes the macro trajectory, structural dynamics, competitive posture, and actionable playbooks that senior leaders—procurement chiefs, business unit heads, and investors—must consider before committing capital or revising commercial strategies. It intentionally surfaces high-value, decision-relevant insight while preserving the granular segmentation tables and models found in the full report.
Hexanoic Acid Market
Macro snapshot: where the market stands and where it’s heading
Using 2025 as the analytical base, the Hexanoic Acid market has expanded from an estimated USD 200 million in 2020 to approximately USD 255 million in 2025. Our baseline forecast for the 2026–2032 period assumes a compound annual growth rate of 6.5%, taking the market to roughly USD 396 million by 2032. The near-term bump between 2025 and 2026 reflects continued recovery in end-use industries—food & beverage, personal care, pharmaceuticals and industrial applications—and the early effects of premiumization driven by regulatory and quality requirements.
Hexanoic Acid Market
Two structural themes underpin this trajectory. First, a bifurcation is emerging between commodity-grade supply and premium, regulatory-driven high-purity grades; regulatory shifts and rising demand in pharmaceutical and personal care segments are accelerating adoption of higher-purity specifications in critical markets. Second, feedstock economics and traceability requirements are moving from a procurement footnote to a central strategic risk: raw materials sourced from palm kernel and coconut oils account for the single largest input cost in the value chain, making feedstock exposure a primary driver of supplier margins and buyer pricing.
Hexanoic Acid Market
What the full report delivers (practical modules for 2026 action)
- Integrated demand forecast (2026–2032) with price-elasticity overlays by end-use and purity grade, delivered as scenario-ready spreadsheets.
- Supplier landscape and capability mapping, including high-resolution scorecards for specialty producers, integrated chemical majors, and oleochemical houses—covering capacity, product purity range, certification readiness, and contract flexibility.
- Feedstock sensitivity models and OPEX simulators that quantify margin impacts from palm kernel and coconut oil price swings, and that model hedging and contract strategies.
- Regulatory impact matrix (REACH, CLP, FDA GRAS status, EU flavoring standards) with compliance checkpoints and cost-to-compliance estimators for common market-entry scenarios.
- Commercial playbooks and negotiation templates: long-term offtake frameworks, take-or-pay alternatives, indexation clauses, and escalation mechanics tailored to hexanoic acid and its derivatives.
- CapEx prioritization and brownfield/greenfield investment guidance, with throughput breakeven banding across purity grades and product derivatives.
- M&A and partnership target shortlists, with rationale and integration risk mapping for strategic buyers and private equity.
- Three fully stress-tested market scenarios (baseline, upside premiumization, downside feedstock shock) with implications for capacity utilization, margin compression, and working capital needs.
Competitive landscape: players to watch and strategic moves
The market exhibits a mix of specialty chemical houses, integrated chemical majors, targeted high-purity resellers, and oleochemical producers. Each cohort presents different implications for supply risk, price stability and strategic partnering.
- Perstorp Holding AB (Sweden) — a leader in specialty carboxylic acids and oxo-chemicals. Recent corporate activity reinforces Perstorp’s pivot toward premium, regulated markets: a capacity expansion announced in early 2026 prioritizes pharmaceutical and premium personal care grades, and a global pricing action in spring 2026 signals willingness to defend margins in the face of rising feedstock and input costs. For buyers, Perstorp’s moves suggest a tightening of available specialty capacity and an elevated premium for regulatory-compliant grades.
- Eastman Chemical Company (United States) — an integrated manufacturer with broad downstream applications. Eastman’s scale and product breadth make it a strategic supplier for diversified buyers but also a competitive pressure for specialty margins when they opt to compete on volume rather than premiumization.
- OXEA GmbH (Germany) & BASF SE (Germany) — European-focused suppliers with strong industrial and food-grade capabilities. Their presence means European buyers can access high-quality materials locally, but also face tighter regulatory alignment (REACH/CLP) that has pushed market preference toward higher-purity specifications.
- Tokyo Chemical Industry (TCI) — a global supplier of research and high-purity chemicals. TCI is a go-to for small-batch, high-purity requirements and serves as a barometer for demand in R&D and flavors/fragrance applications.
- KLK OLEO & IOI OLEO (Malaysia) — oleochemical producers supplying palm kernel–derived caproic/hexanoic acids. Their competitive edge is cost and proximity to feedstock, but growing demand for traceability and certification is forcing additional investment in documentation and processing to meet food-grade and EU market requirements.
Collectively, the competitive picture suggests a market that is neither a tight oligopoly nor a pure commodity field. Top suppliers hold technological, regulatory or feedstock advantages, but no single cohort dominates to the extent that a full-scale pricing cartel is feasible—presenting both opportunities for aggregation and risks of opportunistic price moves during tight feedstock cycles.
Key dynamics and risk factors to bake into 2026 decisions
- Feedstock concentration: reliance on palm kernel and coconut oil creates exposure to agricultural cycles, geopolitical risks, and sustainability scrutiny. In practical terms, feedstock costs represent the majority of production operating expenses, so even moderate swings transmit quickly to supplier pricing and buyer margins.
- Regulatory premiumization: stricter regional regulations and acceptance criteria for flavoring and pharmaceutical uses have accelerated adoption of higher-purity grades in several jurisdictions. Firms lacking compliant production lines will face margin erosion or market exclusion.
- Sustainability and traceability: buyers—especially in Western Europe—are increasingly demanding documented origin and certification for bio-based variants. Suppliers that can demonstrate chain-of-custody and food-grade certifications capture premium positioning.
- Supply-side moves: announced capacity additions and price actions by specialty producers are tightening the mid- and high-purity market segments; buyers should expect a divergence between commodity and premium pricing trajectories.
A 2026 strategic playbook—what to do now
- For buyers: prioritize contractual flexibility. Layered procurement (short-term spot exposure plus a core of indexed multi-year agreements) reduces volatility while preserving upside capture. Build feedstock-pass-through clauses and clear quality acceptance windows into contracts.
- For manufacturers and formulators: invest selectively in high-purity capability and certification. The premium for regulatory-compliant, traceable product often justifies modest CapEx, particularly where pharmaceutical or personal care applications are targeted.
- For oleochemical suppliers: accelerate traceability programs and invest in upstream farmer engagement to lock in supply and certification. This both de-risks feedstock chains and positions producers to command higher value in food-grade markets.
- For investors and corporate development teams: prioritize targets that offer either pure-play specialty capabilities or vertically integrated feedstock control. Consolidation opportunities exist in mid-sized specialty producers and regional oleochemical suppliers where value can be realized by combining traceability, regulatory know-how, and distribution reach.
Scenario outlook and sensitivity considerations
Our scenario workbench highlights three plausible paths:
- Baseline: sustained 6.5% CAGR with gradual premiumization—favours suppliers with regulatory-ready capacity and buyers with balanced contract portfolios.
- Upside: accelerated premium adoption and faster growth in pharmaceutical/personal care—rewards rapid certification and capacity-expansion winners; spot shortages occur if specialty capacity lags.
- Downside: sharp feedstock price shock or trade disruption—favours vertically integrated suppliers and buyers with robust hedging and diversified sourcing.
Each scenario alters optimal capital allocation, inventory policy, and commercial posture. The full report provides the models to stress-test balance sheets and to quantify the P&L impact across scenarios.
Conclusion: the strategic value of rigorous, operational intelligence
Hexanoic acid is no longer a simple commodity tucked inside larger formulations; it occupies a strategic crossroad where regulatory dynamics, feedstock economics, and product-grade differentiation intersect. For 2026 decision-makers, the most immediate priorities are: lock flexible supply, invest in high-purity capability where justified, and hardwire feedstock risk into commercial contracts.
PW Consulting’s full Hexanoic Acid Market report contains the granular segmentation, supplier scorecards, pricing ladders and downloadable scenario models that operational teams need to execute these recommendations. This introduction provides the decision framework and strategic signposts; the complete dataset and playbooks are available in the full publication for teams ready to act on a market that is both growing and re-shaping itself under regulatory and sustainability force-multipliers.
For detailed analysis of this topic, please visit the official page: Hexanoic Acid Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com