

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Liquid Biopsy Market Poised for 14.85% CAGR Through 2032

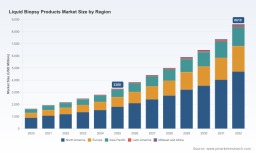
Liquid Biopsy Products Market: Strategic Preview for 2026 Decision-Makers
As healthcare systems, biopharma sponsors, and diagnostic platforms race to shift cancer care from episodic to continuous, liquid biopsy has moved from promising research tool to commercial inflection point. Our new PW Consulting market study—anchored to a 2025 base year and projecting through 2032—quantifies that transition and translates it into clear strategic choices for organizations planning budgets, partnerships, and product roadmaps in 2026. This brief serves as a trailer: it highlights the analytic depth and practical frameworks contained in the full report while deliberately withholding granular segment tables and proprietary allocations to encourage direct access to the primary release.
Liquid Biopsy Products Market
Why 2026 is a Strategic Inflection for Liquid Biopsy
- Compounded market expansion: The liquid biopsy products market is on a sustained, double-digit trajectory with a modeled CAGR of approximately 14.85% over our forecast window. From a 2025 base market value of roughly USD 3.3 billion (revenue unit: Million USD), the opportunity scales materially through 2032 in both clinical and research settings.
- Commercialization momentum: Between 2020 and 2025 the market exhibited consistent year-on-year expansion as technologies matured, reimbursement pathways began to stabilize, and multi-stakeholder clinical adoption increased—setting the stage for accelerated commercialization in the second half of the decade.
- Market concentration: The competitive landscape shows a moderate concentration with the top three and top five vendors collectively commanding a majority of the market. This structure creates both barriers and strategic openings for challengers depending on the chosen niche and go-to-market approach.
What’s Driving Growth—and What Will Change in 2026
Our analysis distills four converging forces that will crystallize in 2026 and determine winners and losers:
Liquid Biopsy Products Market
- Clinical utility expansion: Liquid biopsy use cases continue to broaden beyond therapy selection to early detection, minimal residual disease (MRD) monitoring, and pharmacogenomics adjuncts. The rate at which payors and guideline bodies recognize these applications will be a dominant determinant of near-term commercial scale.
- Technology specialization: Next-generation sequencing (NGS), ultra-sensitive PCR modalities, and bioinformatics platforms are evolving in parallel. Competitive advantage will increasingly accrue to integrated solutions that couple assay sensitivity with scalable sample-to-answer workflows and interpretive AI.
- Regulatory clarity and approvals: The cadence of regulatory submissions and approvals for multi-cancer early detection and companion diagnostics will reshape adoption curves. High-profile filings and submissions in late 2025 and early 2026 have signaled a coming wave of regulatory decisions that could unlock major commercial pathways.
- Partnerships and site-of-care expansion: Public-private partnerships, hospital-based on-site services, and vertically integrated offerings are reducing time-to-result and strengthening clinical trust. Organizations that can operationalize on-site or near-site testing models will capture demand tied to rapid clinical decision-making.
Competitive Landscape: Strategic Profiles and Strategic Implications
The market is populated by legacy life-science platforms, specialized diagnostics houses, and AI-enabled analytics firms. Below are distilled strategic profiles of representative players examined in our study and the implications for 2026 strategy.
Liquid Biopsy Products Market
- Guardant Health, Inc. — Positioned as an integrated liquid biopsy service and assay provider with on-site partnerships and end-to-end clinical workflows. Strategic implication: incumbency in service delivery gives Guardant a foothold in clinical adoption, making them a likely counterparty for hospital systems seeking turnkey solutions.
- Illumina, Inc. — A platform provider whose NGS instruments and sequencing kits underpin many third-party assays. Strategic implication: Illumina’s strength lies in enabling ecosystems; competitors must decide whether to align with dominant platform vendors or invest in platform independence.
- F. Hoffmann‑La Roche Ltd. — A developer of targeted oncology assays with deep clinician relationships. Strategic implication: Roche will likely leverage commercial reach and companion diagnostic pathways to convert clinical evidence into sustainable uptake.
- QIAGEN N.V. — A supplier focused on sample prep and reagents for liquid biopsy workflows. Strategic implication: Players controlling pre-analytic steps can influence assay reproducibility and clinical reliability—making reagent/instrument bundling a strategic lever.
- Thermo Fisher Scientific Inc. — Offers digital PCR and NGS solutions aimed at both research and diagnostics customers. Strategic implication: Broad product portfolios create cross-selling opportunities into biopharma workflows and clinical labs.
- Myriad Genetics, Inc. & Exact Sciences Corporation — Both have advanced multi-cancer testing ambitions, emphasizing early detection and population screening approaches. Strategic implication: Success in multi-cancer early detection will hinge on evidence generation and payer acceptance; investments in longitudinal studies are high-payoff but capital intensive.
- Bio-Rad Laboratories, Inc. & SOPHiA GENETICS — Focused on assay reagents and AI-driven interpretation respectively. Strategic implication: The intersection of robust chemistry and sophisticated analytics will define differentiated clinical value, especially for decentralized diagnostics.
Recent ecosystem moves illustrate how strategy is playing out in real time. Notable near-term developments include a product expansion in early 2026 by a precision diagnostics vendor that enhances pharmacogenomic and clonal hematopoiesis insights; a late-2025 announcement by a leading liquid biopsy services provider to deploy on-site testing at a major European hospital; and a regulatory submission for a multi-cancer early detection test in early 2026. Each event underlines the dual engines of technology evolution and regulatory validation driving 2026 market dynamics.
Actionable Strategic Framework for 2026
For executives revising plans in 2026, the report delivers a decision framework organized around portfolio, partnerships, and operational readiness. The following high-level actions should be considered as part of an immediate strategic playbook:
- Prioritize use-case sequencing: Differentiate between early detection, MRD, and therapy selection. Invest in evidence generation proportional to the commercial runway and reimbursement complexity of each use case.
- Choose a platform strategy: Decide whether to be an assay-first company allied with platform providers, to develop proprietary instrumentation, or to specialize in pre-analytic or analytics layers. Each route requires distinct capital profiles and partnership ecosystems.
- Design clinical evidence roadmaps: Pair clinical pilot programs with payer engagement and health economics studies from the outset; early alignment with key opinion leaders and clinical networks reduces commercialization friction.
- Operationalize flexibility: Build modular lab and IT operations that can pivot between centralized and decentralized testing as demand and regulatory constraints evolve.
- Negotiate strategic partnerships: Use the market concentration dynamics to your advantage—selective partnerships with incumbent leaders can accelerate market access, while targeted alliances with niche innovators can create differentiation.
What the PW Consulting Report Contains (Practical, Executable Deliverables)
The full study is explicitly designed for commercial and corporate strategy teams making 2026 decisions. Core deliverables include:
- Market sizing and forecasting model (2020–2032) with transparent assumptions and sensitivity testing to stress-test adoption scenarios under varying regulatory and reimbursement timelines.
- Buy-side segmentation and adoption archetypes that map clinical customer journeys, decision triggers, and procurement constraints—helpful for sales targeting and evidence planning.
- Technology roadmaps comparing NGS, PCR variants, and emerging platforms along dimensions of cost-per-sample, sensitivity thresholds, throughput, and compliance readiness.
- Competitive landscaping with revenue bands, strategic positioning maps, and playbooks for partnerships, M&A, and defensive moves—complete with public-company comparable benchmarks and KOL quotes synthesized from primary research.
- Commercial go-to-market templates addressing pricing strategy, channel selection, and payer engagement playbooks tailored to hospital systems, reference labs, and biopharma clients.
- An executable 18-month strategic plan template that translates insights into prioritized investments, KPIs, and a resourcing roadmap for rapid deployment.
How to Use This Preview
This preview highlights the contours of a market that expands from a 2025 base of approximately USD 3.3 billion to a substantially larger opportunity by 2032 (with modelled escalation consistent with a mid-teens CAGR). It summarizes competitive positions, recent strategic moves, and the core choices leaders must make in 2026. For teams facing capital allocation decisions, partnership negotiations, or product roadmap re-scoping, the full report provides the granular segmentation, quantified scenario outputs, and consultant-grade playbooks necessary to execute with confidence.
Next Steps
If your 2026 planning cycle hinges on clear answers—how to prioritize clinical evidence investments, which partnerships to pursue, or how to structure a regional launch—the PW Consulting liquid biopsy market study offers the calibrated, actionable intelligence you need. The full release contains the confidential segment matrices, regional and application breakdowns, and financial models intentionally omitted from this public preview. Accessing the complete report will enable you to move from strategic intent to operational readiness with a defensible roadmap backed by data and consulting-grade recommendations.
For detailed analysis of this topic, please visit the official page: Liquid Biopsy Products Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com