

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Laser Capture Microdissection Market to Hit USD 230 Million in 2025 at 8.55% CAGR

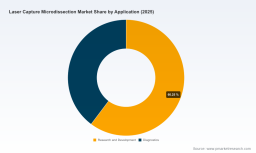
Laser Capture Microdissection Market — Strategic Briefing for 2026 Decision-Making
As organizations plan capital allocation, product roadmaps, and commercial strategies for 2026, Laser Capture Microdissection (LCM) occupies a unique intersection of precision biology, diagnostics innovation, and capital-intensive instrumentation. PW Consulting’s new market research positions LCM not as a niche laboratory technique but as a growing platform technology whose adoption and monetization pathways are being reshaped by reimbursement recognition, automation trends, and changing operating models in core facilities. Anchored to a 2025 base year and modeled across a 2026–2032 forecast horizon, the market expands at a compound annual growth rate of 8.55%, rising from a mid‑hundreds‑of‑millions base in 2025 toward a substantially larger opportunity by 2032 (all figures in USD Million). This briefing summarizes the study’s strategic value for executives and investment committees while intentionally holding back the granular splits reserved for subscribers to the full report.
Laser Capture Microdissection Market
Why this study matters for 2026
-
Timing of investment cycles — LCM procurement is capex‑intensive and adoption commonly follows institutional budgeting cycles. The dataset in this study identifies short‑term inflection points and procurement windows that will determine whether 2026 becomes a breakout year for device upgrades or a consolidation year for existing core facilities.
Laser Capture Microdissection Market -
Commercial levers are shifting — revenues are increasingly driven by a combination of instrument sales, recurring consumables/reagents, and software/service bundles. Understanding attach rates and service economics is now as important as device performance.
Laser Capture Microdissection Market -
Regulatory and reimbursement changes are material — the recent private‑payer recognition of CPT 0249U for oncology semiquantitative analysis is already altering project economics for clinical and translational labs that can bill for downstream workflows that rely on microdissection.
-
M&A and partnership timing — with a moderately concentrated supplier base (CR3 and CR5 metrics indicate that the top vendors hold meaningful shares of industry revenue), strategic partnerships, bolt‑on acquisitions, and distributor agreements are viable routes to scale faster than greenfield market entry.
What the report delivers — practical, decision‑grade outputs
-
Market sizing and scenario models: base, conservative, and upside forecasts from 2026–2032 (base year 2025), including sensitivity analyses that quantify the impact of reimbursement uptake, price erosion, and automation on total addressable revenue.
-
Procurement playbooks for hospitals, academic cores, and contract research organizations (CROs) that balance capex constraints with throughput requirements and service-level needs.
-
Vendor benchmarking toolkit: comparative scorecards across hardware capability, consumable ecosystem, service footprint, software interoperability, and total cost of ownership (TCO).
-
Commercial frameworks: recurring revenue strategies (consumable bundling, reagent subscriptions), go‑to‑market segmentation, pricing scenarios, and distributor models tailored to developed and developing markets.
-
Operational diagnostics: adoption barrier diagnostics and remediation playbooks covering staffing, workflow standardization, training programs, and sample integrity controls.
-
M&A and partnership matrices: diligence checklists, valuation multiples observed in adjacent life‑science tools segments, and playbooks for onboarding acquired IP and service networks.
Market dynamics executives must factor into 2026 plans
-
Reimbursement is a tipping point. The growing recognition of specific CPT codes relevant to oncology semiquantitative analyses materially improves the unit economics for clinical labs adopting LCM workflows. Organizations planning to monetize LCM in clinical pipelines should model conservative and accelerated uptake scenarios tied to payer adoption rates.
-
Capital intensity remains a constraint. LCM instrumentation continues to be a meaningful capital commitment for labs; typical single‑unit capital costs sit in a high five‑figure to low six‑figure range. That cost profile drives a preference for shared core facilities, leasing, and multi‑institution procurement models in constrained settings.
-
Labor availability is a practical adoption limiter. Staffing shortages and specialized training requirements dampen rapid, decentralized deployment—favoring installations in centralized cores that can amortize operator expertise and automation investments.
-
Concentration enables strategic approaches. Market concentration metrics show that a small set of vendors account for a majority share of global revenues; this creates leverage for downstream partners but also competitive pressure for entrants to differentiate on service, consumables, or software.
Competitive landscape — what leading vendors are doing and why it matters
The competitive topology is characterized by a mix of legacy manufacturers and specialized niche players, each pursuing different paths to capture instrument and recurring revenue. The report includes detailed profiles and strategic implications for the major incumbents; below are the headlines and actionable takeaways.
-
Thermo Fisher Scientific — historically associated with the Arcturus LCM line (now commercialized by a partner), Thermo Fisher’s footprint in LCM architectures has shaped customer expectations around reliability and integration. For buyers, legacy vendor relationships can simplify procurement and service but may not always represent the best consumables economics.
-
Laxco, Inc. — as the commercial custodian of the Arcturus lineage in certain markets, Laxco has positioned its Accuva Cellect systems around IR laser capture and tissue‑preserving workflows. The company exemplifies how focused platform stewardship can convert legacy installed bases into recurring revenue via kits and reagents.
-
Molecular Machines & Industries (MMI) — MMI’s CellCut platform and automation options emphasize single‑cell precision and contamination control. Their route-to-market highlights the value of automation in labs where throughput and contamination risk are critical decision factors.
-
Carl Zeiss — with PALM systems integrated into high‑end microscopy ecosystems, Zeiss plays to clients that prioritize imaging‑driven workflows and downstream genomic fidelity. Their approach underscores the strategic cross‑sell opportunity when microdissection is embedded into broader imaging‑centric purchases.
-
Leica Microsystems — Leica’s LMD family competes on laser precision and collection flexibility. Recent product demonstrations at academic cores signal continued investment in customer education and pilot installations that reduce adoption friction.
Strategic implications for vendors and buyers:
-
Vendors: prioritize service networks and consumables ecosystems to convert installed base into annuity streams; software and reagent lock‑in are powerful churn reducers.
-
Buyers: evaluate vendor offers on TCO, training commitments, and consumable pricing rather than instrument list price alone—shared core and leasing models may achieve better throughput economics.
-
Private equity and strategic buyers: consolidation opportunities are present where a platform can provide distribution reach for specialized consumables or standardize automation across a fragmented installed base.
Scenario planning and what moves the needle
Our modeling identifies a short set of high‑impact variables that change the forecast trajectory materially:
-
Reimbursement adoption rate for newly recognized codes — faster payer acceptance converts translational use cases into billable clinical workflows.
-
Automation and software integration — improvements that reduce operator time-per-sample can shift demand from centralized cores toward distributed lab models.
-
Consumables attach rates — modest improvements in kit and reagent uptake per instrument can drive significant recurring revenue uplift without corresponding increases in capital deployment.
-
Pricing and financing innovations — leasing, reagent subscriptions, and pay‑per‑use offerings reduce entry barriers in cash‑constrained institutions and accelerate unit placements.
The report’s detailed scenarios translate these drivers into financial outcomes across the 2026–2032 horizon (base year 2025), allowing procurement teams and investors to stress‑test strategic choices under plausible market evolutions.
Adoption barriers and actionable mitigations
-
Barrier — High initial capital outlay: Mitigation — structured leasing, consortium purchasing, and rental-to-own models that align cost with throughput realization.
-
Barrier — Skilled operator scarcity: Mitigation — vendor‑led training hubs, remote operation software, and certification programs that create staffing pools across institutions.
-
Barrier — Workflow standardization: Mitigation — validated sample prep kits, standardized SOPs, and turnkey service contracts that reduce analytical variability and time to CLIA/CAP readiness.
-
Barrier — Clinical validation and billing complexity: Mitigation — pilot programs that document clinical utility and billing workshops that map laboratory workflows to payer coding strategies.
How PW Consulting’s deliverables convert insight into action
-
Decision‑grade dashboards and downloadable financial models built on the 2025 base and 2026–2032 forecast allow scenario updates with client‑specific inputs (pricing, attach rates, reimbursement timelines).
-
Vendor scorecards and procurement templates are engineered for rapid onsite use during tender evaluations and can be customized for institution size and use case.
-
Go‑to‑market playbooks for vendors include prioritized channel strategies, partnership archetypes (distributors, reagent alliances, imaging OEM bundling), and recommended pilot designs to shorten sales cycles.
Next steps — where to get the full intelligence
This briefing highlights the strategic contours of the LCM market and outlines the levers that will determine winners and laggards in 2026. To preserve the commercial value of the granular datasets, regional and application level splits, and the full vendor benchmarking matrices have been curated in the complete report. Executives preparing procurement decisions, commercial leaders shaping revenue plans, and financial sponsors evaluating M&A opportunities should access the full report for the underlying tables, methodology notes, and the editable financial model.
For tailored briefings, scenario workshops, or to license the underlying forecast model for internal planning, contact PW Consulting. Our advisory teams will walk through bespoke sensitivity runs aligned to your pricing, channel, and service assumptions—and help convert the 8.55% CAGR opportunity into executable 2026 outcomes.
For detailed analysis of this topic, please visit the official page: Laser Capture Microdissection Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com