

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: VCI Anti-Rust Paper Market Set for 4.8% CAGR to 2032

VCI Anti Rust Paper Market — Strategic Preview for 2026 Decision-Makers
As PW Consulting’s Senior Strategy Advisor and Chief Industry Analyst, I present a focused, action-oriented briefing to frame the strategic questions your leadership team must answer in 2026. This preview synthesizes market trajectory, competitive dynamics, regulatory inflection points, and concrete go-to-market plays that matter when allocating R&D budgets, negotiating supply contracts, or evaluating M&A targets in the VCI anti rust paper sector.
VCI Anti Rust Paper Market
Why this moment matters
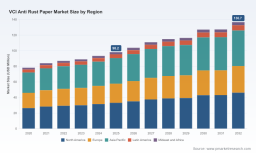
The VCI anti rust paper market is on a steady growth path: our base-year assessment (2025) places the market at USD 98.2 Million, growing from roughly USD 78 million five years earlier, and our forecast shows expansion to about USD 136.7 Million by 2032 at a compound annual growth rate (CAGR) of 4.8% (forecast period: 2026–2032). That trajectory signals continued demand tied to metal-intensive supply chains, but it also underlines two concurrent imperatives for market participants: protect margin through product premiumization and mitigate regulatory and raw-material risks through rapid reformulation and supply diversification.
VCI Anti Rust Paper Market
Key market characteristics (what we reveal and what we withhold)
- We confirm a market structure with a notable degree of concentration: the top three players control a meaningful majority share (CR3 ~62.5%), and the top five increase that concentration further (CR5 ~78.2%). This creates both barriers and openings—scale advantages for incumbents, and niche entry points for differentiated propositions.
- We disclose the high-level time-series growth and the macro CAGR to ground investment calculus. What we do not disclose in this preview are the granular region-by-region and application-by-application split percentages. Those core segmentation figures, unit economics by substrate and by protection duration, and the full company-level revenue tables are retained for the full report—because these details are the transaction-grade intelligence that shift procurement negotiations and M&A valuation assumptions.
Market dynamics shaping 2026 decisions
- Regulatory pressure is a design constraint. Across the EU and select U.S. subnational jurisdictions, tightening chemical restrictions (notably under REACH and RoHS in Europe) and escalating VOC controls (such as CARB-driven standards) are forcing reformulations away from legacy amine- and nitrite-based chemistries and from certain plasticizers. Firms that pre-emptively retire restricted actives reduce transition risk and avoid sudden re-tooling costs.
- Raw material and logistics cost volatility compresses margins. Inflation in specialty amine chemistries, coupled with elevated freight and conversion costs, is squeezing manufacturers. Companies that lack upstream hedges or flexible formulations face margin erosion unless they move to value-added service models or premium pricing.
- Product convergence and feature integration are accelerating. Innovations that combine mechanical protection (cushioning, tear resistance) with vapor-phase corrosion inhibition are gaining traction. Recent product activity illustrates this: in May 2026, HexcelPack and Armor Protective Packaging launched an integrated VCI cushioning paper that bundles damage mitigation with corrosion protection—an archetype of what customers increasingly prefer.
- Customer buying behavior is becoming solution-driven. Procurement teams are prioritizing total cost of ownership—corrosion risk mitigation, inventory shrinkage reduction, and sustainability credentials—over unit price alone. Suppliers that can quantify TCO improvements command pricing power.
Competitive landscape — who plays and how they compete
The competitive field is a mixture of specialized chemists, packaging converters, and hybrid players. Below are concise strategic profiles of key incumbents that define the competitive baseline for 2026:
VCI Anti Rust Paper Market
- Cortec Corporation (St. Paul, Minnesota) — Positions on sustainability and repulpable chemistries with products designed for ferrous and non-ferrous storage/shipping. Strength: brand recognition in engineered VpCI chemistries and an emphasis on renewable substrates.
- Daubert Cromwell (Alsip, Illinois) — Known for nitrite-free VCI offerings and military-grade specifications. Strength: specifications-driven sales into defense and high-reliability manufacturing customers.
- ZERUST / Northern Technologies (Beachwood, Ohio) — Focuses on vapor-phase protection and reinforced/poly-coated variants. Strength: integrated systems thinking—film, paper, and desiccants—paired with industrial distribution partnerships.
- Intertape Polymer Group (IPG, Charlotte, NC) — Leverages converter scale to offer extended-duration nitrite-free saturated papers. Strength: manufacturing scale and channel breadth for industrials and contract packagers.
- Armor Protective Packaging (Howell, Michigan) — Blends nanotechnology and renewable kraft substrates, and is aggressive on product innovation and brand launches. Strength: rapid commercialization of integrated mechanical/VCI products (e.g., HexcelWrap).
- Rust-X (USA) — Differentiates on mechanical robustness—laminated papers with superior tear and puncture resistance aimed at heavy-part protection. Strength: niche focus on damage prevention in addition to corrosion control.
Strategically, competitors cluster into two archetypes: (1) chemists/technology leaders who own proprietary VCI actives and differentiation through chemistry; and (2) converter-scale players who leverage manufacturing breadth and distribution to deliver integrated packaging systems. Success in 2026 requires crossing these two dimensions—either by partnering or by capability-building.
Actionable strategic priorities for 2026
Based on the market sizing, regulatory trajectory, and competitive patterns, we recommend five prioritized initiatives to preserve optionality and capture disproportionate upside as the market grows toward our 2032 projection.
- Accelerate compliance-first R&D: Target nitrite-free, low-VOC, and biodegradable VCI formulations. Time-to-market for compliant formulations is becoming a source of competitive advantage as regulatory calendars tighten.
- Move up the value chain with bundled solutions: Pilot integrated products that combine cushioning, strength, and VCI protection—these command higher margins and reduce price elasticity from buyers.
- Lock downstream channel partnerships: Secure preferred-supplier status with tier-1 OEMs in metal-intensive industries and with logistics integrators. Value-based contracting (e.g., pay-for-outcome warranties on corrosion performance) is a lever to improve realized pricing.
- Hedge input risk and rationalize SKUs: Implement dual-sourcing for critical actives and consider SKU rationalization to reduce conversion complexity and inventory carrying costs.
- Prepare M&A and strategic alliance playbooks: With a concentrated CR3/CR5 dynamic, bolt-on acquisitions or licensing deals can accelerate entry into regulated geographies or new substrate formats without building from scratch.
What the full PW Consulting market study delivers (practical, executable content)
Our full VCI Anti Rust Paper Market report is designed as a playbook—not an academic exercise. The deliverables include:
- Multi-year market-size model (2020–2032) with scenario sensitivity to raw-material inflation, regulatory shock events, and accelerated substitution timelines.
- Pricing and margin benchmarks by product formulation and protection-duration tiers, including break-even analyses for converters and white-label suppliers.
- Segment-level demand drivers (by end-use and region) alongside elasticities and procurement decision trees—presented with supplier scorecards and customer purchasing personas.
- Detailed competitive profiles (capabilities, product portfolios, patent positions, recent product launches, and go-to-market routes) with quantified risk/opportunity matrices for each named player.
- Compliance matrix mapping current and forthcoming regulatory regimes (EU REACH, CARB, RoHS and equivalents) to product reformulation roadmaps and certification timelines.
- Commercial playbooks—three GTM blueprints (enterprise OEM-direct, distributor-led rollouts, and integrated systems partnerships) with sample contracts, margin waterfall models, and pilot KPIs.
- Deal-support materials—valuations for probable targets, synergy capture estimates, and a prioritized M&A target shortlist conditioned on technological gap analyses.
Risk register and mitigation levers
- Regulatory shock: Maintain modular formulations so restricted actives can be substituted quickly. Pre-certify alternatives in key jurisdictions.
- Input-cost spikes: Implement indexed supply contracts and consider modest price escalators linked to recognized indices to protect near-term margin.
- Channel disruption: Build a two-tier distribution strategy—direct enterprise coverage plus strategic distributor partners—to preserve reach while controlling service economics.
- Competitive commoditization: Defend with outcome-based propositions (warranties, corrosion-failure reduction guarantees) supported by independent lab validation and field pilots.
Practical next steps for executive teams in 2026
- Run a 90-day “Regulatory Readiness” sprint to audit formulations, update MSDS, and obtain certifications for prioritized markets.
- Initiate two commercial pilots that pair an integrated VCI-cushioning product with a marquee OEM customer; measure TCO and damage/corrosion rate delta over a six-month window.
- Commission a supply-risk stress test for critical chemistries and set trigger-based procurement actions for dual-sourcing or inventory pre-positioning.
- Engage PW Consulting for a tailored valuation and M&A screening if inorganic expansion into proprietary chemistries or geographic footprint is under consideration.
Closing—why our intelligence changes decisions this year
The combination of steady market expansion (from roughly USD 78M in 2020 to USD 98.2M in 2025 and projected to reach about USD 136.7M by 2032 at a 4.8% CAGR), tightening chemical and emissions regulation, and accelerating product convergence creates an environment where proactive strategy materially outperforms reactive responses. Leaders who prioritize compliant innovation, integrated product design, and channel control in 2026 will not only protect margins but will capture share as procurement preferences shift to outcome-based purchasing.
This preview highlights strategic imperatives and competitive contours. Our full VCI Anti Rust Paper Market report contains the granular segmentation, end-user splits, unit-economics, and company-level financials that operational teams use to quantify opportunity and execute deals. To access the full dataset, scenario models, and playbooks, please consult the PW Consulting report page for the VCI Anti Rust Paper Market.
For detailed analysis of this topic, please visit the official page: VCI Anti Rust Paper Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com