

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Eye Wash Station Market to Reach USD 596M by 2032 at 4.65% CAGR

Eye Wash Station Market — Strategic Preview for 2026 Decision Makers
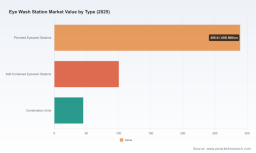
As companies reset safety, procurement, and product strategies for 2026, the Eye Wash Station market is evolving from a compliance-driven commodity into a space of differentiated service models, modular product innovation, and channel consolidation. PW Consulting’s latest study (base year 2025; forecast 2026–2032) synthesizes five years of historical performance with scenario-based forecasts and operational playbooks. At the market level, total industry revenue rose from approximately USD 300 Million in 2020 to about USD 435 Million in 2025, and under our central forecast grows to roughly USD 596 Million by 2032 — a compound annual growth rate of 4.65%. This preview explains the strategic value of that research for boardrooms and operating teams planning decisive moves in 2026, while intentionally withholding segmented datapoints to guide readers to the full report for transaction‑grade intelligence.
Eye Wash Station Market
Why this research is mission-critical in 2026
- Compliance is now a capital decision: stronger enforcement and clearer reference to ANSI/ISEA Z358.1 are forcing companies to convert compliance checklists into procurement budgets and ongoing service contracts.
- Risk-to-cost tradeoffs matter more: end users are weighing one-time capital installation against recurring service, testing, and asset management costs — the report models these tradeoffs under multiple scenarios.
- Channel and product choices have margin consequences: manufacturers, distributors, and end-user procurement organizations will need to reconfigure sales motions to capture aftermarket and service revenue.
- M&A and partnership windows are opening: given moderate market consolidation and numerous specialized OEMs and distributors, 2026 is a strategic moment for bolt-on deals and distribution partnerships.
Market dynamics you need to account for
Three structural dynamics drive investor and operator choices:
Eye Wash Station Market
- Regulatory tightening and standardization. OSHA’s continuing emphasis on immediate drenching facilities, and its reference to ANSI/ISEA Z358.1, mean that technical specifications (e.g., tepid water delivery for 15 minutes at specified flow rates) are not negotiable. The practical effect is predictable replacement and retrofit demand as facilities align installations, testing, and training processes with updated guidance.
- Service and total-cost-of-ownership (TCO) economics. Buyers increasingly evaluate life‑cycle costs — calibration, annual testing, replacement cartridges, and descaling — not just unit price. Vendors that pair hardware with recurring revenue models (service subscriptions, remote-monitoring upgrades) capture premium margins.
- Fragmentation with concentration pockets. The market is neither a pure commodity nor dominated by a tight oligopoly; leading vendors hold meaningful shares but a long tail of regional manufacturers and specialty suppliers keep the competitive landscape fluid. This creates both competitive threat and consolidation opportunity for larger players.
What the full PW Consulting report delivers (practical, actionable content)
The report is built to inform immediate strategic actions as well as six- to 36‑month plans. Key deliverables include:
Eye Wash Station Market
- Transparent methodology and reproducible sizing: detailed assumptions, data sources, and reconciliations that explain how the 2025 base and the 2026–2032 forecast were constructed.
- Scenario-based demand modeling: upside, base, and downside paths that stress-test assumptions on regulation, industrial CAPEX cycles, and supply constraints.
- Go-to-market playbooks: differentiated GTM strategies for OEMs, distributors, and integrators — including direct sales, channel enablement, e-commerce, and specification‑driven approaches for institutional buyers.
- Product and service roadmaps: prioritized feature sets, aftermarket bundles, and sensor/telemetry options that move buyers from transactional purchases to service-led relationships.
- Commercial benchmarking tools: price elasticity, gross margin ladders, and service-contract pricing templates to accelerate commercial decisions without bespoke analysis.
- Regulatory compliance checklist and training matrix: actionable templates that align manufacturer instructions, ANSI guidance, and OSHA requirements into installation, inspection, and audit-ready documentation.
- M&A and partnership heatmaps: acquisition targets by capability, distributor overlays, and partnership scenarios for rapid diligence.
- Risk matrix and mitigation plans: supply chain fragilities, single‑source dependencies, and quality assurance protocols with suggested mitigations.
Competitor landscape — how to interpret vendor strengths
The market includes established manufacturers, specialized regional players, and distributors that aggregate multiple OEMs. The following summaries highlight strategic positioning and what it implies for competitors and partners:
- Haws Corporation (Sparks, Nevada) — A recognized manufacturer with proprietary flushing technologies and a strong engineering pedigree. Haws competes on product performance and specification compliance; its strength lies in R&D and institutional sales. Strategic implication: Haws is a logical partner for spec-driven procurement and large industrial accounts seeking validated flushing performance.
- Guardian Equipment Company (Chicago, IL) — Known for a broad portfolio of emergency wash solutions compliant with ANSI/ISEA and OSHA. Guardian’s advantage is product breadth and channel reach; it excels in modular and combination units. Strategic implication: Guardian is positioned to capture both new-install and retrofit opportunities where compliance checks are a major procurement driver.
- Bradley Corporation (Menomonee Falls, WI) — Focuses on customizable solutions for high‑risk chemical exposure zones. Bradley’s ability to tailor units for specific environments makes it a preferred vendor for specialized industrial facilities. Strategic implication: partners and buyers seeking customization should prioritize engagement with Bradley for pilot projects and specification development.
- Speakman Company (New Castle, DE) — A supplier of plumbed and portable units with strong after-sales support. Speakman’s value proposition centers on replacement parts and maintainability, a critical factor for service-based business models. Strategic implication: Speakman is worth watching for distributors building a services-led offering.
- Haws Safety Products (Honeywell) — Leveraging a global brand and recognized product (Fendall®), Honeywell brings scale and an existing safety-products channel. Strategic implication: Honeywell’s involvement signals a move toward bundling safety offerings within broader corporate procurement platforms.
- Hughes Safety Company (Sarnia, Ontario) — A designer and producer of ANSI-compliant units with global reach. Hughes’ profile suits multinational customers requiring consistent specifications across sites. Strategic implication: Hughes is a partner candidate for cross-border procurement standards harmonization.
- LOC Scientific — Specialist laboratory-focused provider. LOC’s niche focus on lab specifications and small-footprint installations gives it advantage in research and clinical settings. Strategic implication: buyers in lab environments should evaluate LOC for fit-for-purpose products and compatibility with lab safety protocols.
- Unicare (India) — An in‑house engineering manufacturer with cost-competitive positioning for industrial and laboratory applications in emerging markets. Strategic implication: Unicare is a pragmatic partner for cost optimization and localized manufacturing strategies.
- EyewashDirect.com — Distributor and parts specialist aggregating multiple OEM offerings for fast fulfillment. Strategic implication: EyewashDirect is an enabler for buyers seeking quick replacements and for OEMs wanting distribution reach without heavy channel investment.
- Sysbel Manufacturing (China) — A supplier with laboratory and industrial systems and a foothold in regional markets. Strategic implication: Sysbel represents both a sourcing option for cost-sensitive buyers and a possible competitor where local content matters.
Implications and recommended 2026 actions by stakeholder
Below are high‑leverage actions that stakeholders should consider in 2026. Each action is tied to an operational objective the full report helps achieve.
- OEMs: Move from unit sales to bundled service models — pilot subscription-based maintenance contracts, test remote-monitoring add-ons, and price tandems by TCO rather than unit cost.
- Distributors: Build service capabilities and inspection packages to differentiate. Leverage e-commerce to reduce order-to-fulfillment times for replacement cartridges and parts.
- End-users (Chemical, Pharma, Electronics, Oil & Gas): Convert compliance audits into capital planning: prioritize installations by risk matrix, lock in multi-year service agreements, and require telemetry-ready units in new specifications.
- Investors and M&A teams: Target bolt-on acquisitions that add local manufacturing, testing labs, or service infrastructure. Use PW’s valuation multiples and synergy templates to size accretive deals.
- Regulatory and EHS teams: Implement a standardized inspection, recordkeeping, and training cadence based on ANSI/ISEA Z358.1 guidelines and the OSHA referral framework to reduce audit risk.
90-day operational roadmap: convert insight to action
- Days 0–30: Use the report’s compliance checklist to perform a rapid audit across critical sites; identify units due for replacement or retrofit.
- Days 31–60: Pilot a service-subscription offering or sign short-term service contracts at three representative sites; test remote monitoring options if available.
- Days 61–90: Finalize supplier scorecards and procurement terms, and prepare one strategic partnership or small acquisition target based on identified capability gaps.
Conclusion — the strategic edge for 2026
By 2026, decisions about eye wash stations will not be peripheral compliance choices but deliberate commercial tradeoffs with implications for cost structure, supplier strategy, and operational resilience. PW Consulting’s study converts historical performance and a 2026–2032 forecast (base year 2025; CAGR 4.65%) into prescriptive tools — from pricing templates and compliance playbooks to M&A heatmaps and GTM playbooks. The full dataset contains the granular regional, type, and application splits, detailed vendor share tables, and downloadable tools we intentionally omit here to preserve the trailer effect. For procurement teams, OEMs, and investors preparing to act in 2026, the full report provides the transaction‑grade intelligence required to move from consideration to execution.
Access the full PW Consulting Eye Wash Station Market report to unlock segment-level analysis, vendor scorecards, and implementation templates designed for decisive action in 2026.
For detailed analysis of this topic, please visit the official page: Eye Wash Station Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com