

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
Digital Panel Meter Market Set to Grow at 5.9% CAGR Through 2032 — PW Consulting

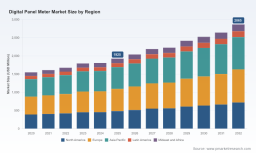
Digital Panel Meter Market — Strategic Preview for 2026 Decision-Makers
Executive positioning
As organizations confront accelerating requirements for real‑time measurement, energy visibility and tighter process control, digital panel meters (DPMs) are shifting from commoditised readouts to strategic nodes in industrial and energy architectures. PW Consulting’s latest market study — built on a 2020–2025 historical base with a 2026–2032 forecast horizon — quantifies that transition and translates it into executable choices for 2026. The market reached a meaningful milestone in the 2025 base year and is expected to expand at a steady mid‑single‑digit compound annual growth rate (CAGR) through the forecast period. This brief previews the study’s strategic value while keeping the detailed segment tables and proprietary scenario outputs gated for subscribers.
Digital Panel Meter Market
Macro trajectory and what it means for 2026 strategy
Between 2020 and 2025 the DPM market demonstrated resilience through supply‑chain shocks and shifting industrial demand patterns. In 2025, the market base is a clear signal that demand dynamics have normalised and are primed for structural growth driven by digitalisation and energy management investments. PW Consulting’s forecast projects continued expansion from the 2026 base, underpinned by a projected CAGR of approximately 5.9% over the 2026–2032 window.
Digital Panel Meter Market
For corporate strategists this macro trajectory implies three practical imperatives for 2026: (1) treat DPMs as strategic edge nodes in IIoT/OT stacks rather than as isolated components; (2) prioritise modular, networked product roadmaps that support cloud and native‑edge workflows; and (3) recalibrate commercial models towards solutions and services (subscription analytics, lifecycle maintenance) to capture incremental value as device capabilities converge with software platforms.
Digital Panel Meter Market
What the full report contains — practical, operational outputs
- Quantified market sizing and a consistent historical series (2020–2025) with a 2026–2032 forecast model expressed in USD (Million), enabling scenario analysis and sensitivity testing against macro inputs.
- Segment‑level structure by product families, application classes and regional lenses — presented with methodology notes, demand drivers and underlying assumptions. (Note: granular tables and downloadable datasets are reserved for the full report.)
- Competitive landscaping featuring detailed company profiles, capability maps, product roadmaps, go‑to‑market strategies and M&A posture assessments.
- Technological deep dives on connectivity stacks, sensor integration, measurement accuracy trends and cybersecurity hygiene for embedded measurement devices.
- Commercial playbooks: pricing frameworks, channel optimisation for OEM/ODM relationships, and three actionable GTM archetypes tailored to incumbent manufacturers, new entrants, and systems integrators.
- Supply‑chain and manufacturing risk matrix with mitigation options (dual‑sourcing, regional assembly, design for manufacturability), plus working capital and lead‑time scenarios for 2026 planning.
- Regulatory and standards roadmap that correlates upcoming measurement, safety and energy reporting requirements with commercial timing, helping prioritise compliance investments.
Competitive landscape — who matters and why
The DPM market is characterised by a moderate level of concentration: the three largest players account for roughly low‑to‑mid thirties percent of the market, while the top five capture the low forties percent. This structure presents a dual landscape: established global leaders with systems integration capabilities, and numerous regional/OEM specialists competing on price, form‑factor and delivery speed. That balance creates opportunities for both consolidation and targeted differentiation.
Below are strategic observations about leading vendors and the competitive implications for 2026 decisions:
- Murata Power Solutions (Japan) — Murata’s multi‑decade pedigree in power and precision positions it to capitalise on customers that require accuracy and reliability in both DC and AC line‑voltage monitoring. Their focus on self‑powered and quartz‑accurate models signals an approach tailored to mission‑critical use cases where uptime and measurement confidence are primary buying criteria.
- Schneider Electric (France) — With its Harmony series and broader energy management ecosystem, Schneider is leveraging DPMs as embedded elements of building and process automation suites. Strategic partnerships with renewables and energy services firms indicate Schneider’s play to capture higher value through integrated hardware–software solutions.
- Red Lion Controls (United States) — Red Lion remains a go‑to for high‑precision industrial instrumentation and offers a strong channel presence among automation suppliers. Their strength lies in process‑grade displays and integration depth for OEMs and system integrators.
- Autonics (South Korea) — As a supplier of compact, cost‑efficient OEM meters, Autonics is well‑positioned where unit economics and board space matter. Their models are likely to continue to capture demand in high‑volume industrial appliances and embedded control panels.
- Siemens (Germany) and ABB (Switzerland) — Both incumbents embed panel meters into broader automation and smart manufacturing suites. The strategic advantage for buyers is simplified integration into MES/SCADA stacks and harmonised lifecycle support; the implication for competitors is the need to offer interoperable, standards‑based interfaces.
- Guangzhou EcoNewlink (China) — Automated OEM/ODM capabilities and global certifications make EcoNewlink a competitive option for electrical panel builders and global distributors seeking cost‑effective scale and bespoke designs.
- Omron (Japan), Phoenix Contact (Germany), Carlo Gavazzi (Switzerland), Precision Digital (USA), Yokogawa (Japan) — These firms collectively span a spectrum from modular process automation to specialised energy monitoring, offering buyers differentiated value propositions ranging from connectivity to lab‑grade accuracy and cloud integration.
Recent product and platform trends to watch in 2026
- Connectivity is now table stakes. Recent product launches and platform releases throughout 2025–early 2026 emphasise Bluetooth, MQTT, webserver functionality and cloud APIs. Devices that are “network‑aware” unlock service and analytics revenue and create stickiness with enterprise software partners.
- Cloud‑native monitoring platforms are moving from optional to strategic. Vendors introducing real‑time analysis and data‑centric platforms are enhancing the value of physical meters by enabling continuous diagnostics and predictive maintenance use cases.
- Partnerships between meter OEMs and renewable/energy firms indicate accelerating demand for integrated energy‑management stacks that combine measurement, control and optimisation — an important vector for renewables integration and demand response programs.
- Feature differentiation is centred on lifecycle usability: higher digit counts, improved accuracy, modular I/O and simplified commissioning interfaces are becoming key purchase drivers for industrial buyers.
Strategic recommendations for 2026
- Prioritise interoperability: Invest in open APIs and standards‑based communication (e.g., MQTT, OPC UA) to ensure product longevity and easier integration with MES/SCADA and cloud platforms.
- Move up the value chain: Evaluate subscription services for analytics, calibration and extended warranties. Even modest SaaS attachments materially increase customer lifetime value in a market with moderate concentration.
- Segment go‑to‑market by buyer economics: Differentiate product families between high‑precision, premium offerings for process industries and compact, cost‑optimised units for OEMs and panel builders.
- Hedge manufacturing risk: Implement dual‑sourcing for critical components and consider nearshoring assembly to reduce lead‑time variability and to meet regional compliance timelines.
- Watch M&A selectively: Targets with complementary software IP, edge analytics or regional channel strength are most likely to accelerate scale quickly given current concentration dynamics.
How PW Consulting’s study de‑risks your 2026 choices
Our research combines bottom‑up company intelligence, device‑level engineering trends and buyer interviews to generate a practical, executable roadmap for product, commercial and M&A decisions. The full dataset includes downloadable forecast spreadsheets, sensitivity scenarios (inflation, component lead‑time, energy policy shifts) and a prioritized implementation checklist that can be applied immediately by product leadership, corporate development teams and channel managers.
Next steps
This preview is designed to signal the strategic arc and immediate levers available in 2026. For procurement, product and corporate strategy leaders who require the underlying tables, region/application‑level forecasts, and company scorecards, please consult the full report on our website. The deeper intelligence is partitioned to protect proprietary modelling and to give subscribers the actionable granularity needed to move from planning to execution.
PW Consulting stands ready to support tailored scenario workshops, competitor benchmarking engagements and M&A target screening based on the full Digital Panel Meter Market dataset and our practitioner playbooks.
For detailed analysis of this topic, please visit the official page: Digital Panel Meter Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com